
Debt-induced currency devaluation trades challenge the traditional relationship between gold and US Treasury yields

Huitong Network, October 6th — At the London Bullion Market Association Precious Metals Conference, experts pointed out that global high debt, inflation, and other factors are driving currency depreciation trades, with the traditional negative correlation between gold and bond yields weakening. As global debt continues to inflate and bond market buyer structures are changing, institutions see potential for increased gold allocation. In Asia, especially in major Asian countries, investors continue to buy gold on dips, while younger generations prefer gold as a store of value. In the long term, the outlook on gold remains bullish, but jewelry demand is falling as gold prices rise, meaning gold prices are likely to remain range-bound in the short term.
At the annual London Bullion Market Association Global Precious Metals Conference, several market experts noted that rising government debt, persistent inflation, and concerns over the long-term purchasing power of fiat currencies are fostering currency depreciation trades. The traditional linkage between gold and bond yields is coming under challenge.
This year’s panel, themed "Long-Term Patterns, Short-Term Trading: Interpreting Currency Depreciation Logic," was chaired by MKSPAMP's Head of Metals Strategy and Research, Nicky Shiels. Analysts and fund managers stated that despite higher global bond yields, gold remains resilient, reflecting increasing investor concern about fiscal situations worldwide.
Global Debt Pressure Mounts, Fiscal Discipline Remains Absent
Vikram Dhawan, Head of Commodities and Fund Manager at Nippon India Joint Fund, noted that the root of the currency depreciation narrative lies in the unsustainable burden of global debt. He said: "Global debt grows by trillions of dollars each year, leaving governments with few choices. They can only resort to some form of financial repression, essentially tolerating higher inflation while attempting to keep borrowing costs low. I see fiscal debt continually rising, but no evidence of fiscal discipline taking shape."
Shayne McGuire, Portfolio Manager at the Teacher Retirement System of Texas, pointed out that currency depreciation is not a new concept. Ancient governments devalued currency by reducing the precious metal content in coins, and now investors fear that mounting debt will ultimately erode the value of money itself. He said: “As debt risks rise, people are becoming more concerned about the shrinking purchasing power of money.”
According to historical patterns, surging global yields would usually severely hit gold prices, but the negative correlation between the two has evidently weakened. Even with bond yields breaching 5%, gold remains supported above $4,000. Vikram Dhawan said that in the short term, gold and yields are still negatively correlated, but in the one- to three-year period after the pandemic, the relationship has weakened significantly, sometimes even moving in tandem. He commented: “
Capital Structure Changes, Institutional Money Likely to Further Increase Gold Allocation
Dhawan believes that rising yields reflect higher term premiums rather than purely strong growth or monetary tightening expectations. The traditional buyer structure of sovereign bonds is shifting; central banks and pension funds, which were previously insensitive to price swings, are being replaced by private investors, who demand greater compensation to absorb duration and fiscal risk. This may continue to decouple the traditional link between gold and the bond market.
McGuire stated that the current issues in the bond market will drive gold further into institutional portfolios. For years, major US pension funds allocated little to gold in their strategic asset mixes, as small positions would hardly impact overall returns. He said: “As problems in the bond market become more apparent, this will inevitably change. Gold may not yield interest, but compared to many bonds, it has appreciated in value. Large institutions have yet to make gold a central part of their discussions, which is a key reason for my long-term optimism.”
Asian Demand Provides Support, Young Investors Favor Hard Assets
DymonAsia Macro Portfolio Manager Wei Yan stated that when domestic real estate and stock markets underperform, major Asian investors have limited options to preserve wealth, so high real yields in Western markets have limited suppressive effect on domestic gold demand. He said: “When the market pulls back, they keep buying. Gold tends to perform better during the Asian trading session, reflecting steady buying from investors in major Asian countries, whereas Western investors are less willing to chase prices higher amid high yield environments.”
Dhawan added that changing preferences among younger generations also favor gold. With persistent inflation, even as nominal assets rise, real purchasing power declines, leading more young people to prefer hard assets as a means of protection. He said: “For those wanting to allocate to hard assets, gold fits all their needs.”
Experts at the forum remain long-term bullish on gold, but caution that currency devaluation trades will not produce one-sided continuous rallies. Dhawan said that rising gold prices suppress traditional physical jewelry demand, so gold prices are likely to trade sideways in the short term. McGuire pointed out that during both Republican and Democratic administrations in the US, fiscal deficits have continued to expand, with no signs of substantive policy improvement. He said: “Regardless of which party is in power, debt and deficit issues remain neglected by the market.”
Conclusion
In summary, global high debt is reshaping the logic of gold pricing, with the traditional negative correlation between gold and bond yields gradually disappearing. Asian physical demand and institutional potential for increased allocation continue to support the long-term outlook for gold. However, in the short term, weakened jewelry demand means gold prices are likely to remain range-bound, making a one-way rally unlikely.
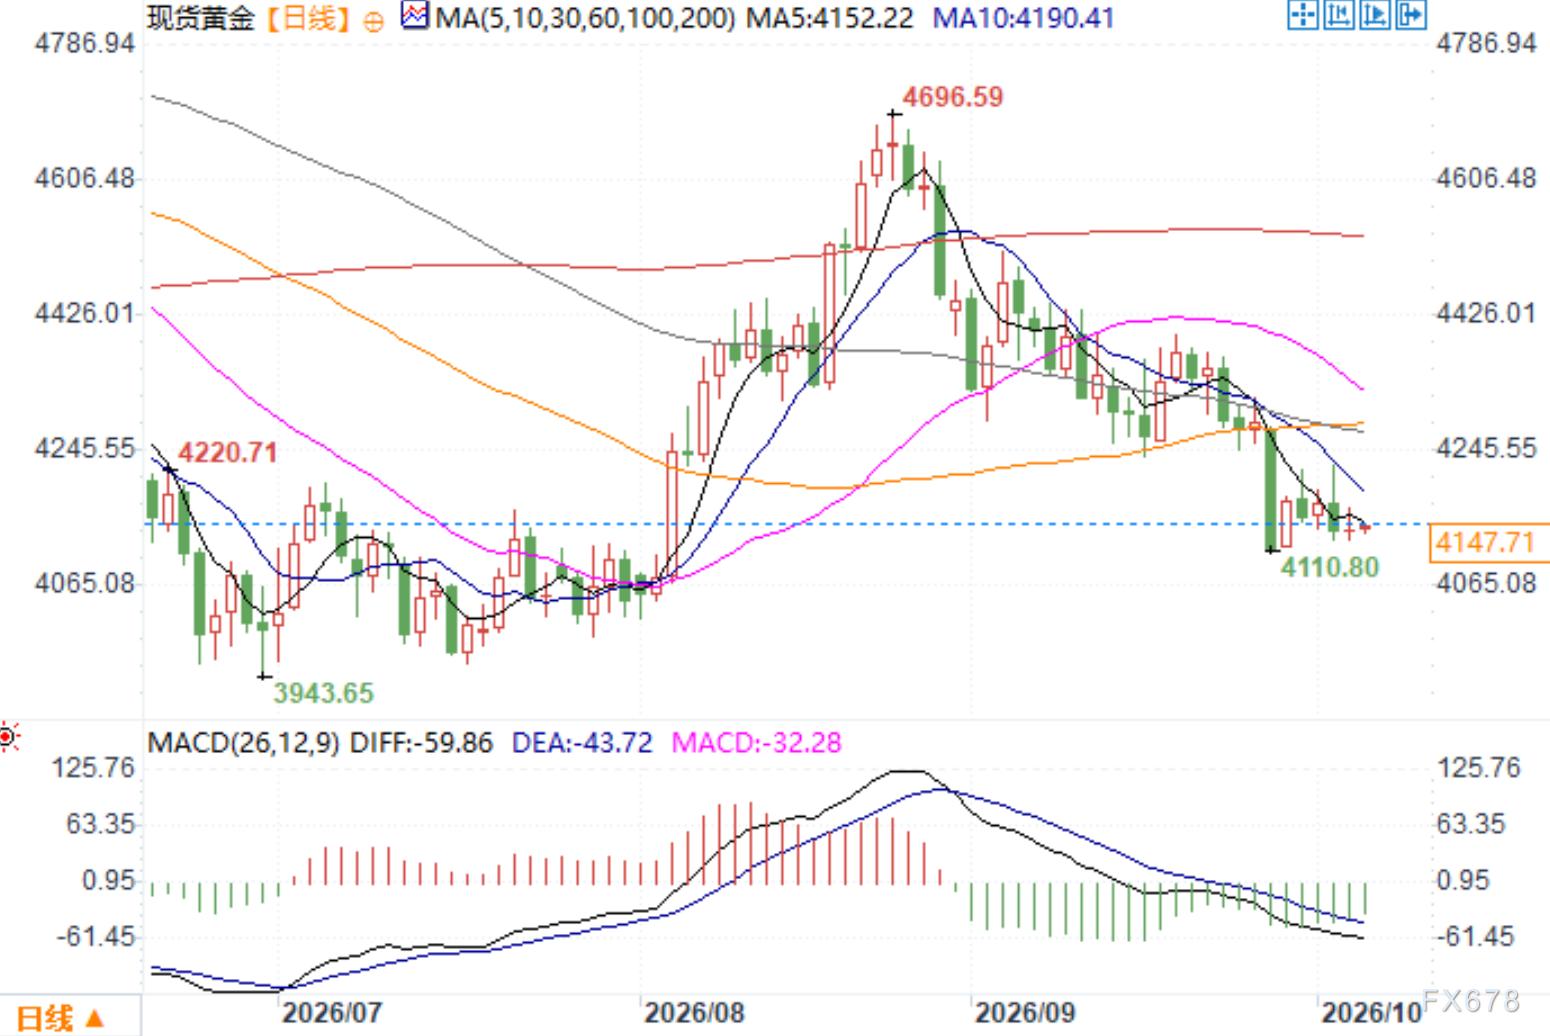
Spot gold daily chart Source: eHuitong
Beijing Time, October 6th, 8:59 — Spot gold quoted at $4,147.71/oz
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
SpaceX unlock wave meets index rebalancing! Goldman Sachs estimates: December rebalancing may bring $10.9 billion in passive buying
The proportion of SpaceX's freely tradable shares has increased from about 5% at the time of its IPO to one-third, and the expansion of index weightings is driving passive funds to increase their holdings. According to Goldman Sachs, the rebalancing of the Russell 1000 Growth Index on December 11 may trigger $10.9 billion in buy orders, with the main counterparts being insiders whose shares are unlocked. The S&P 500 inclusion window points to the second half of 2027, when the competition among passive funds will further intensify.
Citigroup Q3 Holdings: Nvidia (NVDA.US) Remains Top Heavy Position, Expanded Both Index and Tech Stock Options
According to the disclosure by the U.S. Securities and Exchange Commission (SEC), Citigroup (C.US) submitted its third quarter holdings report (13F) as of September 30, 2026, on November 4, 2026.

Carlyle still favors the healthcare sector in Q3, with Medline (MDLN.US) and StandardAero (SARO.US) accounting for over 98% of holdings
Carlyle (CG.US) has submitted its third-quarter holdings report (13F) for the period ending September 30, 2026.

Alphabet (GOOGL.US) reportedly plans to issue its first Hong Kong dollar and Singapore dollar bonds, potentially testing investor confidence amid growing concerns over AI financing.
Alphabet has recently held discussions about the potential issuance of its first Hong Kong dollar and Singapore dollar bonds. Amid global market volatility caused by sell-offs in artificial intelligence (AI) related sectors, this deal will test Asian investors’ appetite for subscription.

Crypto prices
More


