
The China-US interest rate spread has inverted by 300 basis points! Why does the RMB continue to appreciate against the trend?

Over the past year, the RMB exchange rate has shown a significant divergence from the China-US interest rate spread. Since starting its appreciation around April 2025 from near 7.35, the RMB/USD exchange rate has risen to around 6.72, with a cumulative increase of over 8%, approaching the highest level since 2023. So far in 2026, the RMB central parity rate has been adjusted upwards by a cumulative 66 basis points. Meanwhile, China's 10-year government bond yield has remained stable around 1.69%, while yields on US Treasury bonds of the same maturity have continued to hover above 4.71%, widening the negative China-US interest rate spread to about 300 basis points, which is at an extreme range not seen in the past 22 years.
This divergence means that the pricing power of the RMB has fundamentally shifted. The explanatory power of the interest rate spread between China and the US as a single factor for the RMB exchange rate has dropped sharply from 88% during 2022-2024 to just 1% since 2025. The rolling correlation coefficient between the RMB and the US Dollar Index also dropped significantly from 0.80 in November last year to -0.48 in August this year, marking the third notable decoupling since exchange rate reforms began. Meanwhile, the explanatory power of the rolling trade surplus has risen to 0.50, and is highly significant.
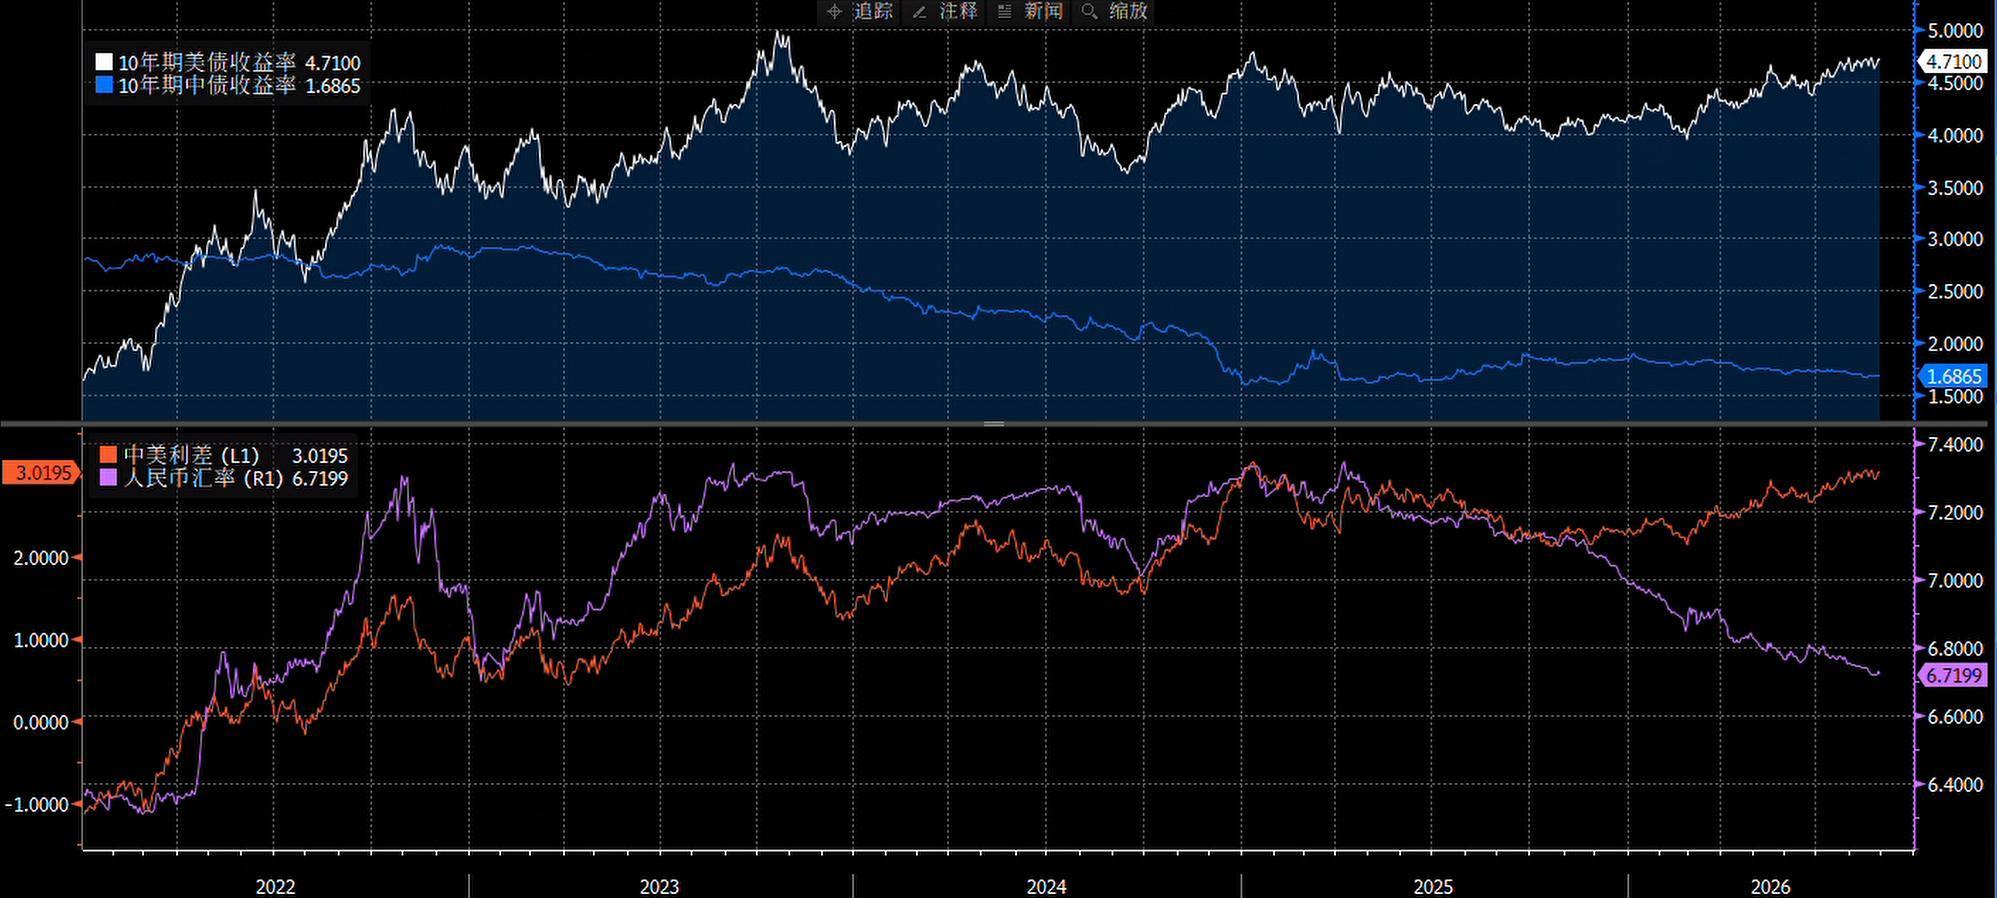
The dominant power over RMB pricing is shifting from the financial account to the trade account: cross-border capital flows driven by the China-US interest rate spread used to be the decisive force for exchange rate direction, but now the supply of foreign exchange under the current account and corporate forex settlement behaviors have taken on a greater role in price formation.
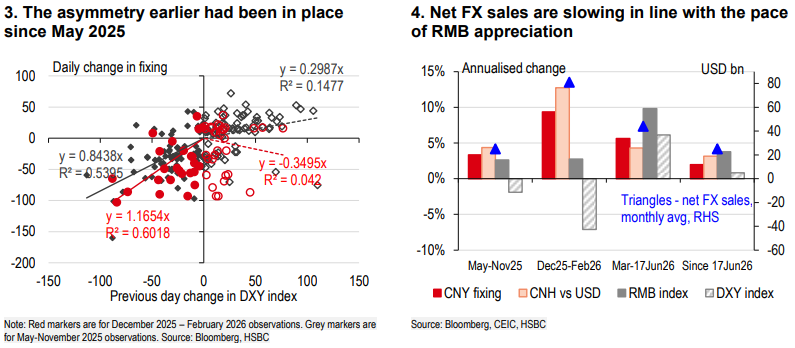
Currently, spread determines pressure, surplus determines direction
The interest rate spread firstly affects the financial account: higher returns on US assets reduce the relative attractiveness of RMB assets and drive increased outflows in securities investment, other investments, and bank cross-border capital. The persistent pressure on the financial account since 2021 shows that the spread pressure still exists. However, as the domestic capital account is not yet fully open, this pressure is difficult to translate directly and seamlessly into sustained depreciation pressure in the onshore RMB market.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
HBAR Price Eyes $0.155 as Traders Watch Key Recovery Levels
Microsoft Beats Nvidia for the First Time Since 2025: So Why Is MSFT Stock Falling?
Gunnison hits rich copper and zinc in Arizona
EIA expects Brent crude spot prices to remain at $100 per barrel for the rest of the year and raises the average price forecasts for this year and next.
The U.S. Energy Information Administration (EIA) has raised its forecast for average Brent crude oil prices in 2026 and 2027 to $97 and $86, respectively, reflecting pressures from global inventory declines, Middle East supply disruptions, and rising transportation costs. As oil production in the Middle East gradually recovers and global inventories rebound from low levels, the EIA expects the average spot price of Brent crude to fall to $87 per barrel in the second quarter of 2027, and further decline to $77 per barrel by the fourth quarter.

Crypto prices
More


