
American monetary historian worries about a sudden collapse in confidence in the US dollar, suggests reducing US Treasury holdings and allocating to gold

FX168 August 25 Report—— Economist Eichengreen stated that the central banks’ massive gold purchases in recent years are mostly not acts against the dollar, but he worries that confidence in the dollar could collapse suddenly. Data shows that among the reserve share lost by the dollar, the euro has gained nothing, Asian major currencies have captured about a quarter, with the remainder flowing to non-traditional currencies such as the Australian dollar, Canadian dollar, and Korean won. He recommends reducing holdings of bonds and increasing allocation to alternative assets like gold, and believes the U.S. may be betting the wrong way on stablecoins. This Friday (August 28), the new Federal Reserve Chair Kevin Warsh will make his debut at the Jackson Hole Symposium.
Gold closed above $4,600 per ounce last Friday (August 21), the dollar index fell to its lowest point since May, while the U.S. Treasury was quietly suppressing its own financing costs. Meanwhile, central banks have increased gold holdings by more than 1,000 tons annually for several consecutive years, equivalent to nearly a quarter of the world's annual gold production. Confronted with this, University of California, Berkeley economist Barry Eichengreen offered an unexpected assessment: most central banks buying gold are not casting a vote against the dollar.
This authoritative scholar on international monetary flows stated: "Personally, I do not believe gold will once again become the core of the international monetary and financial system." However, he has changed his view on another matter, and can precisely state the day that happened. He said: "
This is important because Eichengreen has typically been the calm voice in this debate throughout his career. When others cried out about the dollar’s decline, he focused only on the slow trend: the dollar’s share of global foreign exchange reserves is dropping by about 0.5 percentage points each year, from over 70% at the turn of the century to less than 60% today.
Who is capturing the ground relinquished by the dollar?
The IMF does not release detailed data on the currencies absorbing the dollar's lost share, so Eichengreen and his co-authors dug through annual reports from about 80 central banks. The results were surprising: "The euro has gained nothing from the dollar’s lost reserve share in the 21st century, Asian major currencies gained about a quarter, and the remaining three-quarters were taken up by these non-traditional reserve currencies." He was referring to the Australian dollar, Canadian dollar, Singapore dollar, New Zealand dollar, Nordic currencies, and the Korean won, "all currencies from small, open, well-governed countries that generally practice inflation targeting."
The reason the euro is treading water is simple: insufficient investable assets. Eichengreen notes that only three eurozone government bonds have AAA ratings from all major rating agencies, totaling around $4 trillion, compared to $40 trillion in U.S. Treasury bonds. He says: "German banks hold German government bonds, Dutch insurers hold Dutch government bonds, and these markets are fragmented from each other."
Why are central banks scrambling for gold?
Eichengreen traces the source of the gold-buying wave back to the 2008 financial crisis, rather than disputes with Washington. He notes that most emerging market central banks did not inherit gold reserves and started from a very low base, saying: "I think this was mostly structural catch-up, until quite recently, and I am not entirely sure how recent buying should be interpreted.
Gold struggles to serve as a means of payment
Eichengreen argues for gold's limitations in the strictest sense. Money must serve three functions: unit of account, means of payment, and store of value, but gold can only effectively fulfill one of them.
He notes: "Would you want your monthly salary denominated in ounces of gold? At the supermarket you might find it has depreciated by 10% more than you expected." He also shares a story from his new book: Sanctioned Venezuela paid sanctioned Iran for oil field equipment repair services with gold bars, then hired two Russian planes to transport the gold from Caracas to Tehran. This precisely illustrates the inconvenience of using gold for regular payments."
Reducing bond holdings: the signal is already here
Ray Dalio stated last Friday that investors should allocate 10% to 15% of portfolios to gold to hedge against the U.S. debt crisis he expects within three years; Saxo Bank’s Ole Hansen recommends a 5% to 10% allocation to hard assets.
Eichengreen first responds calmly: "People like Dalio have been predicting fiscal and financial crises for a long time—they will keep predicting until they are right." Then he shifts tone: "The U.S. is indeed on an unsustainable fiscal path, the debt-to-GDP ratio keeps rising, and Treasury investors are more worried now than ever."
He points to the key issue: "Treasuries have always been viewed as the safe-haven cornerstone of the 60/40 portfolio. If they are no longer safe and become highly correlated with equities,
Fragility in the U.S. debt market and the wrong bet
Eichengreen’s sharpest commentary is not about gold. Last month, Washington supported the yen using euro rather than dollar settlement; it also prompted the Fed to expand its facilities so the Bank of Japan could pledge Treasuries for cash rather than selling them; and just days ago, the Treasury doubled its long-term bond buyback program.
He asserts that these moves have not achieved the desired outcome: "I don't think these tricks will fool the market,
Eichengreen also believes the U.S. might be betting on the wrong technology. The GENIUS Act, signed in July 2025, is the first federal law to cover payment stablecoins, requiring issuers to fully back stablecoins with cash, deposits, and short-term Treasuries, make monthly reserve disclosures, and accept independent audits—effectively entrusting the digital future of the dollar to private companies that hold U.S. Treasuries. In contrast, Europe and Asian major economies are moving in the opposite direction, developing central bank digital currencies. He comments: "Over the long run, betting on central bank digital currencies may prove correct, whereas the U.S. bet on private stablecoins may be the wrong choice."
Conclusion
Eichengreen candidly admits to past mistakes: "In 2011, I wrote 'Exorbitant Privilege', predicting the dollar would yield to the euro and Asian major currencies. I was wrong—the funds did not flow to the euro or Asian major currencies, but instead to those non-traditional reserve currencies." He quotes Keynes: "What do you do when the facts change? He said, I change my mind. What do you do, young man?"
This Friday (August 28), the new Fed Chair Kevin Warsh will deliver his first keynote speech at Jackson Hole, with the symposium focus on financial innovation and payments, directly placing the issues raised by Eichengreen before the Federal Reserve.
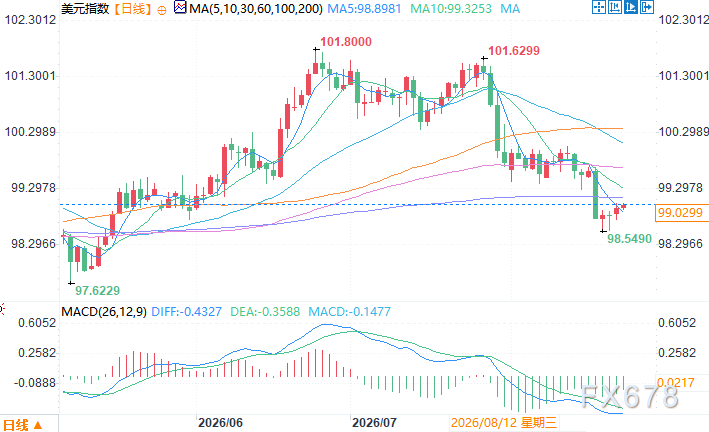
Dollar Index Daily Chart Source: FX168
GMT+8 August 25, 11:18 Dollar Index quoted at 99.03.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
The "Quantum Computing" Halo Can't Offset Fundamentals Growth Disappointment! Rigetti (RGTI.US) Fell Over 9% After Hours; Fidelity Meets Standards but Revenue Misses Expectations by 60%
This technology company focused on quantum computing has achieved its technical milestones, but its revenue falls far short of market consensus expectations. It has encountered significant setbacks in revenue, losses, and order acceptance progress, causing its stock price to drop by over 9% in after-hours trading on the US stock market.
Bank of Canada signals further interest rate hikes! Meeting minutes: High oil prices increase inflation risk, economic uncertainty will not hinder policy actions
The minutes of the Bank of Canada's October meeting reveal that, despite persistently high international oil prices and significant uncertainties in Canada's economic outlook caused by trade disputes with the United States, policymakers believe these risks do not mean the central bank must pause its actions.

Federal Reserve officials intensively deliver hawkish remarks! Waller calls for a 50 basis point rate hike in December, Bowman warns that AI investment returns may fall short of expectations, potentially triggering a sharp correction in US stocks
Several Federal Reserve officials issued consecutive hawkish signals on Tuesday, stating that inflationary pressures in the United States remain persistent and that monetary policy still needs to be further tightened.

Overnight US Stocks | Fed Rate Hike Expectations Rise, Major Indexes Fall, Nvidia (NVDA.US) Continues to Drop 5.4%
At the close, the Dow Jones Index fell by 156.67 points, down 0.30%, to 52,233.08 points; the S&P 500 Index dropped 28.99 points, down 0.38%, to 7,520.95 points; and the Nasdaq Composite Index declined 187.26 points, down 0.74%, to 25,065.87 points.
Crypto prices
More


