
Gold breaks above $4,000 again

After gold traded sideways around $4,000 per ounce for some time, there are now signs of another breakout.
The traditional framework for analyzing gold has failed since 2020.
The reason is simple: the U.S. dollar is losing its status as the supreme reserve currency and is turning into just another commodity.
The biggest KPI for the Federal Reserve now is to produce dollars while also maintaining the dollar’s image and maximizing the total value of this commodity, the dollar.
The value of the dollar is primarily influenced by two factors: the overall national power of the United States and its fiscal discipline.
The tool for measuring the value of the dollar is gold.
Gold is not a commodity determined by supply and demand. Gold was the king before the fiat currency era, but lost its crown after fiat currency appeared. However, when fiat currency fails, gold will regain its original value—as money.
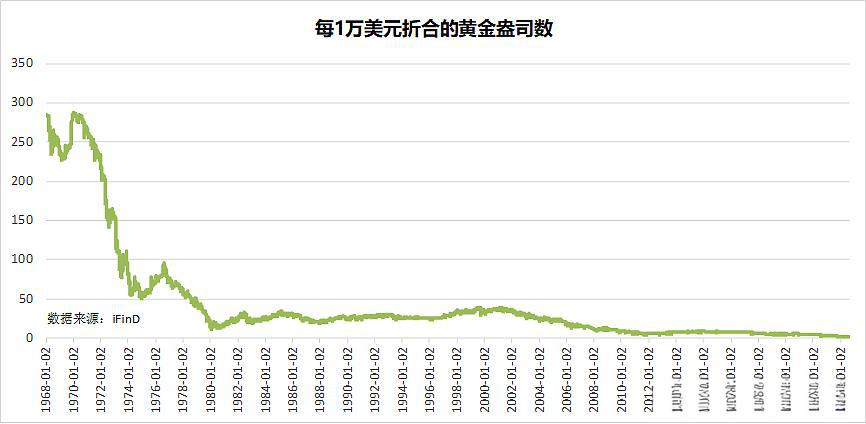
The value measured by $10,000 in gold is continuously shrinking. Before the 1970s, $10,000 could be exchanged for over 200 ounces of gold. What is that number today? As of August 11, 2026, $10,000 can only be exchanged for 2.28 ounces of gold.
From $10,000 exchanging for over 200 ounces of gold to now just 2.28 ounces, this illustrates the actual degree to which the dollar's real purchasing power has shrunk over the past fifty or sixty years.
To judge gold’s trend now is essentially predicting the intrinsic value of the dollar.
From the perspective of national power, opinions differ. Although compared to China, the United States is indeed on the decline, but compared to countries other than China, its relative position might still be higher.
The biggest current issue is fiscal discipline; as of August 2026, U.S. national debt has surpassed $40 trillion. If the current 4%-5% Treasury bond interest rate level continues, when interest expenses surpass military spending, it will trigger the "Ferguson Law," marking the end of the United States as a great power—just as happened in history with Spain and France.
The Federal Reserve is still holding out and refusing to cut rates, but I honestly don't believe it can withstand at this level of interest rate.
Therefore, the intrinsic value of the dollar will continue to decline, and the next wave downward will begin once the dollar starts to cut rates.
The Federal Reserve’s ability to manage the dollar, this unprecedented commodity, has already been almost perfect.
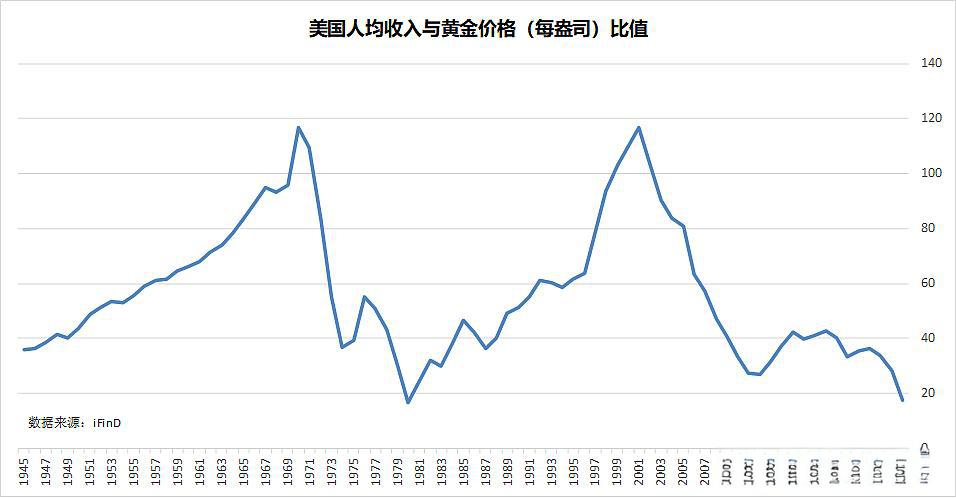
Let’s look at the chart above: the ratio of per capita income in the U.S. to the price of gold. From 1945 to the present, for the majority of the period, an average American’s income could be exchanged for more than 40 ounces of gold. Note, the ounce here is not the usual 28.35 grams, but the special troy ounce, which is 31.1 grams. Forty ounces of gold means that a typical American’s daily income could be exchanged for 3.4 grams of gold.
The peak ratio of U.S. per capita income to gold typically coincides with the peaks of U.S. national strength, such as in 1970 and 2001, when Americans could exchange their per capita income for over 100 ounces of gold. Historically, only twice has this value been below 20—once in 1980, and the other in the recent year 2025.
From a cyclical perspective, technical analysts would conclude that this ratio should "V" back. Since U.S. per capita income isn't changing much in the short term, it means the price of gold would need to drop sharply.
But from a fundamentals perspective, America’s decline is inevitable.
Looking at this chart, we can draw such a conclusion: For ordinary Americans, 2025 may have been the worst year in the past forty or fifty years, but it could turn out to be the best year in the next forty or fifty years, as per capita income could still be exchanged for 17 ounces of gold.
A side note here: the dollar is indeed weak, otherwise central banks worldwide wouldn't be rushing to exchange their dollar reserves for gold. But interestingly, the dollar has generally remained strong relative to the euro and yen.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Fear is the biggest short! Morgan Stanley calls for bottom-fishing in semiconductors: land and electricity shortages are not a problem, approved projects can't meet demand
Morgan Stanley believes that the recent sell-off in the semiconductor sector has been excessive, and that market panic rather than fundamentals is the biggest risk. Driven by demand for AI infrastructure, downstream orders continue to accelerate, with semiconductor supply remaining the core bottleneck. LPS constraints actually make growth more stable. The sector may fluctuate within a range in the short term and is currently near the bottom; prospects for the computing power and storage subsectors are favorable.

Indian Rupee extends rally amid continued FIIs buying, lower oil prices

Hashrate orders are booming, why is "AI trading" falling out of favor? JPMorgan reveals the time lag between AI investment and productivity realization
Joseph Lupton from the JP Morgan Global Economic Research Team pointed out in a research report on November 10 that recent improvements in labor productivity have been driven more by capital deepening and increased intensity of factor utilization. The broad efficiency gains from AI, resulting from process reconstruction, data integration, and organizational adjustments, will still take time to materialize. This means orders for chips, servers, and electrical equipment may grow first, but continuous investment returns for computing power operators and end users may not arrive at the same pace.
AI investment enters the "Trough of Disillusionment", the next 18 months will be a life-or-death test!
Goldman Sachs believes that the AI investment cycle is currently in the "trough of disillusionment," but this is not the first time. The core contradiction lies in the fact that the business models of new cloud computing providers are highly dependent on end-user returns from AI spending, while currently "there are basically zero companies that can attribute profits to AI." Social Capital founder Palihapitiya has clearly defined an 18-month key window, during which the market will decide which AI business models are sustainable and which are not.

Crypto prices
More


