
Strong employment sends a clear signal, can the Non-Farm Payrolls boost the US dollar index?

Morning FX
1. Fundamentals: The pattern of a strong U.S. and weak Europe continues to deepen
This week is a major one for the release of U.S. employment data, and the White House seems eager to showcase its achievements: On Monday evening, Hassett stated, "Indicators suggest the jobs report will be strong again," and on Tuesday evening, Boushey said "If June's employment data is very strong, it would not be surprising," directly signaling to the market that U.S. employment is robust. Due to this advance hint, the market showed almost no reaction to Tuesday's better-than-expected JOLTS and Wednesday's below-expectations ADP data.
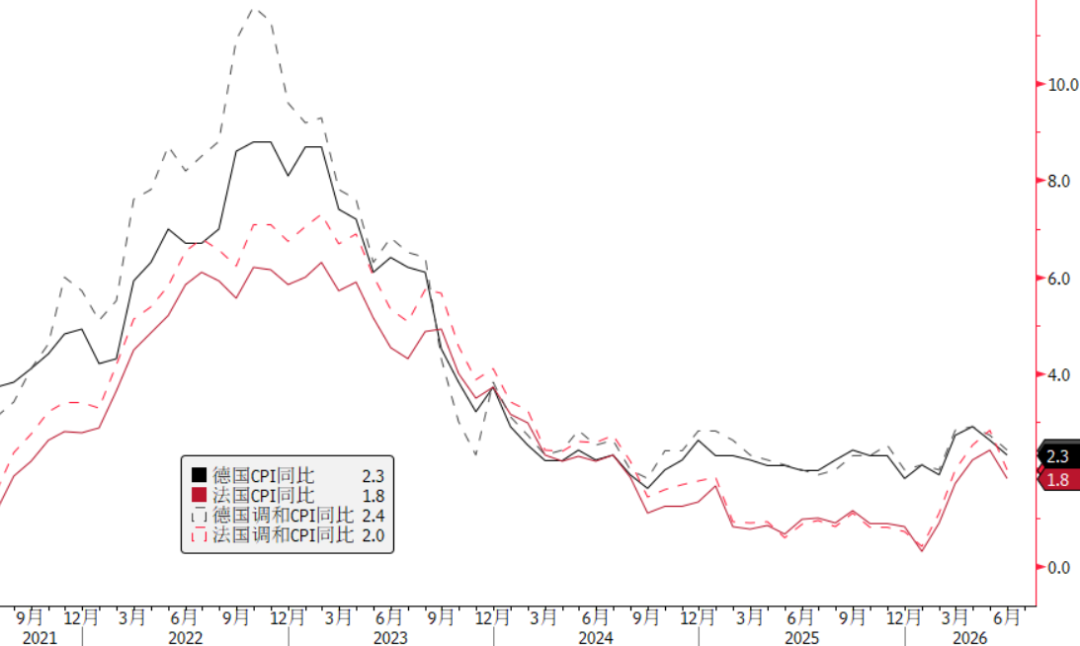
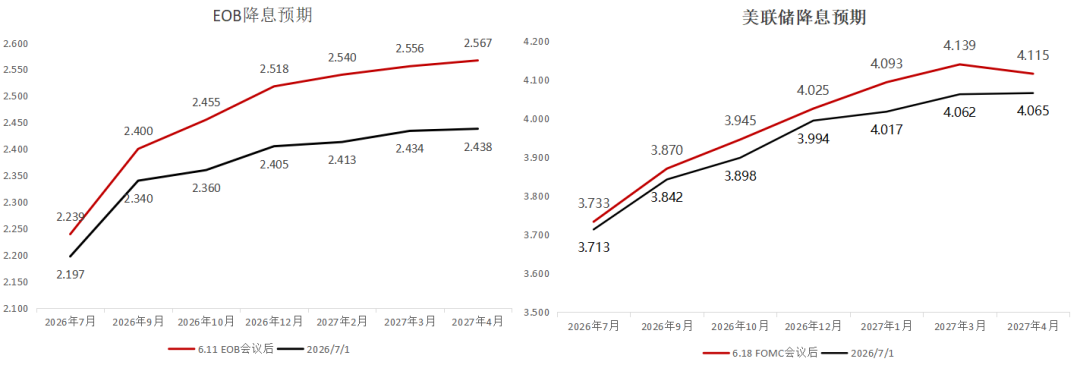
At the same time, the outlook in Europe is far from optimistic. German and French CPI data released on Tuesday and the Eurozone CPI released yesterday all fell short of expectations. The impact of the decline in oil prices in June has become apparent quickly, and expectations for ECB rate hikes this year have declined from 37bp after the June 11 meeting to 22bp.
2. U.S. Dollar Index gains lack momentum, what is the market hesitating about?
As we mentioned before regarding the crowded long position in the U.S. dollar, the current dollar bull position is quite crowded. For the dollar index to continue rising, the market's bullishness on the dollar would have to be stronger than at any point in the past decade. From this perspective, the dollar index will likely oscillate below the 102 resistance; but if it breaks above 102 and long positions hit record levels, a substantial rally could occur.
The fall in European CPI may not be an isolated incident; with the sharp drop in oil prices in June, global CPIs may have already passed their peak and begun to decline. If this trend also appears in the U.S. CPI data on July 14, U.S. interest rates could fall, interest rate differentials with non-U.S. currencies may narrow, and this might drive the dollar index lower.
3. Can Nonfarm Payrolls push the Dollar Index above 102?
Scenario 1 (20%): Nonfarm payroll data significantly exceeds expectations, especially if wage growth is above forecast. This is the scenario most likely to lift U.S. rates and the dollar index. However, due to the "spoilers" from the White House, market expectations have been raised, so it may require nonfarm payrolls to increase by over 200,000 (expectation: 110,000), unemployment rate to be stable or lower, and monthly wage growth above 0.4% to drive a breakout in the dollar index.
Scenario 2 (70%): Nonfarm payrolls come in only slightly better than expected or match expectations. The market will not react strongly, and the dollar index will continue to oscillate below 102.
Scenario 3 (10%): Nonfarm payrolls miss expectations. Considering both Hassett and Boushey have said the data won’t disappoint, this outcome is very unlikely. If it happens, it not only means the U.S. economy is not as strong as thought, but also calls into question the credibility of White House officials. This could deal a second blow to dollar credibility, potentially pushing the index down to around 100.
[June U.S. Nonfarm Payrolls Prediction Game]
Prediction target: The number of new U.S. nonfarm payrolls in June (market expectation: 110,000; previous value: 172,000). Leave your prediction in the comments section. The 5 participants whose predictions are closest to the actual value will receive a Morning FX-branded T-shirt, and those ranking 6th to 10th will receive a branded canvas bag. Go to the comments section and leave your guess!
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like

Wall Street giants collectively raise rate hike forecasts, US Treasury futures continue to fall, gold drops over 1% to break 4000
After the US October CPI exceeded expectations, Goldman Sachs and Nomura added a forecast for an interest rate hike in March next year, while Deutsche Bank included a forecast for a rate hike in January next year. Currently, the market has fully priced in a 25 basis point rate hike in December, with a 13% probability for a 50 basis point hike. On Wednesday, the US Treasury spot market was closed, but Treasury futures continued to fall, with corresponding yields rising by about 2 to 4 basis points, and spot gold came under pressure, dropping by 1.1%.

No Need to Worry About the Cooling Down of AI Data Center Construction? The US Import Boom Is Unlikely to Subside in the Short Term, Real Impact May Come in 2029
It takes an average of 4.8 years from finalizing investment to starting construction of a data center project, and an additional 2.6 years from construction start to becoming operational. Servers usually cannot be installed until after the building structure and racks are completed. For trade partners such as Taiwan (China), South Korea, and Mexico who rely on US data center supply chain demand, the inertia in construction timelines provides at least a one- to two-year buffer for future exports.

Federal Reserve Major Debate: When Should the Tenure of “Number Three” Williams End?
The main point of contention is whether Williams should step down in June 2028, upon completing a full 10-year term, or in June 2027, when he reaches the mandatory retirement age of 65. Analysts point out that the Federal Reserve Board holds ultimate discretion; if he leaves early, Fed Chair Waller would be able to assert greater control over the appointment to this critical position. However, forcing Williams to shorten his term could easily be interpreted as political manipulation. Williams himself is expected to serve until June 2028.

Crypto prices
More


