
SK Hynix ADR Set for Nasdaq Debut: Behind the $28.1B Raise, AI Memory Leader Faces "Bear Market" Headwinds
 2026/07/09 11:06
I. Not Just a "Simple Listing": The Second-Largest ADR Issuance in History
SK Hynix (000660.KR) will list on the Nasdaq Global Select Market as an ADR on Friday, July 10 (US Time), under the ticker SKHY.
Unlike a typical secondary listing, this is a substantial primary capital raise. The company is issuing 17.79 million new ordinary shares, packaged into ADRs at a 10:1 ratio, to raise capital directly from US and global investors. Due to a recent pullback in its Korean share price, the reference price has been adjusted downward from KRW 2.555 million to KRW 242,500 per ADR. Consequently, the total fundraising amount has been revised to approximately KRW 43.14 trillion (~$28.18 billion), resulting in a dilution rate of about 2.44%.
This issuance size remains exceptionally rare—second only to SpaceX’s record-breaking $85.7 billion IPO last month. It surpasses Saudi Aramco’s $25.6 billion listing in 2019 and Alibaba’s 2014 NYSE debut, marking one of the largest ADR offerings by a foreign company in history. Institutional interest has already reached $7 billion, with positive feedback from management roadshows.
However, there is a critical, often overlooked catalyst: Analysts widely expect SK Hynix to be included in the PHLX Semiconductor Sector Index (SOX) following its Nasdaq listing. This would trigger incremental buying from passive funds and help narrow the long-standing valuation discount SK Hynix trades at compared to US peers like Micron—a valuation reshaping path difficult to achieve within the Korean market framework alone.
The use of proceeds is specific: primarily for expanding production capacity in the Yongin and Cheongju semiconductor clusters, and purchasing advanced equipment such as EUV lithography machines, all serving HBM expansion and advanced packaging upgrades.
II. Investment Thesis: The HBM Moat – Real Performance, Not Just Hype
SK Hynix’s core value proposition today is HBM (High Bandwidth Memory), an indispensable component for AI large model training and inference.
Leveraging its early mass production of HBM3E and NVIDIA certification advantages, SK Hynix holds an estimated ~50% global HBM market share by revenue. It is a core supplier to AI giants like NVIDIA and Google, clearly leading Samsung and Micron in this niche sector.
Let the latest financial data speak: In Q2 2025, HBM accounted for over 40% of the company’s DRAM revenue and more than half of its DRAM operating profit, making it a true "profit engine." During the same period, the company’s overall operating margin hit a high of 41% (up 68% YoY), with operating profit double that of Samsung.
This is not concept hype; it is the realization of HBM demand on actual financial statements. Furthermore, nearly 70% of the company’s revenue comes from the US market. Listing in the US effectively aligns its capital market presence with its business重心 (core focus).
III. From HBM3E to HBM4: Growth Relay Continues, But Headwinds Persist
SK Hynix’s growth logic is shifting from HBM3E volume ramp-up to HBM4 mass production. As next-gen AI GPUs continue to demand higher bandwidth and capacity, companies that stabilize mass production first will remain beneficiaries.
However, we must acknowledge current headwinds: The memory chip sector has collectively weakened recently, with market concerns arising over rapid capacity expansion and whether AI hardware demand can sustainably absorb the new supply.
While SK Hynix’s Korean shares have risen significantly year-to-date, the pullback around the issuance launch was the direct cause of the reduced fundraising scale. This is a counter-trend financing move during a sector cooldown; short-term sentiment repair will take time.
IV. How to View ADR Pricing? Exchange Ratios and FX Rates Are Key
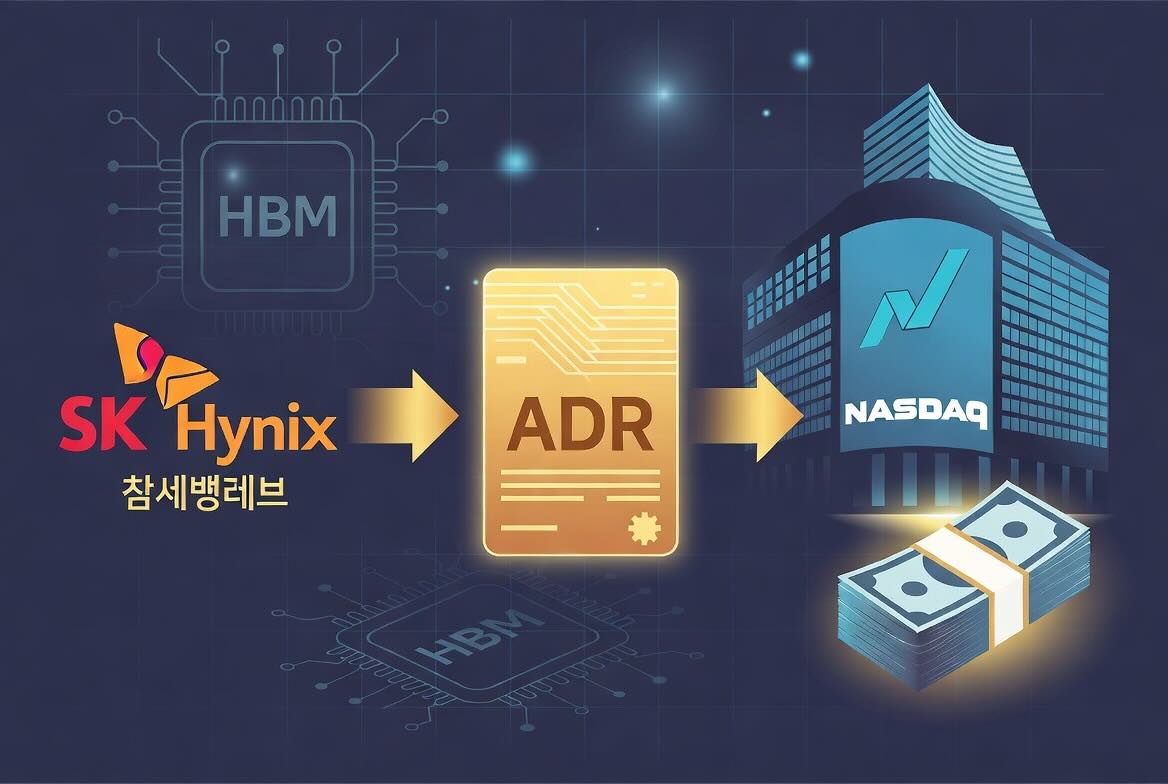
Upon seeing the ADR quote, many investors might mistakenly compare it directly: "Why is the US stock only ~$100+ while the Korean stock seems so expensive?" This comparison is flawed because ADRs typically have an exchange ratio. For SK Hynix, the structure is roughly 10 ADRs for 1 Korean share. By splitting 1 Korean share into 10 ADRs, the unit price becomes more accessible for US retail investors and smaller capital.
Example: If the Korean share price is high, the 10:1 split lowers the ADR unit price accordingly. You must also consider the KRW/USD exchange rate. Long-term, ADRs and ordinary shares represent the same equity interest, so their price trends are highly correlated. If the ordinary share rises, the ADR follows; if it falls, the ADR drops too.
Short-term discrepancies may occur due to time zone differences, FX fluctuations, varying investor sentiment in both markets, and conversion fees, but the general direction remains aligned.
This is why understanding the exchange ratio and real-time FX rates is crucial before investing in ADRs. Ignoring these factors can lead to misjudgments.
With this ADR listing, US investors can more conveniently participate in the growth of this global memory giant without navigating the complexities of the Korean market.
Conclusion
SK Hynix’s ADR listing is a capital move combining new equity financing, verified HBM performance, and pricing during a sector cooldown. In the short term, watch for capital inflows from the listing itself and potential SOX index inclusion. In the medium to long term, focus on the HBM4 mass production pace, ASP trends, and capacity utilization realization.
Notably, Bitget will list the SK Hynix ADR rToken (Ticker: SKHY) on day one, July 10. Since US new stock opening times vary, the rToken is expected to go live within 10 minutes of the market open, providing users with a convenient way to trade in USD. Stay tuned!
Investment Advice: Consider phased accumulation based on earnings season data (HBM shipments & margins) and the memory sector’s recovery rhythm, rather than chasing highs solely on the "story" phase.
(Data based on latest public information. Investment involves risks; please enter the market with caution.) operating margin hit a high of 41% (up 68% YoY), with operating profit double that of Samsung.
This is not concept hype; it is the realization of HBM demand on actual financial statements. Furthermore, nearly 70% of the company’s revenue comes from the US market. Listing in the US effectively aligns its capital market presence with its business重心 (core focus).
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like

Wall Street giants collectively raise rate hike forecasts, US Treasury futures continue to fall, gold drops over 1% to break 4000
After the US October CPI exceeded expectations, Goldman Sachs and Nomura added a forecast for an interest rate hike in March next year, while Deutsche Bank included a forecast for a rate hike in January next year. Currently, the market has fully priced in a 25 basis point rate hike in December, with a 13% probability for a 50 basis point hike. On Wednesday, the US Treasury spot market was closed, but Treasury futures continued to fall, with corresponding yields rising by about 2 to 4 basis points, and spot gold came under pressure, dropping by 1.1%.

No Need to Worry About the Cooling Down of AI Data Center Construction? The US Import Boom Is Unlikely to Subside in the Short Term, Real Impact May Come in 2029
It takes an average of 4.8 years from finalizing investment to starting construction of a data center project, and an additional 2.6 years from construction start to becoming operational. Servers usually cannot be installed until after the building structure and racks are completed. For trade partners such as Taiwan (China), South Korea, and Mexico who rely on US data center supply chain demand, the inertia in construction timelines provides at least a one- to two-year buffer for future exports.

Federal Reserve Major Debate: When Should the Tenure of “Number Three” Williams End?
The main point of contention is whether Williams should step down in June 2028, upon completing a full 10-year term, or in June 2027, when he reaches the mandatory retirement age of 65. Analysts point out that the Federal Reserve Board holds ultimate discretion; if he leaves early, Fed Chair Waller would be able to assert greater control over the appointment to this critical position. However, forcing Williams to shorten his term could easily be interpreted as political manipulation. Williams himself is expected to serve until June 2028.

Crypto prices
More


