
Gold: Trend Reversal or Range-bound Impulse?

On the evening of July 2, after the release of the US June non-farm payrolls, London gold surged nearly 2%, ending a four-week losing streak and closing at $4,174/oz. We need to calmly answer one question: is this rebound in gold prices the beginning of a trend reversal, or is it just a pulse at the upper end of its range?
I. Bottom Support: Central Banks “Support But Not Propel” Gold Prices
Central bank buying remains the fundamental “stock” support for gold prices. According to the World Gold Council (WGC)'s “2026 Central Bank Gold Reserve Survey” released in mid-June: 45% of surveyed central banks plan to increase their gold holdings in the next 12 months, a record high; 89% of central banks expect the proportion of global gold reserves to continue to rise. Since 2022, annual central bank gold purchases have averaged around 1,000 tons, doubling from 500 tons over the previous decade. Currently, gold has surpassed US Treasury bonds (27% vs 22%) as the world’s largest official reserve asset.
WGC June Central Bank Reserve Survey
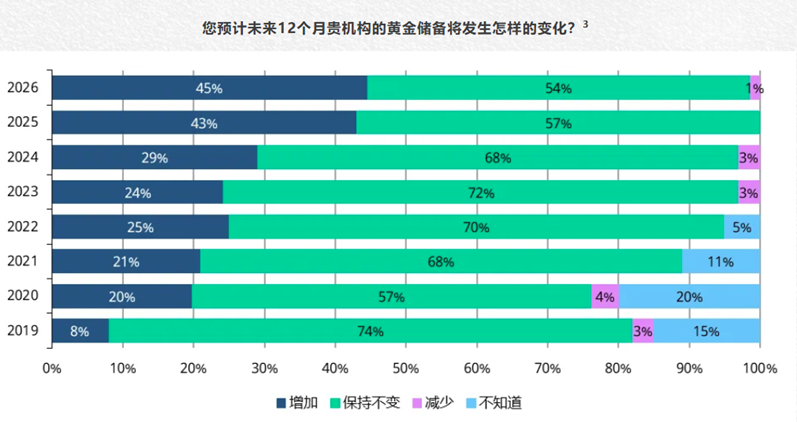
However, WGC also did the math: on top of a baseline average annual purchase of 600 tons, buying an additional 20-30 tons would only push up gold prices by about 1%. The signal from central bank gold buying is far more significant than its marginal effect on pricing. It can support gold prices around $3,800-$3,900, but alone it cannot drive a breakthrough. The real determinant of direction is interest rate expectations and risk appetite.
II. Fundamentals: The Three Major Catalysts Have Not Continued to Exert Force
To determine whether the rebound can escalate into a reversal, the core focus should be on the catalysts driving gold prices. In its “Mid-Year Gold Outlook 2026” released on July 1, WGC put the baseline scenario for gold prices in the second half of the year at 4100±5% (corresponding to a range of about $3,895-$4,305/oz), and clearly stated: for gold to regain an upward trend, at least one of the three major catalysts must continue to exert force:
① Significant deterioration in geopolitical risks; ② Trend reversal in interest rate expectations; ③ Long-term allocation capital flowing back.
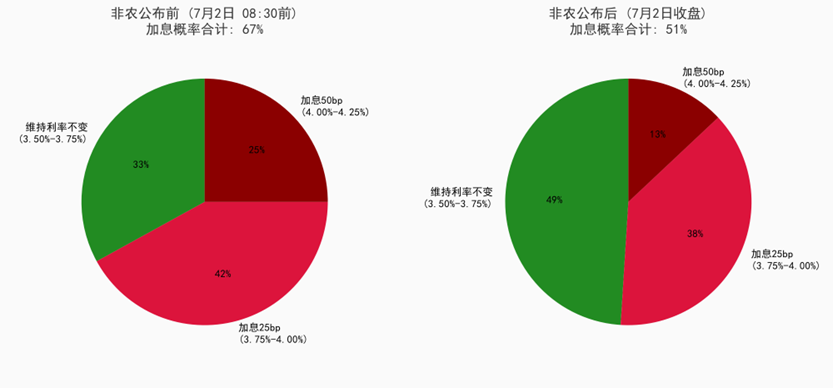
Comparing to the current market, this non-farm-led rebound only scratched the “edge” of the second point, i.e., a downgrade of rate hike expectations due to weaker single-month data. However, FedWatch data shows the probability of a Fed rate hike in December remains around 77%, far from a “trend reversal.” Both geopolitically and in terms of capital flows, the outlook remains less favorable: geopolitically, shipping in the Strait of Hormuz has recovered to pre-war levels; on the capital side, real rates remain high, with the SPDR Gold ETF still languishing at low levels and no sustained net inflows observed.
CME FedWatch ShowsChanges in Probability of Fed Rate Hike at September FOMC
III. Technicals: Oversold Correction Rather Than Trend Reversal
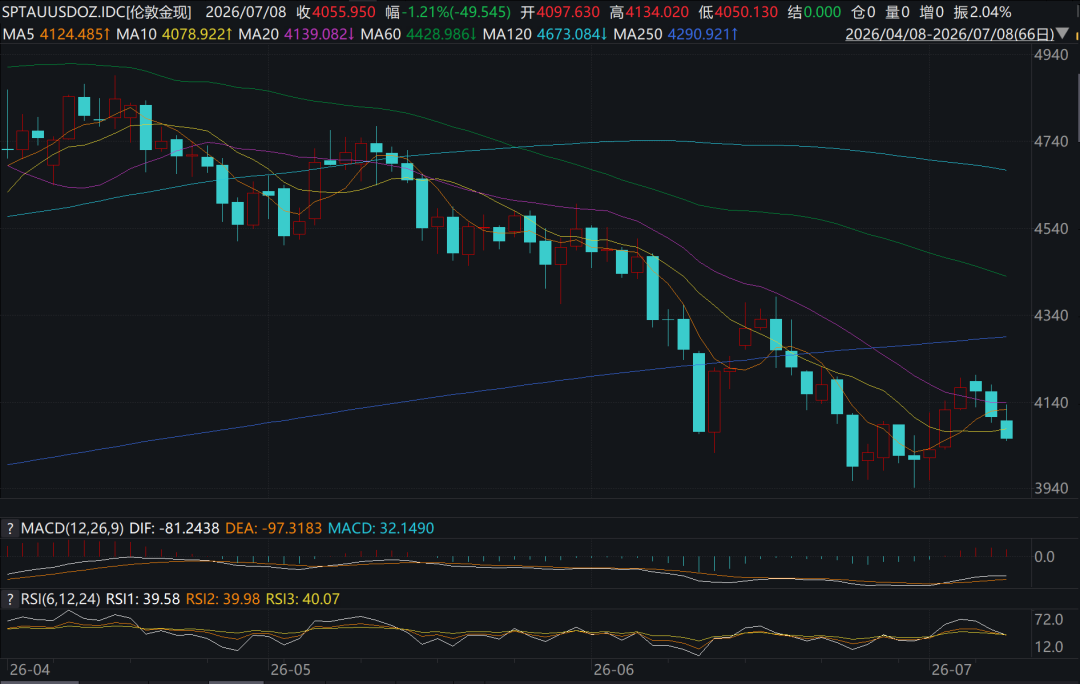
At the indicator level, the RSI (14-day) has recovered from the extremely oversold zone in late June to near 40, moving out of the panic selling area, but it has yet to enter the bullish dominance zone (typically above 50-55); the MACD dual lines also remain below the zero axis. Both point to the same judgment: the bulls have not yet regained dominance.
Spot Gold (London) Price Performance Over Past Three Months with MACD & RSI
IV. Conclusion: Range-bound Fluctuation Remains Gold’s Reasonable Pricing Pattern
Returning to the initial question, our core judgment is as follows:in the coming weeks, gold prices are expected to remain range-bound. From a medium- to long-term perspective, gold benefits from central bank buying, excessive monetary issuance, and the reconstruction of the global reserve system, so its long-term value direction is clear.
In the short term, focus on the US June CPI and the Fed’s July FOMC meeting: if core CPI falls and the FOMC leans dovish, the “reversal in interest rate expectations” in the WGC framework may truly begin; if CPI remains resilient and FOMC remains hawkish, then the non-farm rally will be disproved. Before CPI and the FOMC provide clear direction, responding with a broad range framework of 3900-4300 may be more effective than betting on a unilateral breakout.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like

Wall Street giants collectively raise rate hike forecasts, US Treasury futures continue to fall, gold drops over 1% to break 4000
After the US October CPI exceeded expectations, Goldman Sachs and Nomura added a forecast for an interest rate hike in March next year, while Deutsche Bank included a forecast for a rate hike in January next year. Currently, the market has fully priced in a 25 basis point rate hike in December, with a 13% probability for a 50 basis point hike. On Wednesday, the US Treasury spot market was closed, but Treasury futures continued to fall, with corresponding yields rising by about 2 to 4 basis points, and spot gold came under pressure, dropping by 1.1%.

No Need to Worry About the Cooling Down of AI Data Center Construction? The US Import Boom Is Unlikely to Subside in the Short Term, Real Impact May Come in 2029
It takes an average of 4.8 years from finalizing investment to starting construction of a data center project, and an additional 2.6 years from construction start to becoming operational. Servers usually cannot be installed until after the building structure and racks are completed. For trade partners such as Taiwan (China), South Korea, and Mexico who rely on US data center supply chain demand, the inertia in construction timelines provides at least a one- to two-year buffer for future exports.

Federal Reserve Major Debate: When Should the Tenure of “Number Three” Williams End?
The main point of contention is whether Williams should step down in June 2028, upon completing a full 10-year term, or in June 2027, when he reaches the mandatory retirement age of 65. Analysts point out that the Federal Reserve Board holds ultimate discretion; if he leaves early, Fed Chair Waller would be able to assert greater control over the appointment to this critical position. However, forcing Williams to shorten his term could easily be interpreted as political manipulation. Williams himself is expected to serve until June 2028.

Crypto prices
More


