
After the weak nonfarm payroll, what's the outlook for 10-year US Treasury bonds?

In June, the U.S. nonfarm payrolls increased by 57,000, lower than the market expectation of 113,000; the April and May figures were revised downward by a combined 74,000. On the surface, this is data that appears positive for U.S. Treasury bonds and negative for the dollar, but the market reaction was not entirely aligned with this view: On July 2, the yield on the U.S. 2-year Treasury note fell from 4.17% to 4.14%, while the 10-year rose from 4.48% to 4.49%, and the 2s10s spread widened from 31bp to 35bp. In other words, the market indeed bought into the short end, but did not simultaneously buy the long end. The first implication of weaker nonfarm payrolls is a diminished need for continued rate hikes, rather than an immediate shift to recession trades.
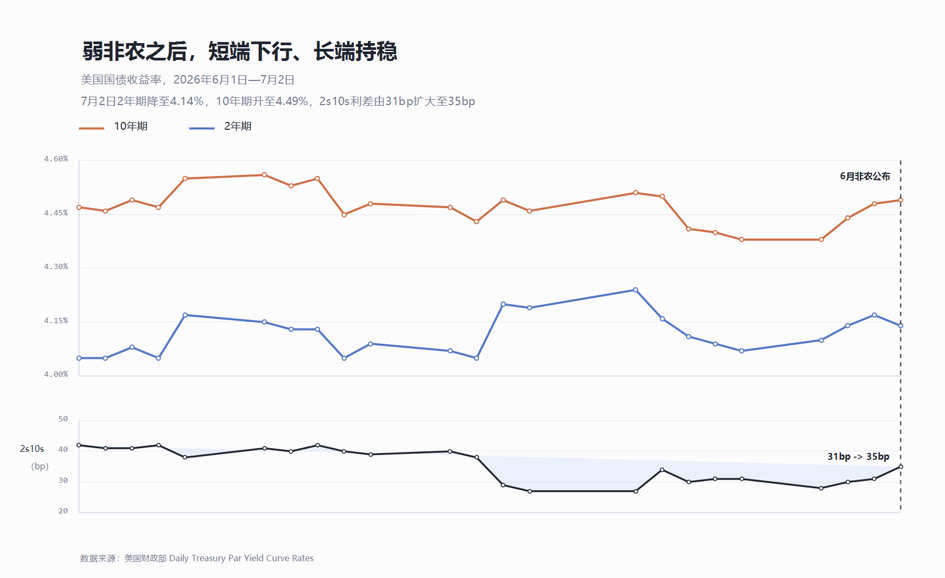
The decline at the short end is not hard to understand: the significant slowdown in nonfarm job additions, coupled with the downward revisions to the previous two months, shows that the labor market is not overheating. For the 2-year yield, the most direct trade is a lower tail risk of further rate hikes by the Federal Reserve. In other words, weak nonfarm data primarily reduces the probability of an "immediate hike" or "one more hike".
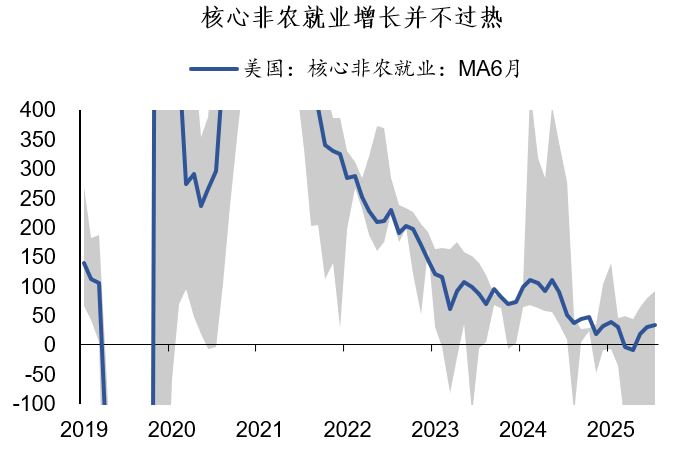
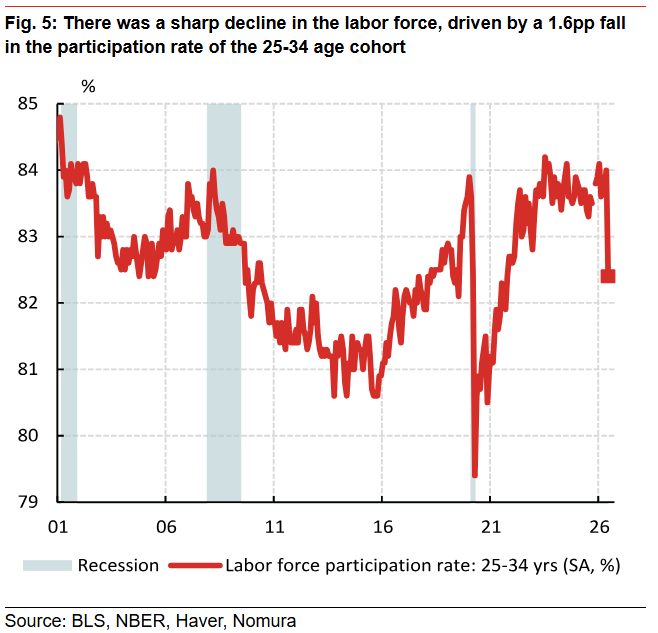
However, this data is not weak enough for the market to instantly jump to recession pricing. There are many temporary factors in the report: reduced employment in leisure and hospitality due to earlier hiring, and a 1.6 percentage point drop in the participation rate among the 25-34 age group. The message to the Federal Reserve is that it can be a little less hawkish and more patient, rather than needing to immediately shift to easing.
A single month of weak nonfarm payrolls only indicates a marginal slowdown in job creation, which is not enough to prove that long-term growth and the real interest rate center will quickly move lower,which is precisely why the 10-year yield did not move down significantly. At the same time, fiscal financing, Treasury supply, and capital spending such as on AI data centers are still generating financing demand. Weaker private sector credit does not mean an overall decline in U.S. total financing demand; government and AI investments are still supporting the center of long-term rates.
Therefore, after the weak nonfarm payrolls, the market is not pricing in an overall downward shift of the yield curve. With reduced hike expectations, the short end benefits more directly, while the 10-year only experiences lighter upward pressure and has not yet confirmed a trend reversal; a choppy view is maintained.
Looking ahead, CPI is the main data point to watch. If June’s CPI comes in significantly below expectations, the 10-year has a chance to test the 4.35%–4.40% range; if core inflation remains around 0.3% or higher, the yield may return above 4.50%.In the medium term, only when labor market cooling spreads to rising layoffs and weaker consumption, along with falling inflation, will the downside for the long end truly open up.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like

Wall Street giants collectively raise rate hike forecasts, US Treasury futures continue to fall, gold drops over 1% to break 4000
After the US October CPI exceeded expectations, Goldman Sachs and Nomura added a forecast for an interest rate hike in March next year, while Deutsche Bank included a forecast for a rate hike in January next year. Currently, the market has fully priced in a 25 basis point rate hike in December, with a 13% probability for a 50 basis point hike. On Wednesday, the US Treasury spot market was closed, but Treasury futures continued to fall, with corresponding yields rising by about 2 to 4 basis points, and spot gold came under pressure, dropping by 1.1%.

No Need to Worry About the Cooling Down of AI Data Center Construction? The US Import Boom Is Unlikely to Subside in the Short Term, Real Impact May Come in 2029
It takes an average of 4.8 years from finalizing investment to starting construction of a data center project, and an additional 2.6 years from construction start to becoming operational. Servers usually cannot be installed until after the building structure and racks are completed. For trade partners such as Taiwan (China), South Korea, and Mexico who rely on US data center supply chain demand, the inertia in construction timelines provides at least a one- to two-year buffer for future exports.

Federal Reserve Major Debate: When Should the Tenure of “Number Three” Williams End?
The main point of contention is whether Williams should step down in June 2028, upon completing a full 10-year term, or in June 2027, when he reaches the mandatory retirement age of 65. Analysts point out that the Federal Reserve Board holds ultimate discretion; if he leaves early, Fed Chair Waller would be able to assert greater control over the appointment to this critical position. However, forcing Williams to shorten his term could easily be interpreted as political manipulation. Williams himself is expected to serve until June 2028.

Crypto prices
More


