
Bitcoin recovers from Strategy's BTC sale, funding rates hit 9%: Are bulls back?

Key takeaways:
- Bitcoin derivatives show resilience despite bearish pressure from Strategy’s Bitcoin sales.
- Onchain Bitcoin data points to sellers’ exhaustion, strengthening the $60,000 support level.
Bitcoin price quickly recovered from the selloff to $61,300 that followed Strategy’s Bitcoin sale announcement. Despite the negative impact on traders' sentiment, the additional $216 million cash position eased concerns about the company's ability to pay dividends and cover its debt. Does the quick recovery suggest that Bitcoin bulls back in control?
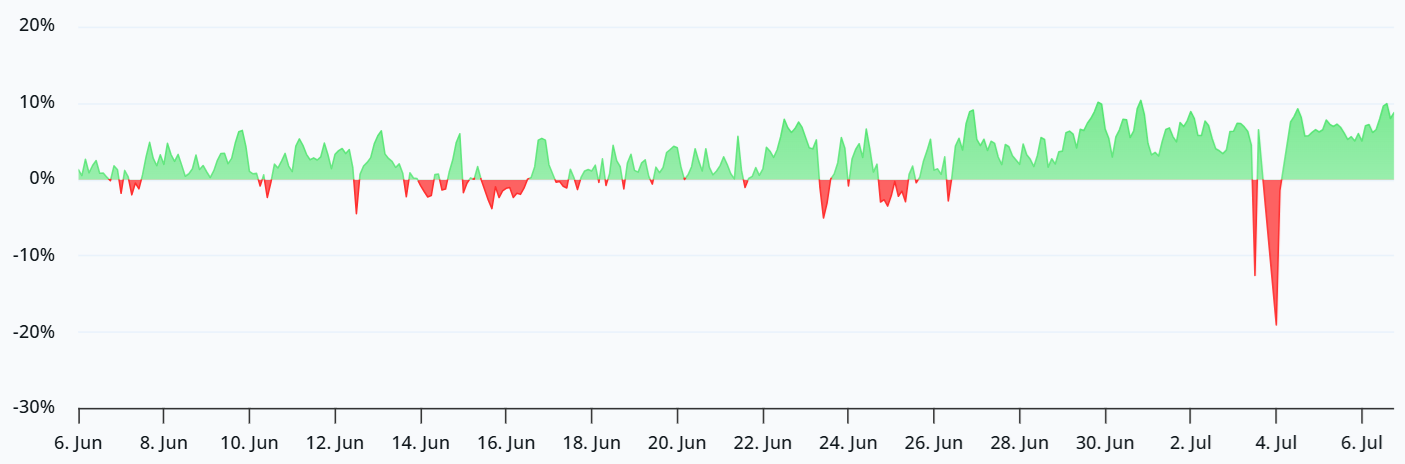
Bitcoin perpetual futures annualized funding rate. Source: Laevitas
The Bitcoin perpetual futures annualized funding rate jumped to 9% on Monday, indicating balanced demand between bullish and bearish leverage. While far from displaying conviction, the indicator distanced itself from the bearish momentum on Saturday marked by negative funding rates. But unlike the futures markets, Bitcoin options signaled minor stress on Monday.
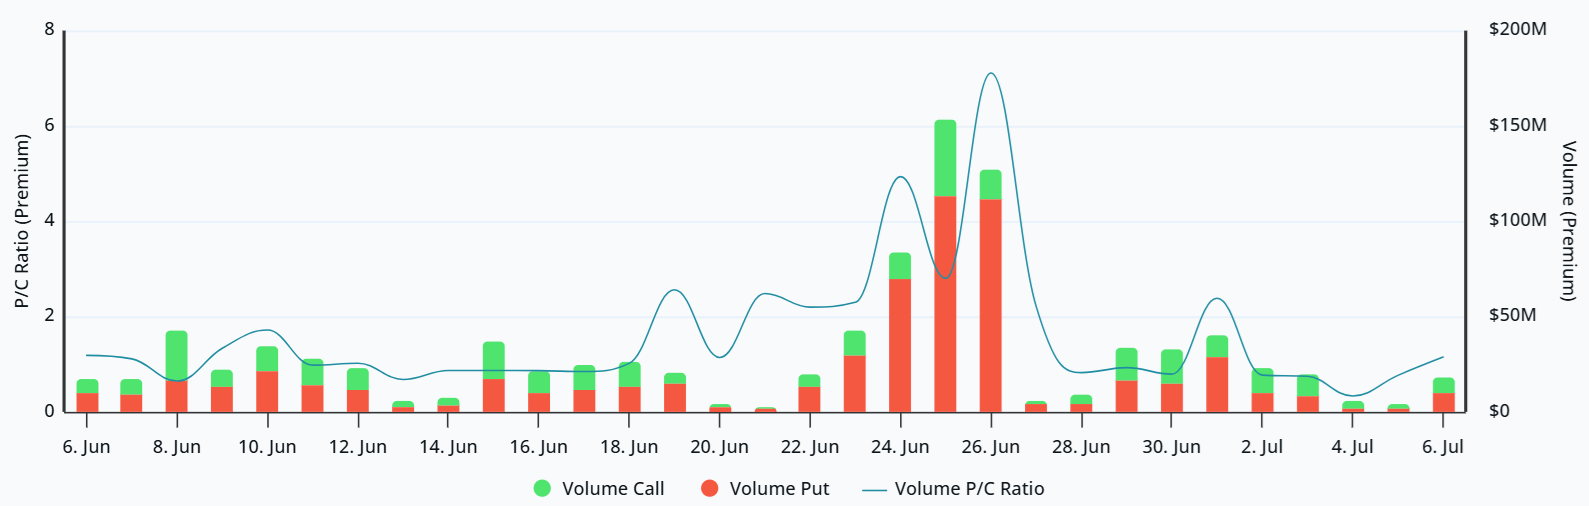
Bitcoin options premium put-to-call ratio at Deribit. Source: Laevitas
The put (sell) options premium at Deribit outpaced the equivalent call (buy) instruments on Monday, reverting the trend from Thursday and Friday. Typically, periods of stress can easily push the indicator above 2 times, hence the current 1.15 level remains under the neutral range. Bitcoin futures and options displayed resilience, although the bounce to $63,500 was unable to instill bullishness.
Bitcoin ETF flows reversal and long-term holders conviction favor $65,000 rally
Bitcoin bears might have underestimated the relevance of the $223 million net inflows into US-listed spot Bitcoin exchange-traded funds (ETFs) on Friday, the first after 10 consecutive outflows. The record-high $4.51 billion net outflows in June negatively impacted trader sentiment.
Still, the sell pressure will eventually subside, and the potential reversal in ETF flows could be enough to instill bullishness in Bitcoin derivatives markets.
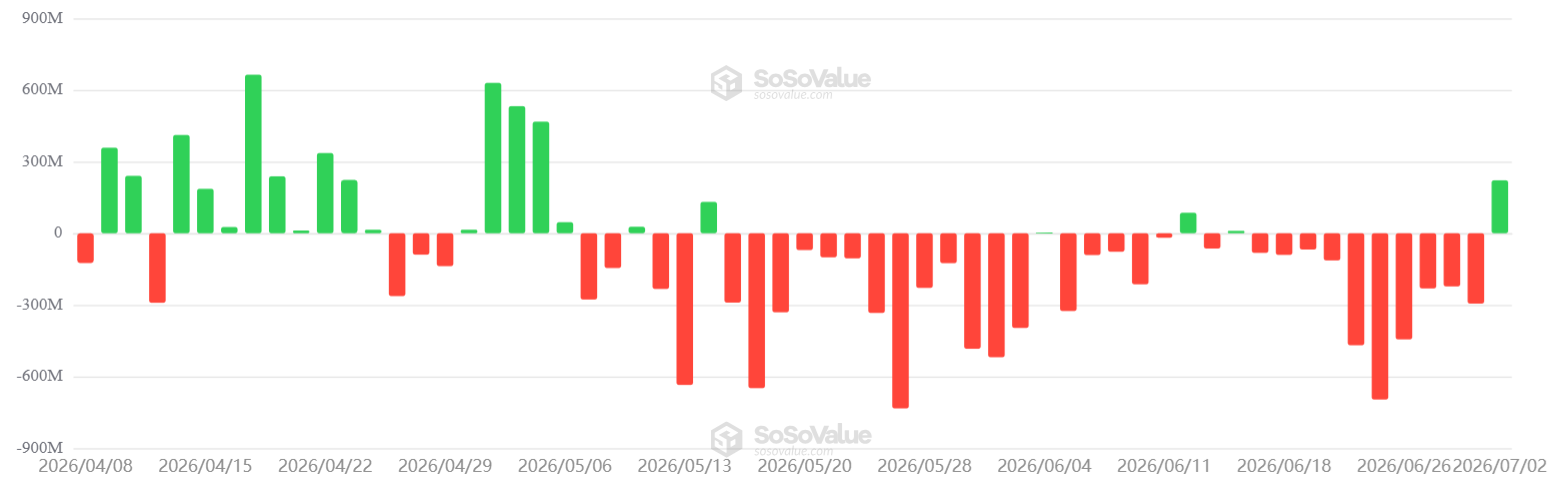
US-listed spot Bitcoin ETFs daily net flows, USD. Source: SoSoValue
Part of the recent bearishness can be pinned to the record drawdown in Strategy preferred perpetual equity Stretch (STRC US), which offers holders an attractive 12% yield. However, new stock issuance can occur only at the fixed $100 price; hence, the company currently has fewer instruments available to support the dividend payout.
Strategy holds sufficient cash reserves to cover 17 months of dividends; thus, the urgency of additional Bitcoin sales is debatable.
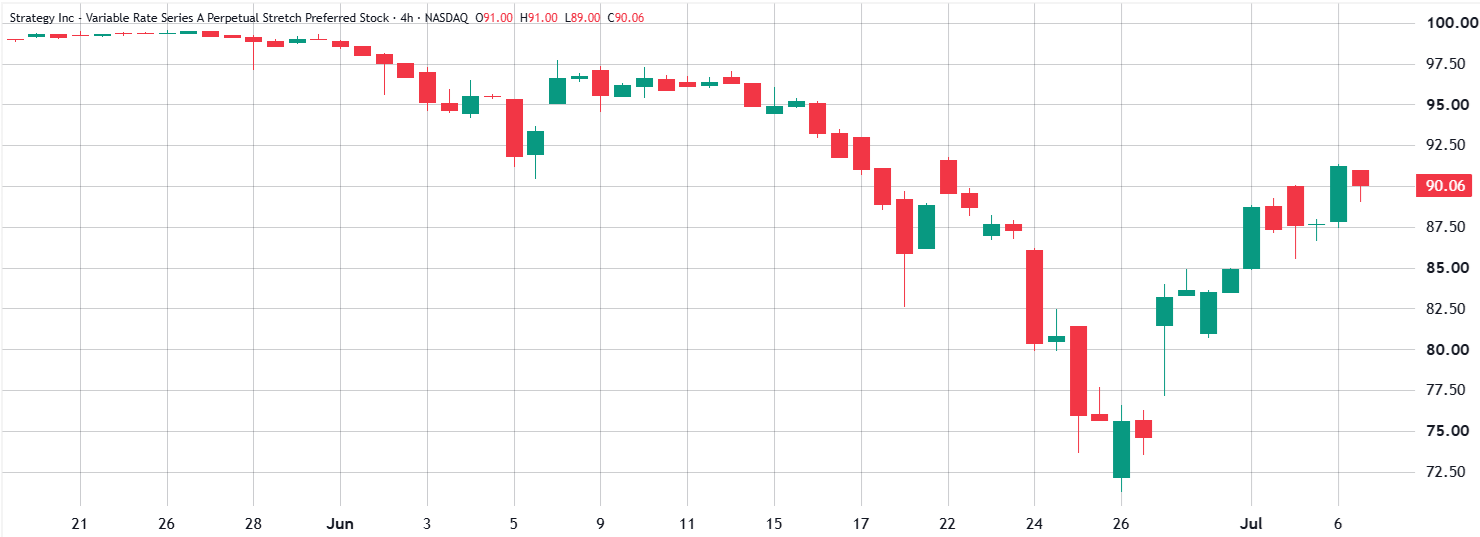
Strategy preferred perpetual equity Stretch (STRC US). Source: TradingView
Regardless of Strategy’s extremely low 8% debt leverage, Bitcoin bears have the upper hand as the company endures $8 billion in unrealized losses from its Bitcoin purchases. Bitcoin bulls' biggest hopes rely on long-term holders' conviction and onchain data pointing to selling exhaustion, strengthening the $60,000 support level.
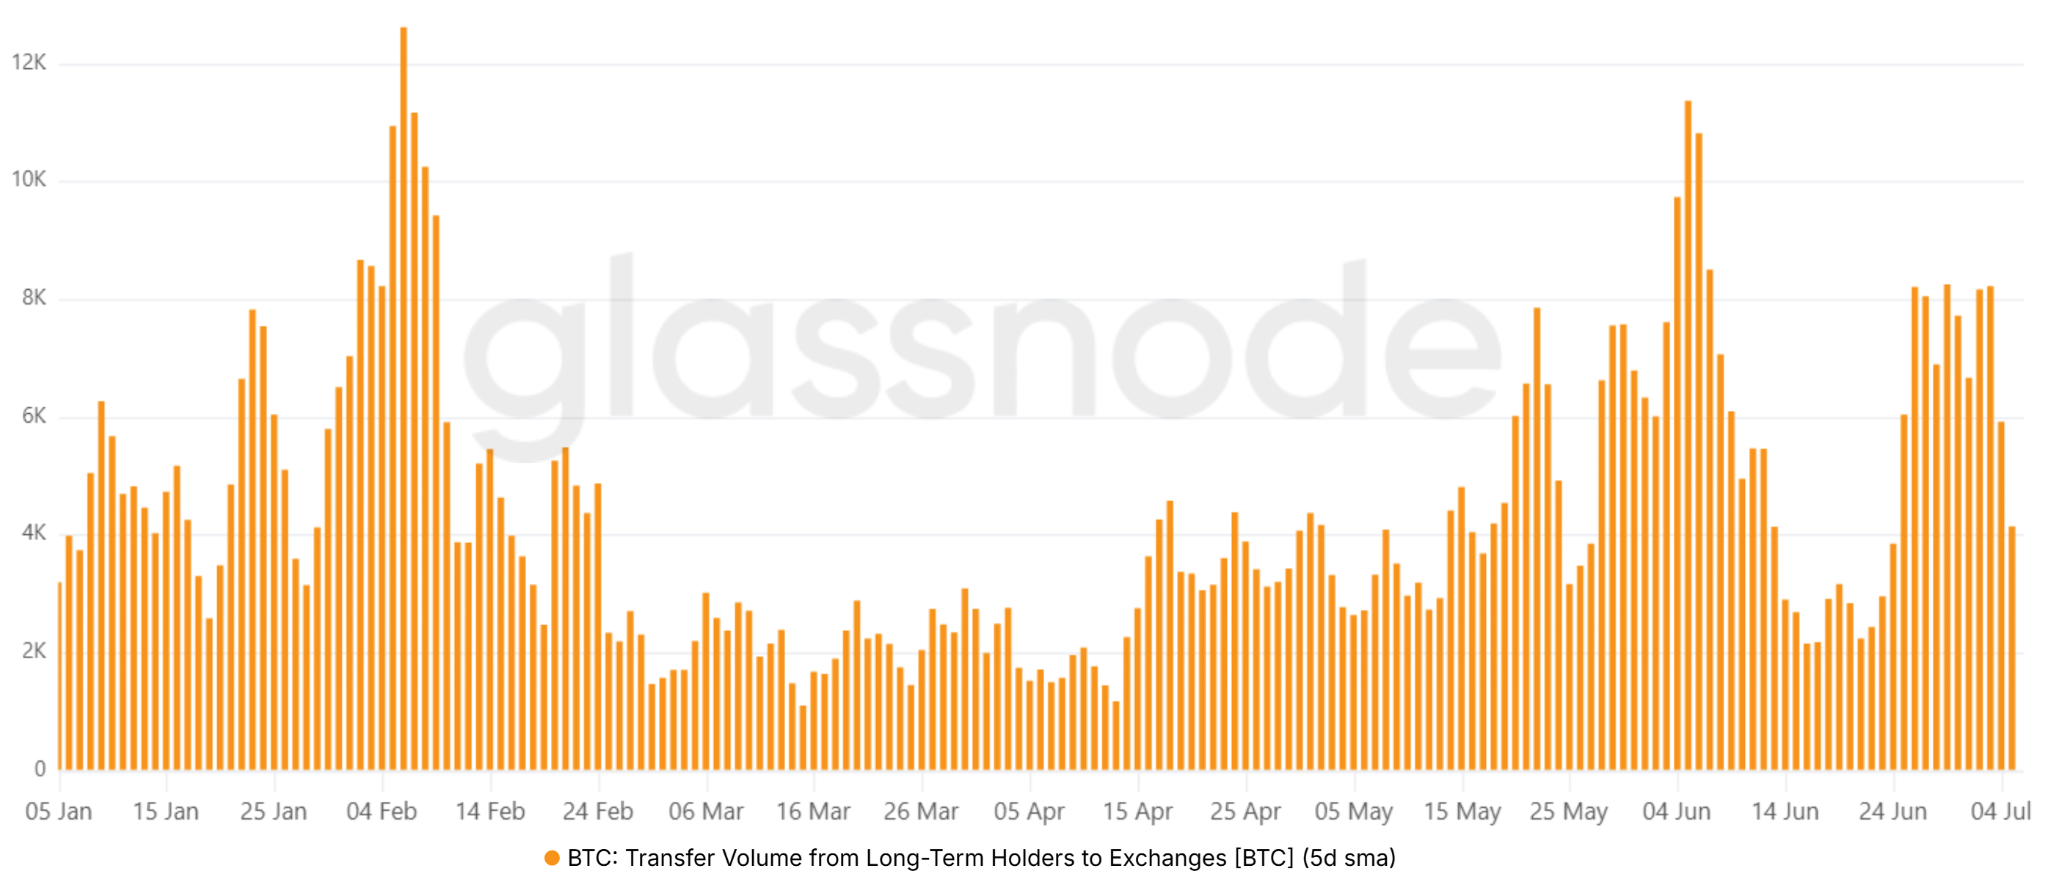
Bitcoin transfers from long-term holders to exchanges, BTC. Source: Glassnode
Transfers from long-term holders to exchanges are down to 4,130 BTC per day on average, from 8,040 BTC one week prior. Nonetheless, unless the spot Bitcoin ETFs exhibit a sequence of relevant net inflows, derivatives traders will likely remain skeptical of sustained bullish momentum, reducing the odds of a sustained rally above $65,000.
Presently, Strategy’s huge unrealized losses and skepticism in Bitcoin derivatives point to further pressure from bears.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like

Wall Street giants collectively raise rate hike forecasts, US Treasury futures continue to fall, gold drops over 1% to break 4000
After the US October CPI exceeded expectations, Goldman Sachs and Nomura added a forecast for an interest rate hike in March next year, while Deutsche Bank included a forecast for a rate hike in January next year. Currently, the market has fully priced in a 25 basis point rate hike in December, with a 13% probability for a 50 basis point hike. On Wednesday, the US Treasury spot market was closed, but Treasury futures continued to fall, with corresponding yields rising by about 2 to 4 basis points, and spot gold came under pressure, dropping by 1.1%.

No Need to Worry About the Cooling Down of AI Data Center Construction? The US Import Boom Is Unlikely to Subside in the Short Term, Real Impact May Come in 2029
It takes an average of 4.8 years from finalizing investment to starting construction of a data center project, and an additional 2.6 years from construction start to becoming operational. Servers usually cannot be installed until after the building structure and racks are completed. For trade partners such as Taiwan (China), South Korea, and Mexico who rely on US data center supply chain demand, the inertia in construction timelines provides at least a one- to two-year buffer for future exports.

Federal Reserve Major Debate: When Should the Tenure of “Number Three” Williams End?
The main point of contention is whether Williams should step down in June 2028, upon completing a full 10-year term, or in June 2027, when he reaches the mandatory retirement age of 65. Analysts point out that the Federal Reserve Board holds ultimate discretion; if he leaves early, Fed Chair Waller would be able to assert greater control over the appointment to this critical position. However, forcing Williams to shorten his term could easily be interpreted as political manipulation. Williams himself is expected to serve until June 2028.

Crypto prices
More


