
Heading to 165? Can the new stealth intervention strategy of the yen resist the depreciation trend?

On July 2, the Japanese yen experienced a dramatic reversal. During the session, the yen's exchange rate swiftly fell from a high of 162.54 to 160.62, with a maximum decline of 1.18%, and ultimately closed down 0.9%. Subsequent trading data showed that trading volume on that day was significantly lower than during the official Japanese intervention at the end of April, suggesting that it was more likely concentrated speculative covering rather than large-scale official buying.
There were two main triggers for this event: first, the Ministry of Finance of Japan may abandon its usual practice of sending repeated verbal warnings to the market before intervention, shifting instead to an ambush-style covert intervention strategy. This approach would allow authorities to act suddenly when speculative short positions have accumulated to a certain extent, significantly raising the costs of shorting for speculators and causing a concentrated closure of short positions. Second, the U.S. nonfarm payrolls released on July 2 showed an increase of only 57,000 in June, well below the market expectation of 115,000, which weakened interest rate hike expectations and depreciated the dollar, amplifying the yen's rebound.
However, this rebound did not last. As of today (July 6), the yen has returned to around 162.0. Market movements suggest that the anticipation of covert intervention may create short-term volatility and punish excessive speculation, but it is difficult to eliminate the macro-structural forces driving the yen's weakness.
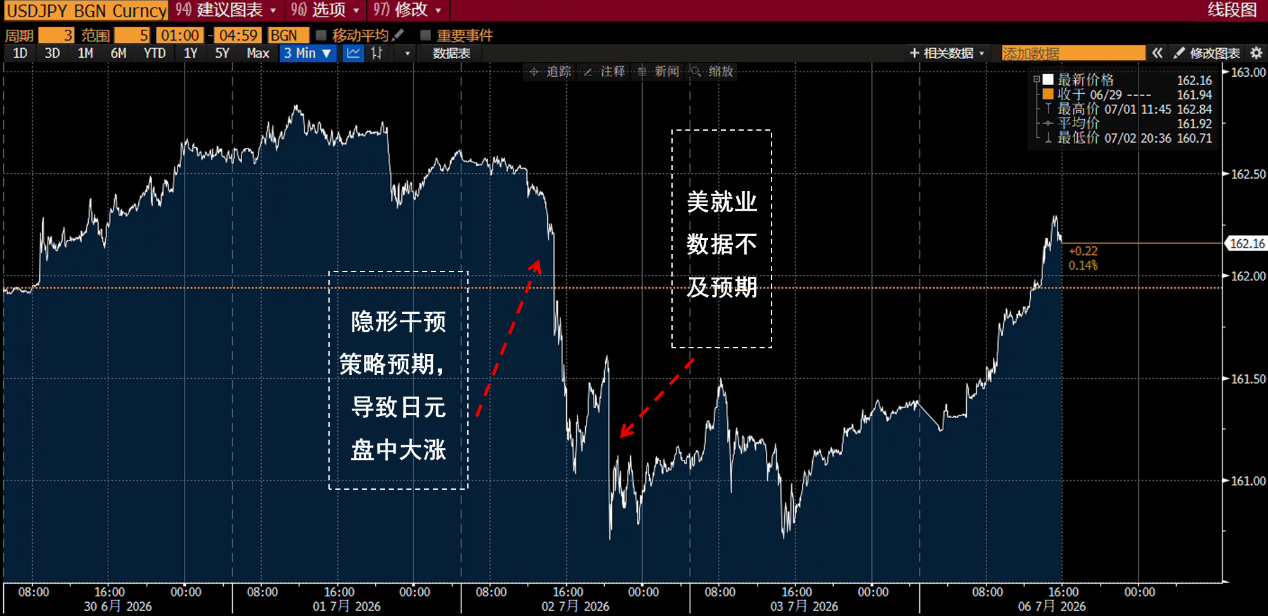
Covert intervention can create volatility, but is difficult to alter the trend
In the past, Japanese authorities would typically send continuous warning signals ahead of any official intervention, guiding the market to reduce short positions in advance and thus lowering the actual cost of intervention. However, as the market gradually adapted to this policy model, traders often prepared in advance and rebuilt short positions quickly after the impact of the intervention faded. As a result, official intervention increasingly became just a short-term trading opportunity rather than an effective tool to reverse the trend, and its actual deterrent effect on speculative capital has continued to wane.
This time, Japanese authorities have shifted towards covert intervention, attempting to deliberately obscure policy intentions and create uncertainty to compress arbitrage opportunities and curb the expansion of speculative short positions. In the short term, this adjustment can indeed increase exchange rate volatility and raise the risk of shorting the yen. The response from the options market is quite clear: the negative skew in the yen's one-week risk reversal indicator has significantly deepened, and butterfly spreads have widened to their highest levels since April 2024, indicating that traders are paying higher premiums for short-term volatility.
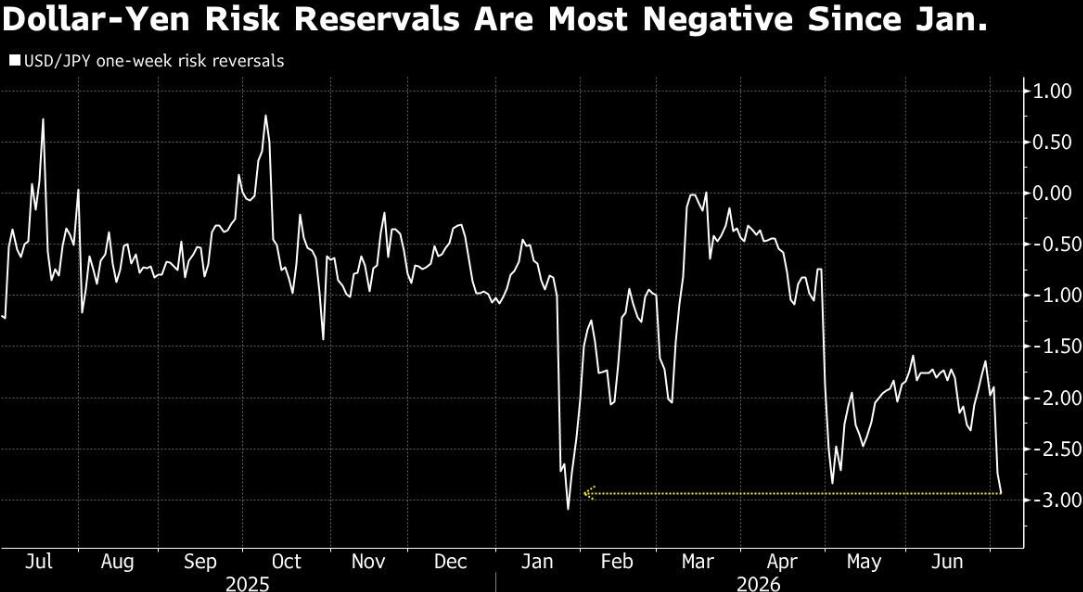
However, the main impact of this policy lies in changing market participants' risk perceptions, focusing on suppressing excessive accumulation of speculative positions through risk premiums, rather than altering the fundamental pricing logic of the yen.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like

Wall Street giants collectively raise rate hike forecasts, US Treasury futures continue to fall, gold drops over 1% to break 4000
After the US October CPI exceeded expectations, Goldman Sachs and Nomura added a forecast for an interest rate hike in March next year, while Deutsche Bank included a forecast for a rate hike in January next year. Currently, the market has fully priced in a 25 basis point rate hike in December, with a 13% probability for a 50 basis point hike. On Wednesday, the US Treasury spot market was closed, but Treasury futures continued to fall, with corresponding yields rising by about 2 to 4 basis points, and spot gold came under pressure, dropping by 1.1%.

No Need to Worry About the Cooling Down of AI Data Center Construction? The US Import Boom Is Unlikely to Subside in the Short Term, Real Impact May Come in 2029
It takes an average of 4.8 years from finalizing investment to starting construction of a data center project, and an additional 2.6 years from construction start to becoming operational. Servers usually cannot be installed until after the building structure and racks are completed. For trade partners such as Taiwan (China), South Korea, and Mexico who rely on US data center supply chain demand, the inertia in construction timelines provides at least a one- to two-year buffer for future exports.

Federal Reserve Major Debate: When Should the Tenure of “Number Three” Williams End?
The main point of contention is whether Williams should step down in June 2028, upon completing a full 10-year term, or in June 2027, when he reaches the mandatory retirement age of 65. Analysts point out that the Federal Reserve Board holds ultimate discretion; if he leaves early, Fed Chair Waller would be able to assert greater control over the appointment to this critical position. However, forcing Williams to shorten his term could easily be interpreted as political manipulation. Williams himself is expected to serve until June 2028.

Crypto prices
More


