
Micron Technology (MU) FY2026 Q3 Earnings Preview: AI-Driven Record Growth with Attractive Low Valuation
 2026/06/22 03:17
1. Investment Highlights at a Glance
Micron Technology is expected to report FY2026 Q3 earnings soon, with market consensus projecting revenue of approximately $34.38 billion (+270% YoY) and Non-GAAP EPS of about $19.72 (sharp increase).
The key focus is the continued ramp of high-bandwidth memory (HBM) and premium products. Q2 already set records with revenue of $23.86 billion (+196% YoY) and EPS of $12.20, while Q3 guidance points to revenue of $33.5 billion (±$0.75 billion) and gross margin around 81%, further validating structural AI demand tailwinds.
Wall Street remains optimistic as Micron’s HBM capacity is sold out through the end of 2026, supporting sustained pricing power and high profitability. This creates notable trading opportunities for active traders, though cyclical characteristics warrant caution.
2. Three Major Focus Areas
Focus 1: HBM and Premium Product Ramp, Sustained AI Demand Strength
AI data center buildouts continue to accelerate, with HBM as the primary driver. Micron’s HBM capacity is fully booked through multi-year agreements, and HBM4 mass production is progressing smoothly, boosting overall business lines.
Core Logic: HBM is essential for AI GPUs; tight supply enhances pricing power. Q2 delivered record revenue and profits across segments, with Q3 expected to maintain strong momentum. Data center SSDs and other products also benefit from surging demand.
Key Metrics: HBM shipment volume/revenue contribution, DRAM & NAND ASP (average selling prices). Stronger-than-expected delivery and margins could reinforce confidence in structural growth and drive share price upside.
Focus 2: Gross Margin and Profitability Reaching New Highs
Q2 Non-GAAP gross margin reached approximately 75%, with Q3 guidance rising further to 81%. EPS guidance stands at $19.15 (±$0.40), far exceeding historical levels.
Core Logic: AI-driven premium product mix, tight supply, and cost discipline are breaking traditional memory cycle patterns of rapid post-peak decline, significantly enhancing profitability.
Key Metrics: Gross margin, operating margin, and EPS growth (YoY/QoQ). Planned CapEx expansion (FY2026 > $25 billion) supports long-term capacity while maintaining near-term tightness.
Focus 3: Valuation Advantage vs. Peers
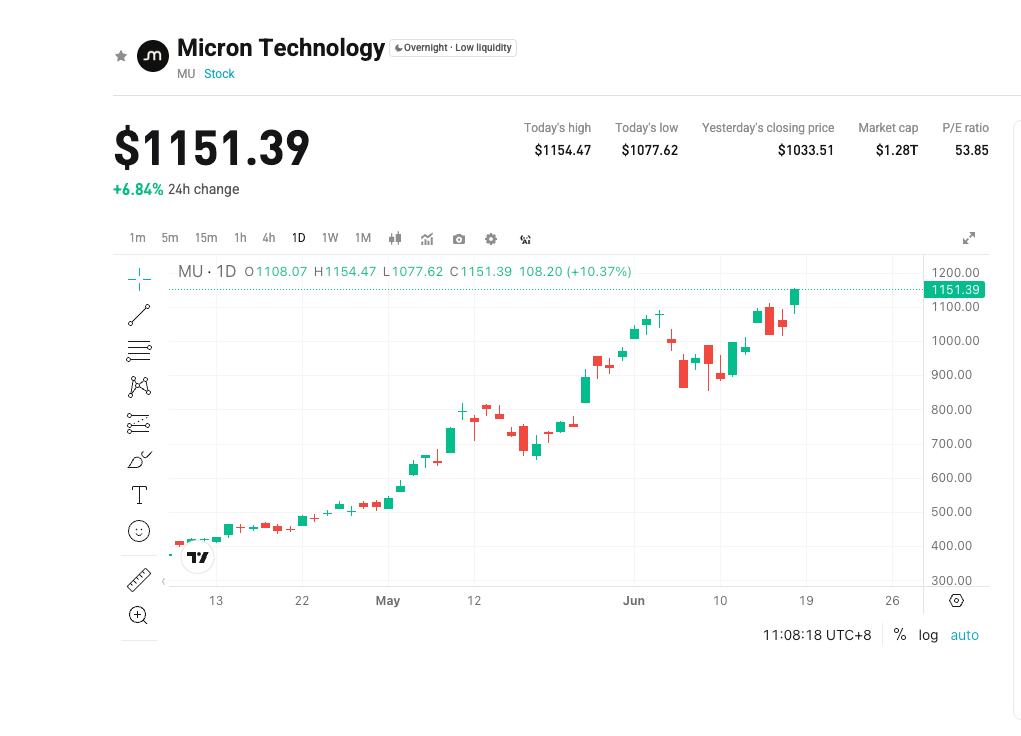
Despite explosive growth, Micron’s valuation remains relatively attractive compared to history and peers. Shares have risen substantially YTD, but AI momentum leaves room for further re-rating.
Core Logic: Cyclical concerns have capped multiple expansion, yet long-term AI cloud demand provides structural support. This creates favorable comparison to higher-valued growth names like NVIDIA.
Key Metrics: Forward P/E, HBM market share, and cloud CapEx trends. Another earnings beat could accelerate valuation catch-up.
3. Risks and Opportunities Coexist
Upside Catalysts:
- Q3 results and HBM4 updates exceeding consensus, confirming pricing power and demand resilience.
- Upward revision to full-year guidance or strong CapEx execution signaling confidence.
- Broader end-market improvement (servers + consumer) driving diversified growth.
Downside Risks:
- Supply easing leading to pricing pressure and renewed cyclical concerns.
- Macro or geopolitical factors slowing downstream CapEx and inventory digestion.
- Intensified competition or execution delays impacting share and margin sustainability.
4. Trading Strategy Suggestions
- Bull Case: Q3 report validates high margins and sustained demand, strengthening the HBM thesis and accelerating valuation re-rating—favorable for long positioning, especially in leveraged products.
- Bear Case: Conservative guidance or early peak-margin signals could trigger profit-taking and near-term pullback.
- Key Data to Watch: Revenue, gross margin, HBM guidance, EPS, CapEx updates, and full-year outlook.
- Actionable Ideas: Monitor volatility around the report; consider staged entries on positive catalysts. Maintain strict risk management and adjust positions based on real-time data and personal risk tolerance.
Disclaimer: This content is for reference only and does not constitute investment advice. Investing involves risks—trade cautiously. Please consult the latest official disclosures, professional advice, and your own circumstances before making decisions.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
The AI boom may follow the path of the 19th-century railway bubble, and builders may not be the ultimate winners
Goldman Sachs analyst Bobby Molavi compared the current situation to the 19th-century British railway mania: 500 companies spent more than the nation's annual income building 8,000 miles of railway, with most early investors losing out, while the real beneficiaries were the later "passengers." He pointed out that the current AI craze is driven by both debt and momentum, and that the S&P 500’s forward P/E ratio of 18x is only "a bit cheaper." Whether the builders can retain value is uncertain, and history does not offer an optimistic answer.

If Anthropic's IPO goes smoothly and the stock price rises next week, then everything remains the same for AI. Otherwise, some companies will go bankrupt.
The shrinking valuations of two major giants have triggered a chain reaction—investors are adopting more conservative revenue multiples for AI startups and are directly halting high-valuation financing for companies with zero revenue. Multiple venture capital firms have advised their portfolio companies to lower valuation expectations and to quickly build up cash reserves. Market participants warn that the outcome of Anthropic’s IPO will be a barometer for the industry: if successful, the boom will continue; if it fails, some companies may face elimination.
After the Brazilian election, political discount deepens; Morgan Stanley remains bullish on Petrobras (PBR.US), focusing on fuel pricing and dividends
Morgan Stanley still maintains its most optimistic "Overweight" rating, but has lowered its year-end 2027 target price from $31 to $25.

Corning (GLW.US) receives initial "Buy" rating from Jefferies! AI factories driving a fiber optic rush, with a potential global supply gap of up to 30%
For Corning, the recent profit growth mainly comes from the expansion of AI clusters. As the number of optical links crossing cabinets and campuses increases, customers need to deploy more optical fibers within limited conduit and cabinet space, thus driving demand for high-density optical cables and connection systems.

Crypto prices
More


