
Intel (INTC) 2026 Q1 Earnings Highlights: AI-Driven Data Center +22% Growth, Q2 Guidance Significantly Beats Expectations, Post-Earnings Stock Surges Over 20%
 Bitget2026/04/24 02:24
Key Takeaways
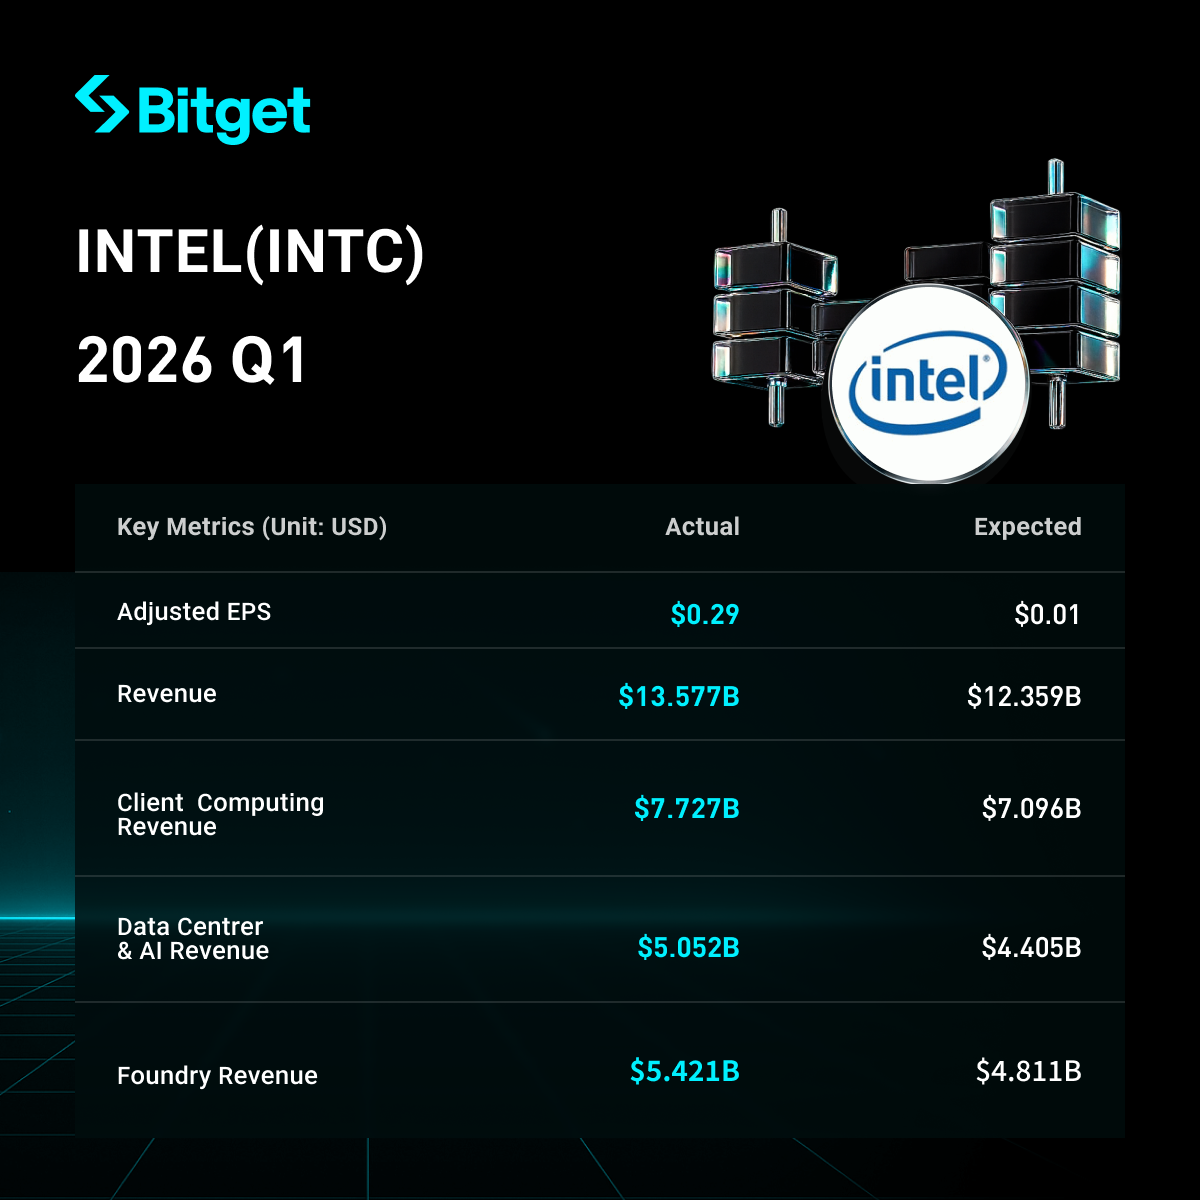
Intel (INTC) delivered a strong beat-and-raise in its 2026 Q1 earnings and Q2 guidance, fueled by surging AI server demand. Q1 revenue grew 7% year-over-year to $13.6 billion (vs. $12.4 billion expected). Q2 revenue guidance midpoint of $14.3 billion far exceeded the $13.0 billion consensus. Data Center and AI (DCAI) revenue reached $5.1 billion, up 22% YoY. CEO highlighted massive customer demand and supply constraints, with aggressive capacity expansion underway. Shares surged more than 20% in after-hours trading, bringing YTD gains to 81% (pre-earnings close: $66.78).
Bitget has now listed INTCUSDT 50X capture returns!
Detailed Breakdown
- Overall Revenue and Profit Performance
- Q1 Revenue: $13.6 billion, +7% YoY, well above consensus of $12.4 billion.
- Adjusted EPS: $0.29 (significantly beating expectations around $0.02).
- Operating cash flow: $1.1 billion.
- Adjusted gross margin: 41% (still below historical peak above 60%).
- Other: Repurchased 49% minority stake in Ireland Fab 34 wafer fab to strengthen balance sheet.
- Data Center & AI (DCAI) Performance
- Revenue: $5.1 billion, +22% YoY, beating Street estimates (~$4.4 billion).
- Key Drivers: AI infrastructure buildout wave, strong demand for Xeon server processors; enterprises and cloud providers accelerating AI commercialization, re-evaluating CPU strategic value.
- CEO Lip-Bu Tan stated: “Customer demand is enormous, our supply remains insufficient — we are fully focused on expanding factory capacity.”
- Other Business Segments Performance
- Client Computing Group (CCG, including PC): $7.7 billion, +1% YoY.
- Intel Foundry Services: $5.4 billion, +16% YoY.
- Intel Products overall: $12.8 billion, +9% YoY.
- All three core segments exceeded Wall Street forecasts.
- PC industry facing memory chip shortages (server demand squeezing capacity); Intel noted it has managed the situation effectively.
- Capital Expenditure Plans
- Full-year capex expected to be roughly flat versus last year, reversing prior cuts.
- CFO Dave Zinsner: Additional spending on new production equipment beyond previous budgets.
- Strategy: Leverage existing fab space and fill capacity by adding equipment.
- Q2 2026 Guidance
- Revenue: $13.8–$14.8 billion, midpoint $14.3 billion — materially above consensus $13.0 billion.
- Overall guidance significantly beat expectations, reflecting continued strong AI-driven server chip demand.
- Market Context & Investor Concerns
- Positive Signals: Strengthened partnerships including multi-year Xeon deal with Google, Xeon 6 selected for NVIDIA DGX Rubin systems; participation in Terafab project (with SpaceX, xAI, Tesla); Tesla CEO Elon Musk confirmed using Intel tech for internal chip fab.
- Core Challenges: No mainstream AI accelerator product yet to directly compete with NVIDIA; ongoing CPU market share pressure; gross margin still below historical highs.
- Investor Reaction: Shares jumped >20% after hours, also lifting AMD (+7%) and Arm (+6%). Market betting on CPU demand recovery and acceleration.
Right now, we're also running the limited-time "Lifetime Zero: The Weekly Jackpot IV" event for US stock contracts:
- Lifetime 0 trading fees on US stock contracts + weekly jackpot draws that never stop!
- Participate and stand a chance to win free TSLA, NVDA, and other hot US stocks!
Disclaimer This content is for reference only and does not constitute any investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Cerebras (CBRS.US) Cloud Business Soars, Masking Hardware Decline; OpenAI Supports Half of Cloud Revenue
Cerebras achieved record Q3 revenue, but hardware income dropped by nearly 30%, while cloud business accounted for two-thirds of total revenue. OpenAI contributed $72.4 million. The company raised its full-year guidance and expects Q4 to be close to breakeven.
Microsoft (MSFT.US) offers voluntary buyout packages to about 60,000 employees: Structural divergence in U.S. employment under AI transformation
In 2026, the U.S. labor market is characterized by both low layoffs and weak hiring. Companies like Microsoft and American Express are leveraging AI to optimize their workforce, while data centers are driving growth in the construction sector. However, entry-level white-collar jobs face increasing pressure, with real wages experiencing negative growth and structural transformation risks becoming more prominent.

"Inflation is really too high"! Federal Reserve "third-in-command": The Fed must continue to take action and promptly bring the price level back to 2%
John Williams, President of the New York Federal Reserve and the “number three” official at the Federal Reserve with a permanent voting right, stated that U.S. inflation remains high and policymakers must take further action to curb price pressures.

Jensen Huang steps down, and the "biggest patron" of new AI players is gone too
Anthropic's tens-of-billions IPO investment, Figure AI's additional $1 billion, and Nscale's over $5 billion credit guarantee are all in negotiations but their outcomes remain uncertain. Meanwhile, its $500 billion AI financing platform has stalled, and some clients are considering switching to AMD or Google. Successor Kress has a conservative style and has repeatedly vetoed deals aggressively promoted by Jensen Huang, signaling the possible end of Nvidia's era of bold investments.
Crypto prices
More


