
Macroeconomic Repricing Amid US-Iran Conflict: Will the 1970s Stagflation Crisis Repeat?

With the escalation of the US-Israel-Iran conflict, shipping in the Strait of Hormuz has been significantly hampered, putting about 20% of global crude oil and LNG supply at risk of disruption. Brent oil prices have surged quickly above $80, while diesel, shipping rates, and war risk insurance costs have all spiked in tandem. The crack spread in energy prices has widened, reflecting an increasingly tight supply of refined oil products. Currently, the market is repeatedly pricing between scenarios of short-term military friction and long-term strategic blockade, making inflation expectations and the path of the Federal Reserve’s policy the core variables.
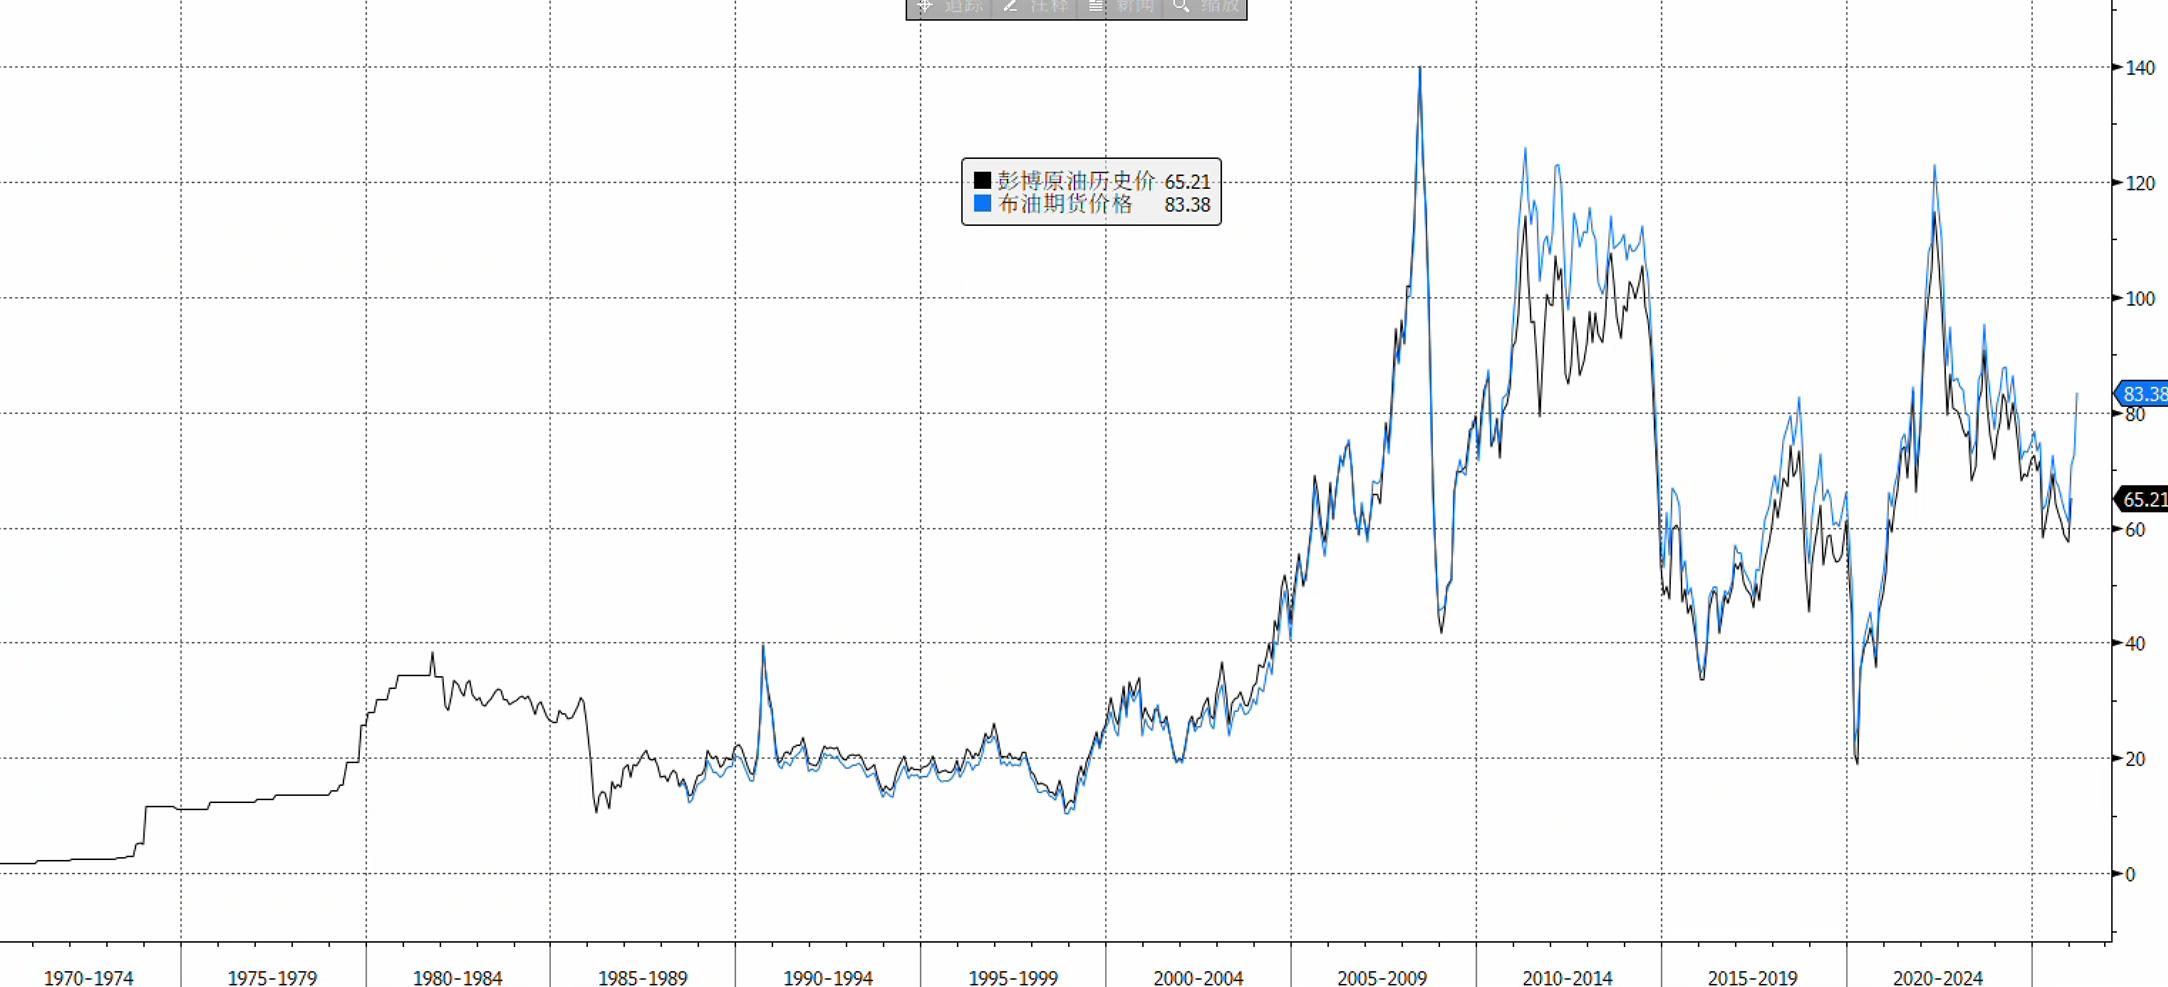
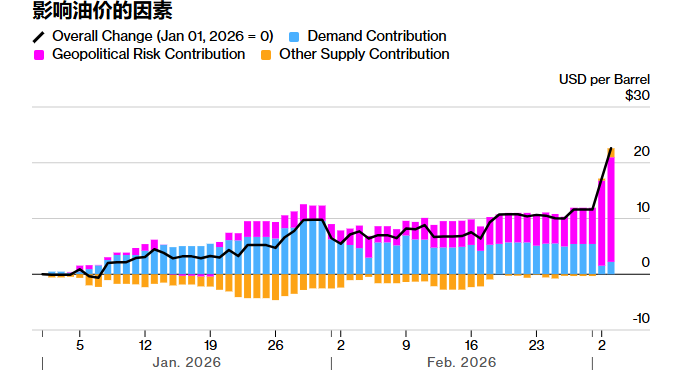
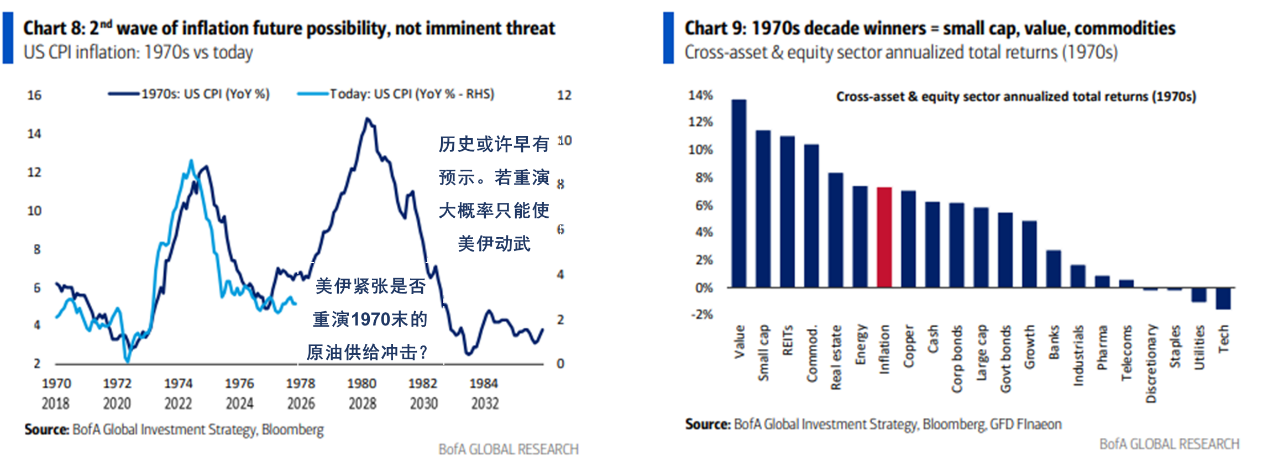
Looking back at history, the Fourth Middle East War and oil embargo in 1973, as well as the Iranian Revolution and the Iran-Iraq War in 1979, triggered global energy supply shocks twice: Oil prices doubled within months, the US CPI surged into double digits, the US stock market saw deep pullbacks, and real bond yields experienced dramatic swings. Afterwards, under the aggressive tightening policy led by then Federal Reserve Chair Paul Volcker, the US suppressed inflation at the cost of high unemployment and deep recession, barely managing to survive the stagflation crisis. The key question now for the market is whether this round of conflict meets the macroeconomic conditions to repeat the stagflation chain reaction of the 1970s.
In our coverage on January 29, "Crude Oil Volatility: US-Iran Geopolitical Risks Return to Pricing Core," we noted that "currently, low oil prices and high inventories have significantly decreased concerns about energy inflation within the US, thus lowering the costs of limited, surgical strikes. The current level of oil prices does not impose obvious pressure on US inflation or the cost of living for Americans, which decreases US concerns about the consequences of high oil prices in Middle Eastern affairs, making it more willing to take aggressive steps on sanctions and military deterrence."
However, this time, the US carried out surgical strikes on Iranian leaders, but unlike the quick end to the crisis following the surprise attack on Venezuelan President Maduro, the conflict has not ended swiftly, and Iran has declared itself prepared for a prolonged war. Meanwhile, the reaction of US stocks to this round of conflict has remained mild, implying that the market has not yet fully priced in the risks of a prolonged blockade of the Strait of Hormuz. This mild reaction is not a coincidence, but conforms to the usual pattern of market response: Only when a geopolitical event spills over to affect other macro variables such as economic growth or inflation does the market respond in a persistent and broad manner; lacking such economic spillovers, the impact typically remains confined to directly affected assets and rarely spreads further (see the January 8 article "What Conditions Are Needed for Geopolitical Tensions to Cause Significant Market Reactions?").
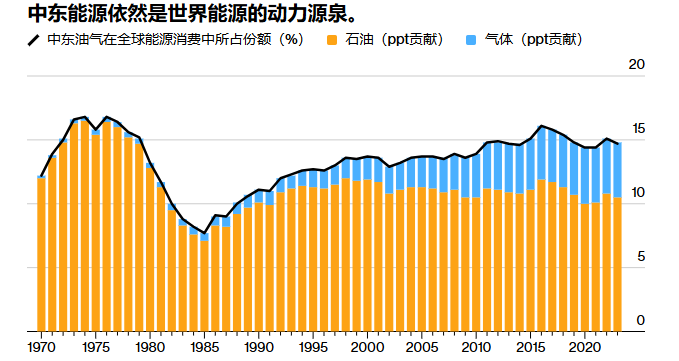
However, some Asian economies such as Japan and South Korea are more vulnerable to the closure of the Strait of Hormuz. Combined with strong prior momentum trends, investors have taken profits as risk aversion has risen, resulting in large capital outflows and triggering stampede-style sell-offs. The impact on European markets has also been more severe than in the US, as they are more affected by surging crude oil and natural gas prices, resulting in sharper market reactions than in the US market.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Nvidia falls to its lowest valuation in 14 years! "Super bull" Tom Lee calls for bottom fishing, retail investors are buying more as it drops, but Wall Street is divided
After the market opened on Thursday, retail investors went against the trend and bought up Nvidia, with net purchases reaching $111 million in just half an hour, setting a record for the same period. Investors such as Tom Lee have publicly supported the company, with institutions optimistic about strong order backlogs extending to 2028, robust revenue growth, and opportunities created by declining valuations. Meanwhile, institutions like Bernstein and Goldman Sachs have become more cautious about Nvidia's outlook, with concerns focusing on management succession and technological leadership following Jensen Huang's departure.

Jane Street boosts Fidelity Bitcoin ETF stake 8x in Q3, trims BlackRock IBIT

From SpaceX to Anthropic, the market has new strategies for dealing with tech giants' IPOs
The market's response strategies to major listings are currently centered around "index inclusion expectations": the new regulations allow mega IPOs to be included in the six major indices within 15 days, triggering concentrated buying by passive funds. Investors are positioning themselves in advance and using options to hedge and amplify buying power. However, Anthropic has a free float of only about 6%; shares available for sale by employees on the first day and privately placed shares with no lock-up period may create supply pressure. On the other hand, index arbitrageurs are facing a rare opportunity.

Nvidia Q3 Earnings Preview: Revenue Expectations and Key Metrics to Watch
Crypto prices
More


