
Alarm.com (ALRM) Q4 Earnings: What To Expect

Smart property technology provider Alarm.com (NASDAQ:ALRM) will be reporting earnings this Thursday after market hours. Here’s what investors should know.
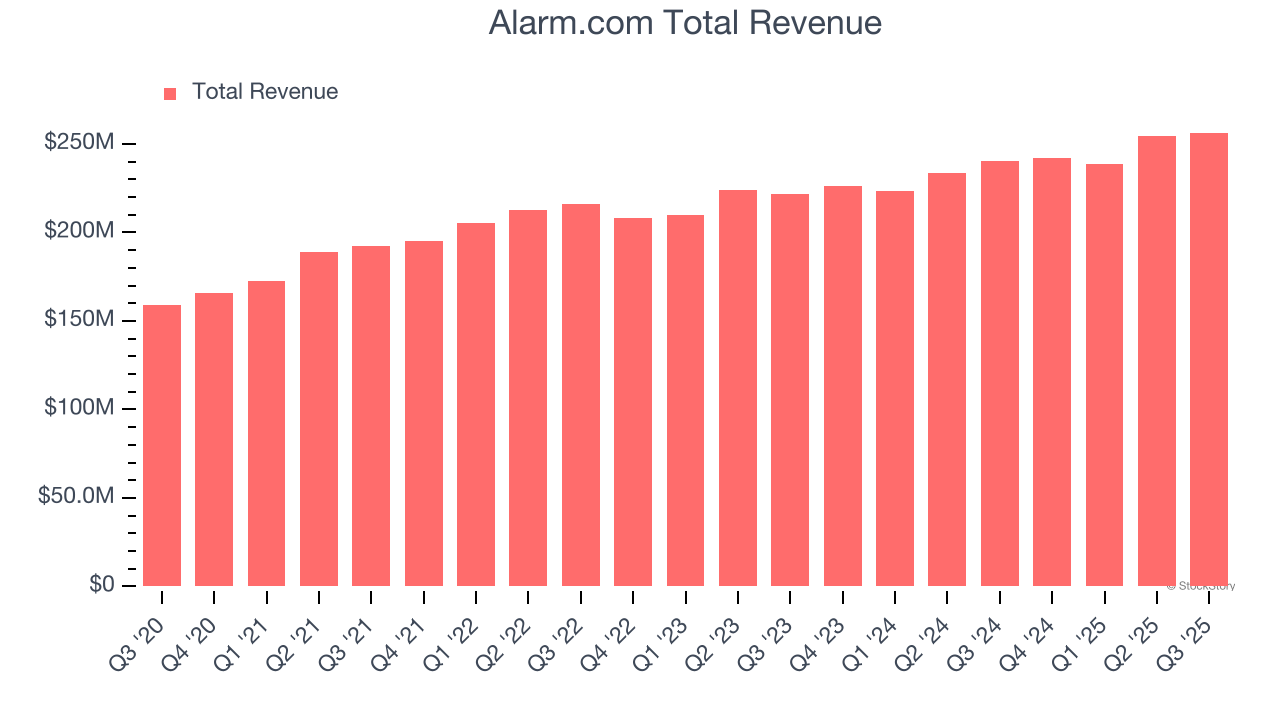
Alarm.com beat analysts’ revenue expectations by 2.2% last quarter, reporting revenues of $256.4 million, up 6.6% year on year. It was an exceptional quarter for the company, with an impressive beat of analysts’ EBITDA estimates and full-year EPS guidance exceeding analysts’ expectations.
This quarter, analysts are expecting Alarm.com’s revenue to grow 3.6% year on year to $250.8 million, slowing from the 7.1% increase it recorded in the same quarter last year. Adjusted earnings are expected to come in at $0.64 per share.
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business to stay the course heading into earnings. Alarm.com has a history of exceeding Wall Street’s expectations, beating revenue estimates every single time over the past two years by 2.4% on average.
Looking at Alarm.com’s peers in the software-as-a-service segment, some have already reported their Q4 results, giving us a hint as to what we can expect. Manhattan Associates delivered year-on-year revenue growth of 5.7%, beating analysts’ expectations by 2.2%, and Fastly reported revenues up 22.8%, topping estimates by 6.9%. Manhattan Associates traded down 5.1% following the results while Fastly was up 72.3%.
The outlook for 2025 remains clouded by potential trade policy changes and corporate tax discussions, which could impact business confidence and growth. While some of the software-as-a-service stocks have shown solid performance in this choppy environment, the group has generally underperformed, with share prices down 13.6% on average over the last month. Alarm.com is down 7.8% during the same time and is heading into earnings with an average analyst price target of $66.33 (compared to the current share price of $45.41).
Here at StockStory, we certainly understand the potential of thematic investing. Diverse winners from Microsoft (MSFT) to Alphabet (GOOG), Coca-Cola (KO) to Monster Beverage (MNST) could all have been identified as promising growth stories with a megatrend driving the growth. So, in that spirit, we’ve identified a relatively under-the-radar profitable growth stock benefiting from the rise of AI, available to you FREE via this link.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Jensen Huang's sudden resignation shrouded in suspicion: Did the White House secretly intervene? Is a return possible in the future?
Only a few days separated Jensen Huang’s strong support from the board last Sunday and his late-night resignation on Wednesday. Multiple reports of the Wednesday night Nvidia board meeting were co-authored by Washington-based journalists—who do not typically cover Nvidia—fueling rumors of "White House pressure and information leaks." Huang’s unique value lies in leveraging his personal reputation to secure the supply chain and drive the implementation of technological roadmaps, making him difficult to replace. Some analysts note that, drawing on examples such as Steve Jobs’ return to Apple, it is possible that Huang may come back in the future.

Gold recovers from YTD low, retakes $3,900; Fed hike bets and bullish USD to cap gains
Cerebras (CBRS.US) Cloud Business Soars, Masking Hardware Decline; OpenAI Supports Half of Cloud Revenue
Cerebras achieved record Q3 revenue, but hardware income dropped by nearly 30%, while cloud business accounted for two-thirds of total revenue. OpenAI contributed $72.4 million. The company raised its full-year guidance and expects Q4 to be close to breakeven.
Crypto prices
More


