
Cadence Design Systems's (NASDAQ:CDNS) Q4 CY2025 Sales Top Estimates

Electronic design automation company Cadence Design Systems (NASDAQ:CDNS) announced
Is now the time to buy Cadence Design Systems?
Cadence Design Systems (CDNS) Q4 CY2025 Highlights:
- Revenue: $1.44 billion vs analyst estimates of $1.43 billion (6.2% year-on-year growth, 1% beat)
- EPS (GAAP): $1.42 vs analyst estimates of $1.21 (17.2% beat)
- Free Cash Flow Margin: 2.9%, down from 20.7% in the previous quarter
- Market Capitalization: $81.51 billion
Company Overview
Powering the chips behind everything from smartphones to AI accelerators for over 35 years, Cadence Design Systems (NASDAQ:CDNS) provides essential computational software, hardware, and intellectual property used by engineers to design and verify advanced electronic systems and semiconductors.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Cadence Design Systems grew its sales at a 14.6% annual rate. Though this growth is acceptable on an absolute basis, we need to see more than just topline growth for the software sector, which can display significant earnings volatility. This means our bar for the sector is particularly high, reflecting the non-essential and hit-driven nature of the products and services offered. Additionally, five-year CAGR starts around Covid, when revenue was depressed then rebounded. Luckily, there are other things to like about Cadence Design Systems.
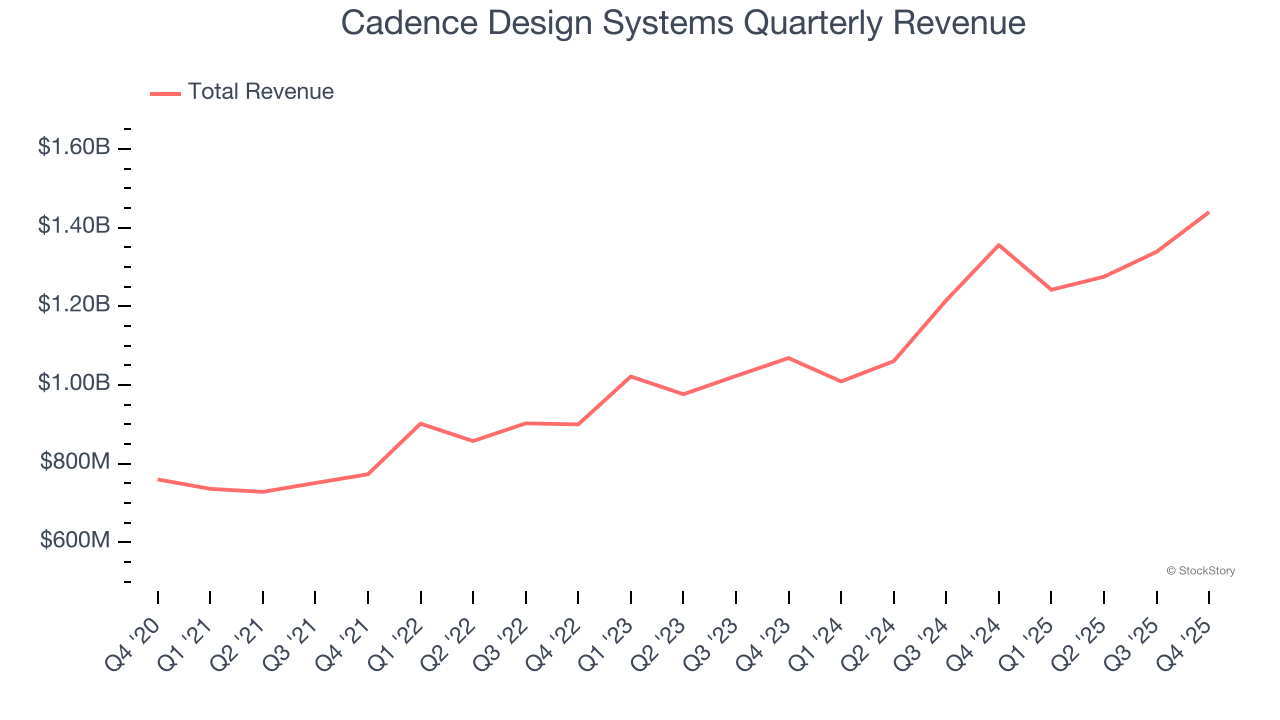
We at StockStory place the most emphasis on long-term growth, but within software, a half-decade historical view may miss recent innovations or disruptive industry trends. Cadence Design Systems’s annualized revenue growth of 13.8% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak.
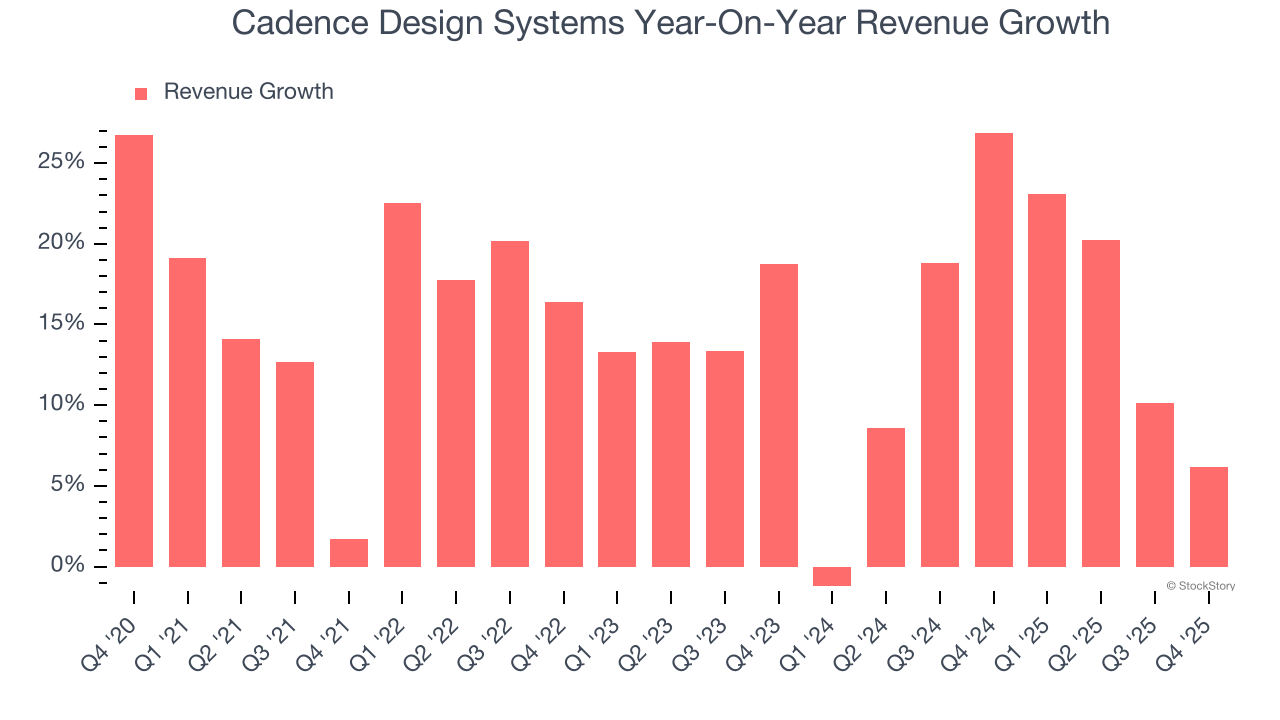
This quarter, Cadence Design Systems reported year-on-year revenue growth of 6.2%, and its $1.44 billion of revenue exceeded Wall Street’s estimates by 1%.
Looking ahead, sell-side analysts expect revenue to grow 12.1% over the next 12 months, a slight deceleration versus the last two years. This projection doesn't excite us and implies its products and services will face some demand challenges. At least the company is tracking well in other measures of financial health.
The 1999 book Gorilla Game predicted Microsoft and Apple would dominate tech before it happened. Its thesis? Identify the platform winners early. Today, enterprise software companies embedding generative AI are becoming the new gorillas.
Customer Acquisition Efficiency
The customer acquisition cost (CAC) payback period measures the months a company needs to recoup the money spent on acquiring a new customer. This metric helps assess how quickly a business can break even on its sales and marketing investments.
Cadence Design Systems is extremely efficient at acquiring new customers, and its CAC payback period checked in at 8.6 months this quarter. The company’s rapid recovery of its customer acquisition costs means it can attempt to spur growth by increasing its sales and marketing investments.
Key Takeaways from Cadence Design Systems’s Q4 Results
It was good to see Cadence Design Systems narrowly top analysts’ revenue expectations this quarter. Zooming out, we think this was a decent quarter. The stock traded up 4.5% to $295.57 immediately following the results.
So should you invest in Cadence Design Systems right now? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Jensen Huang's sudden resignation shrouded in suspicion: Did the White House secretly intervene? Is a return possible in the future?
Only a few days separated Jensen Huang’s strong support from the board last Sunday and his late-night resignation on Wednesday. Multiple reports of the Wednesday night Nvidia board meeting were co-authored by Washington-based journalists—who do not typically cover Nvidia—fueling rumors of "White House pressure and information leaks." Huang’s unique value lies in leveraging his personal reputation to secure the supply chain and drive the implementation of technological roadmaps, making him difficult to replace. Some analysts note that, drawing on examples such as Steve Jobs’ return to Apple, it is possible that Huang may come back in the future.

Gold recovers from YTD low, retakes $3,900; Fed hike bets and bullish USD to cap gains
Cerebras (CBRS.US) Cloud Business Soars, Masking Hardware Decline; OpenAI Supports Half of Cloud Revenue
Cerebras achieved record Q3 revenue, but hardware income dropped by nearly 30%, while cloud business accounted for two-thirds of total revenue. OpenAI contributed $72.4 million. The company raised its full-year guidance and expects Q4 to be close to breakeven.
Crypto prices
More


