
Pinterest (NYSE:PINS) Reports Sales Below Analyst Estimates In Q4 CY2025 Earnings, Stock Drops 15.9%

Social commerce platform Pinterest (NYSE: PINS)
Is now the time to buy Pinterest?
Pinterest (PINS) Q4 CY2025 Highlights:
- Revenue: $1.32 billion vs analyst estimates of $1.33 billion (14.3% year-on-year growth, 0.8% miss)
- Adjusted EPS: $0.67 vs analyst estimates of $0.67 (in line)
- Adjusted EBITDA: $541.5 million vs analyst estimates of $547.1 million (41% margin, 1% miss)
- Revenue Guidance for Q1 CY2026 is $961 million at the midpoint, below analyst estimates of $981.8 million
- EBITDA guidance for Q1 CY2026 is $176 million at the midpoint, below analyst estimates of $205.4 million
- Operating Margin: 22.8%, in line with the same quarter last year
- Free Cash Flow Margin: 28.8%, down from 30.3% in the previous quarter
- Monthly Active Users: 619 million, up 66 million year on year
- Market Capitalization: $12.9 billion
Company Overview
Created with the idea of virtually replacing paper catalogues, Pinterest (NYSE: PINS) is an online image and social discovery platform.
Revenue Growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Thankfully, Pinterest’s 14.6% annualized revenue growth over the last three years was solid. Its growth surpassed the average consumer internet company and shows its offerings resonate with customers, a great starting point for our analysis.
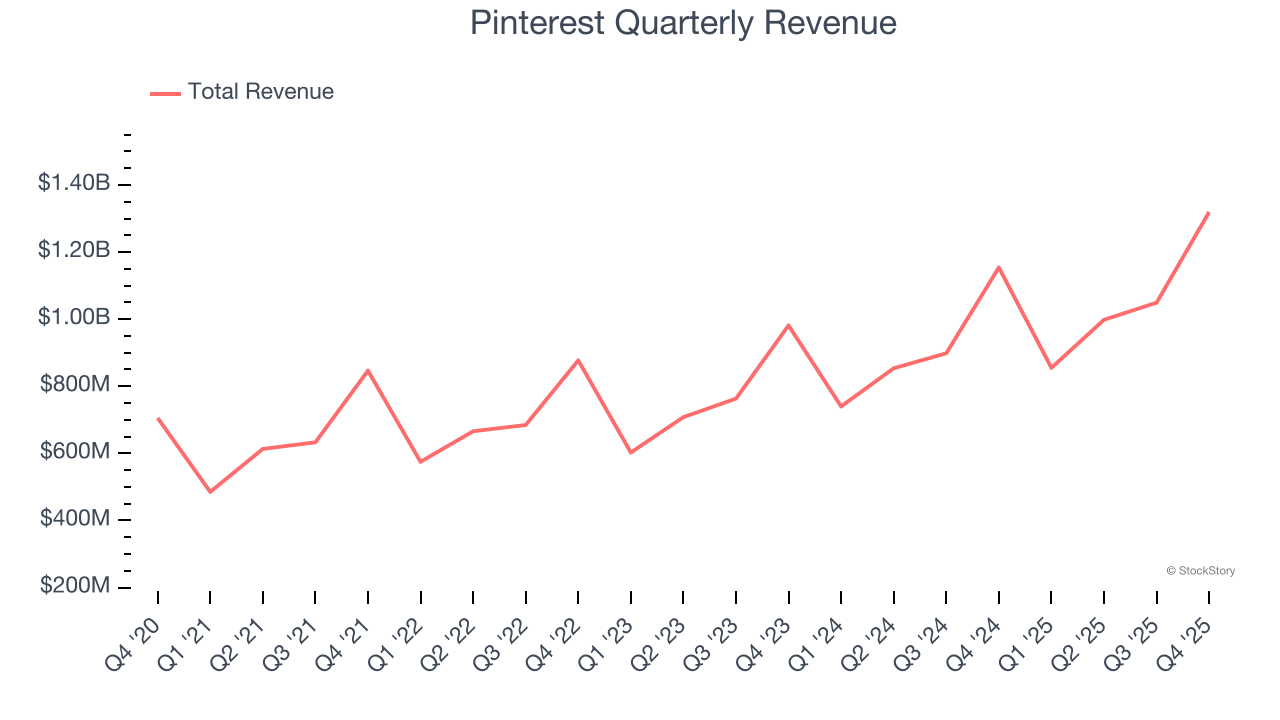
This quarter, Pinterest’s revenue grew by 14.3% year on year to $1.32 billion but fell short of Wall Street’s estimates. Company management is currently guiding for a 12.4% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 14.5% over the next 12 months, similar to its three-year rate. This projection is healthy and implies the market is forecasting success for its products and services.
The 1999 book Gorilla Game predicted Microsoft and Apple would dominate tech before it happened. Its thesis? Identify the platform winners early. Today, enterprise software companies embedding generative AI are becoming the new gorillas.
Monthly Active Users
User Growth
As a social network, Pinterest generates revenue growth by increasing its user base and charging advertisers more for the ads each user is shown.
Over the last two years, Pinterest’s monthly active users, a key performance metric for the company, increased by 11.4% annually to 619 million in the latest quarter. This growth rate is strong for a consumer internet business and indicates people love using its offerings.
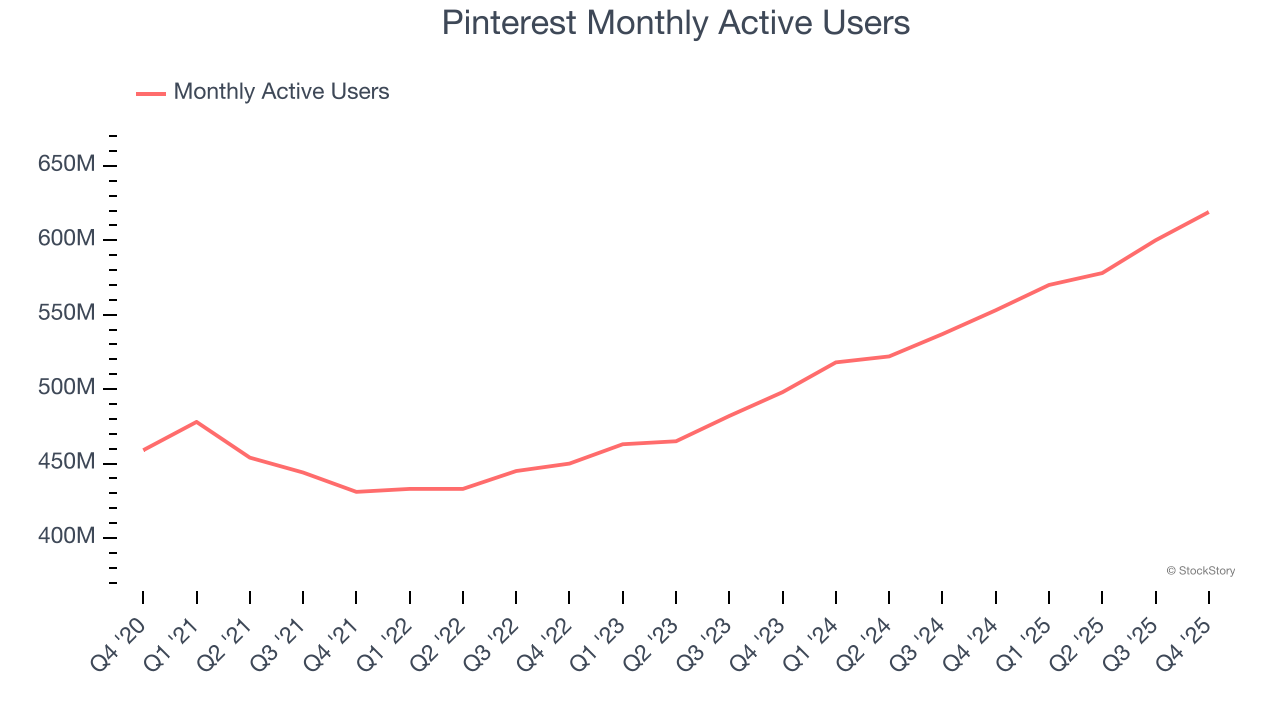
In Q4, Pinterest added 66 million monthly active users, leading to 11.9% year-on-year growth. The quarterly print isn’t too different from its two-year result, suggesting its new initiatives aren’t accelerating user growth just yet.
Revenue Per User
Average revenue per user (ARPU) is a critical metric to track because it measures how much the company earns from the ads shown to its users. ARPU can also be a proxy for how valuable advertisers find Pinterest’s audience and its ad-targeting capabilities.
Pinterest’s ARPU growth has been strong over the last two years, averaging 6.3%. Its ability to increase monetization while quickly growing its monthly active users reflects the strength of its platform, as its users continue to spend more each year.
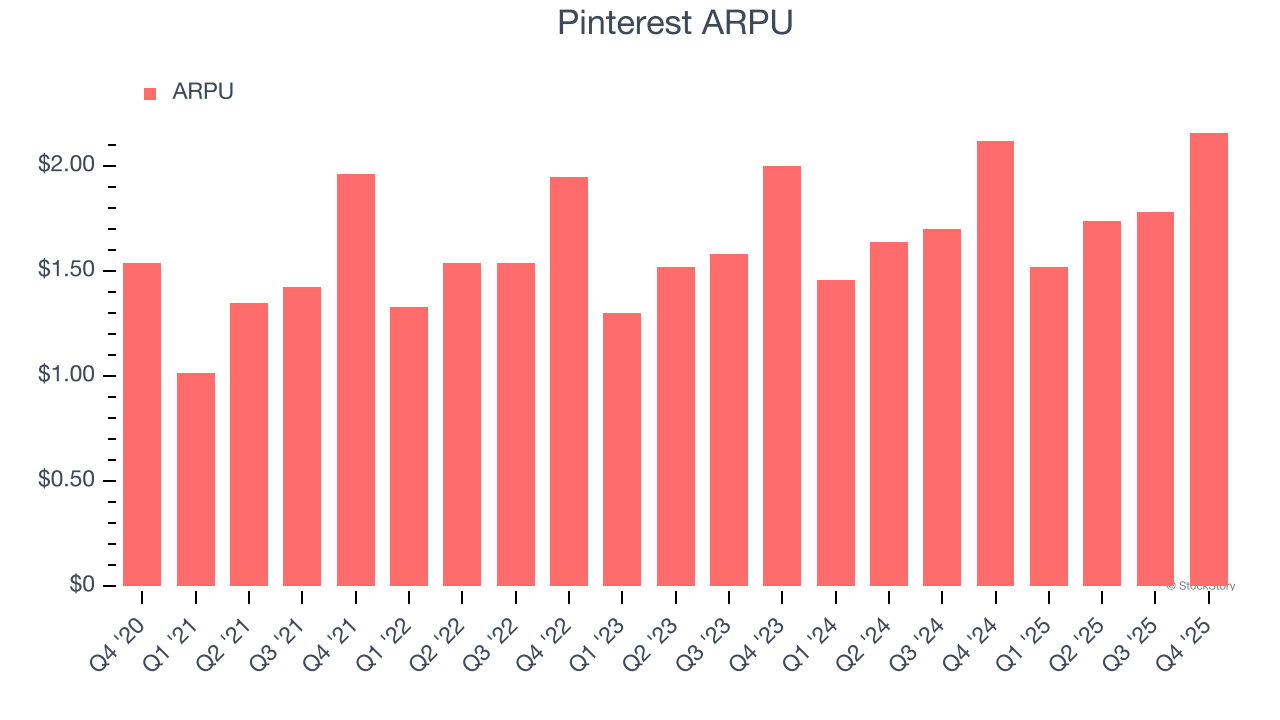
This quarter, Pinterest’s ARPU clocked in at $2.16. It grew by 1.9% year on year, slower than its user growth.
Key Takeaways from Pinterest’s Q4 Results
It was good to see Pinterest increase its number of users this quarter. On the other hand, its revenue guidance for next quarter missed and its EBITDA guidance for next quarter fell short of Wall Street’s estimates. Overall, this was a softer quarter. The stock traded down 15.9% to $15.54 immediately after reporting.
Pinterest may have had a tough quarter, but does that actually create an opportunity to invest right now? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Cerebras (CBRS.US) Cloud Business Soars, Masking Hardware Decline; OpenAI Supports Half of Cloud Revenue
Cerebras achieved record Q3 revenue, but hardware income dropped by nearly 30%, while cloud business accounted for two-thirds of total revenue. OpenAI contributed $72.4 million. The company raised its full-year guidance and expects Q4 to be close to breakeven.
Microsoft (MSFT.US) offers voluntary buyout packages to about 60,000 employees: Structural divergence in U.S. employment under AI transformation
In 2026, the U.S. labor market is characterized by both low layoffs and weak hiring. Companies like Microsoft and American Express are leveraging AI to optimize their workforce, while data centers are driving growth in the construction sector. However, entry-level white-collar jobs face increasing pressure, with real wages experiencing negative growth and structural transformation risks becoming more prominent.

"Inflation is really too high"! Federal Reserve "third-in-command": The Fed must continue to take action and promptly bring the price level back to 2%
John Williams, President of the New York Federal Reserve and the “number three” official at the Federal Reserve with a permanent voting right, stated that U.S. inflation remains high and policymakers must take further action to curb price pressures.

Jensen Huang steps down, and the "biggest patron" of new AI players is gone too
Anthropic's tens-of-billions IPO investment, Figure AI's additional $1 billion, and Nscale's over $5 billion credit guarantee are all in negotiations but their outcomes remain uncertain. Meanwhile, its $500 billion AI financing platform has stalled, and some clients are considering switching to AMD or Google. Successor Kress has a conservative style and has repeatedly vetoed deals aggressively promoted by Jensen Huang, signaling the possible end of Nvidia's era of bold investments.
Crypto prices
More


