
Coinbase Q4 Earnings Preview: Subscription Resilience Amid Trading Volume Challenges
1. Investment Highlights Overview
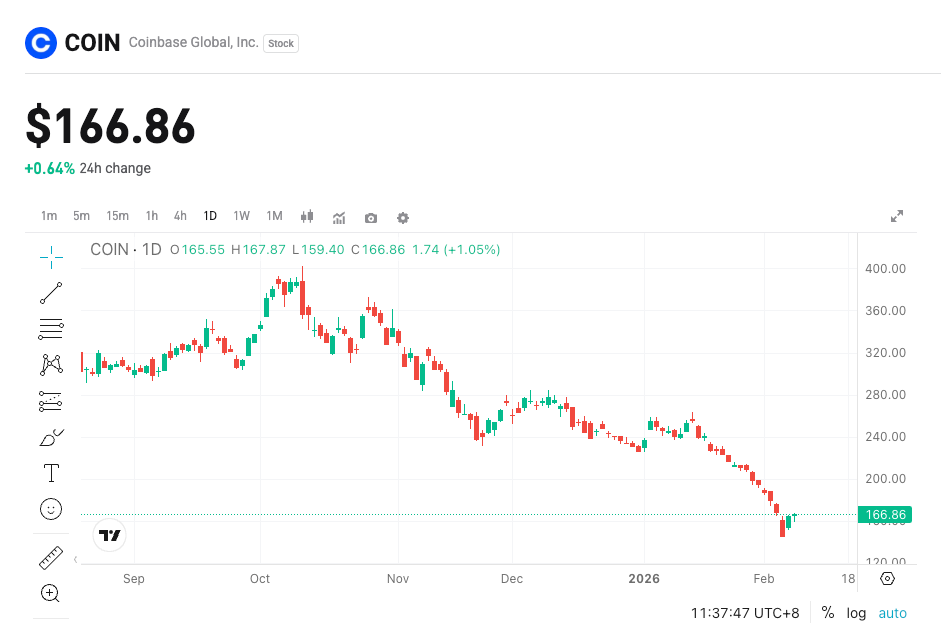
Coinbase is set to release its Q4 2025 earnings after the market close on Eastern Time February 12, 2026, with consensus estimates projecting revenue of $1.87 billion (+0.40% YoY), EBITDA of $410 million (-16.38% YoY), and adjusted EPS of $0.68 (-62.27% YoY). Key focus areas include the stability of trading operations and the ongoing expansion of subscription services, which could act as a buffer against market volatility and shape near-term stock performance. In a relatively stable crypto asset environment, investors are looking for signs of moderate recovery through cost discipline and diversified revenue streams.
2. Key Focus Areas
Focus 1: Trading Volume and Fee Dynamics
Trading remains the backbone of Coinbase's revenue, where market fluctuations directly impact income realization; higher retail engagement could boost blended fee rates, while institutional inflows offer volume stability but potentially lower margins. Watch for trading revenue expectations around the prior quarter's $1.05 billion, along with retail versus institutional volume splits—if volatility rises, it could drive higher transaction activity. Stronger-than-expected volumes might lift the stock by 5-10%, whereas intensified fee competition could miss estimates and add downward pressure.
Focus 2: Sustainability of Subscription and Services Segment
This area provides recurring revenue through custody fees and staking, offering resilience against cyclical trading downturns and helping smooth overall earnings volatility. Building on the previous quarter's $747 million in revenue, expectations lean toward continued strength from institutional capital inflows and expanded asset custody scales. Effective growth in custody partnerships and data offerings could push gross margins above 85%, bolstering long-term valuations; however, unfavorable network reward changes might weigh on net income and erode investor sentiment.
Focus 3: Operational Expense Management and Leverage
Cost control is crucial for amplifying profitability, as slower growth in marketing and product investments could mitigate EBITDA declines and foster a more efficient structure. Track expense trends against the last quarter's gross margin of 85.87% and net margin of 24.12%—consensus anticipates rising costs to pressure adjusted EPS. Outperforming on expense discipline could enhance the upside from modest revenue growth, supporting a stock rebound; persistent high spending, though, might raise concerns and lead to valuation discounts.
3. Opportunities and Risks Coexist
Upside Catalysts:
- Heightened crypto market volatility sparking a retail trading surge, exceeding revenue forecasts.
- Accelerated growth in subscription custody assets, delivering stronger recurring contributions.
- Clearer regulatory landscape boosting institutional adoption and product diversification.
Downside Risks:
- Aggressive fee competition eroding trading revenue realization.
- Elevated operational costs magnifying profit compression.
- Subdued crypto prices dampening overall transaction activity.
4. Trading Strategy Insights
Bullish Rationale: Robust subscription revenue paired with steady trading volumes and effective cost optimizations could beat consensus, propelling the stock past recent highs.
Bearish Risks: Significant misses on adjusted EPS or downward guidance signaling weak operational leverage might trigger short-term selling, testing support levels.
Key Metrics to Monitor:
- Total revenue ($1.87 billion expected)
- Subscription and services revenue (prior quarter $747 million)
- Adjusted EPS ($0.68 expected)
- Gross margin (prior quarter 85.87%)
Operational Guidance:
In an upside surprise scenario, consider initiating short-term long positions to capture quick gains. Should downside risks surface, Bitget now offers 20x leverage contracts for effective hedging or awaiting a pullback for entry. Overall, adopt a wait-and-see approach until full earnings details unfold, steering clear of rash pursuits.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Applied Materials (AMAT.US) Q4 Earnings Call: CEO Responds to Capacity Mismatch Concerns, Says No Customer Delayed Delivery; System Capacity Expected to Double by 2028
Applied Materials released its financial results for the fourth quarter of fiscal year 2026 (ending October 25, 2026) after the US stock market closed on November 12.
The End of an Era! Semianalysis: Without Jensen Huang, Nvidia Will Become the Next Apple
Semianalysis believes that Jensen Huang’s departure marks the end of a founder-driven era. Nvidia is highly likely to replicate the "post-Steve Jobs Apple model"—shifting from aggressive bets to stock buybacks—which is not beneficial for either technological advancement or shareholders. A greater concern is that the supply chain advantages, customer trust system, and open-source ecosystem moat personally built by Jensen Huang will be difficult for his successor to replicate. By 2028, over 70% of total production capacity may shift to non-Nvidia players.

Grayscale finds AI crypto sector volatility at 85%, links to Bitcoin weaken
Crypto prices
More


