
Amazon Q4 Earnings Preview: AWS Momentum + AI Investments = Another Explosive Beat?
1. Investment Highlights Quick View
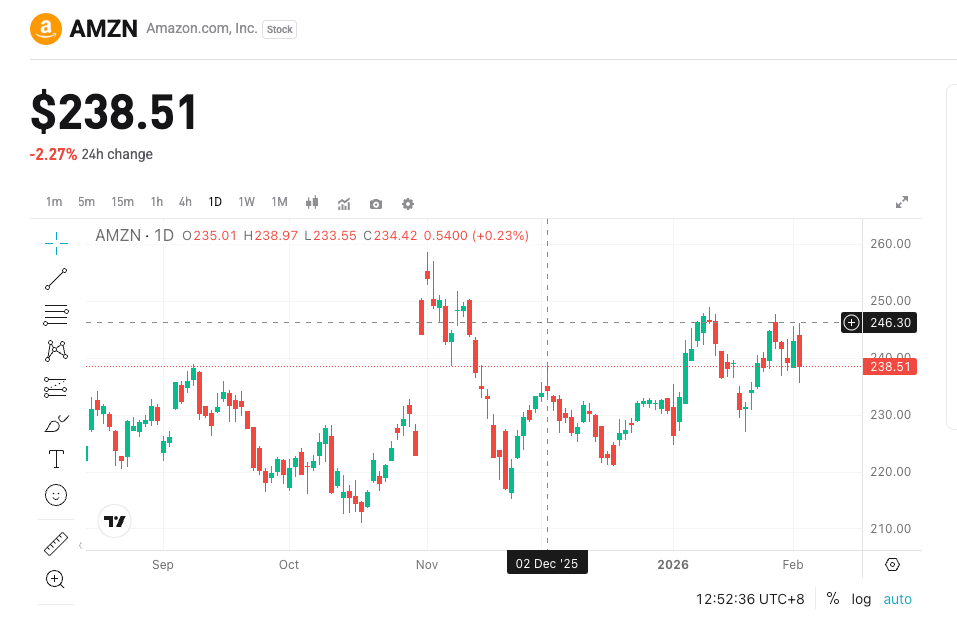
Amazon is set to release its fiscal 2025 fourth-quarter results after the market close on February 5 Eastern Time, with consensus revenue expectations at 207.95 billion USD near the lower end of management's guidance range of 206 billion to 213 billion USD (+11.56% YoY). Key investor focus centers on robust demand for AWS cloud services and strategic investments in AI infrastructure, which could drive results above forecasts and support stock upside. Amid a track record of beating estimates in recent quarters, Wall Street remains bullish, with analyst price targets suggesting around 30% potential gains, underscoring Amazon's appealing valuation among big tech peers.
2. Five Major Focus Points
Focus 1: AWS Supply-Demand Dynamics and Capacity Buildout
Strong AWS demand outpacing current supply is a critical driver for revenue growth and margin stability in this high-profit segment. Expanding capacity will help convert backlogged orders into immediate earnings, bolstering Amazon's edge in the AI cloud market. Key data: Q4 capacity additions expected over 1,000 megawatts, with full-year capex plans elevated; AWS margins historically outperform retail operations. Possible outcomes and impacts: Timely capacity rollout could push revenue toward the guidance upper end, lifting EPS; delays might cause short-term deferrals but set up stronger 2026 growth.
Focus 2: Surging Capex for AI Infrastructure
Amazon's heavy spending on AI data centers aims to capitalize on cloud and generative AI trends, promising higher long-term returns despite near-term pressures. This positions the company for outsized profit expansion compared to rivals. Key data: 2026 capex projected over 1,500 billion USD (highest among the Magnificent Seven); AWS targets doubling capacity by 2027 end. Possible outcomes and impacts: Effective deployment could enhance return on invested capital, sparking stock revaluation; if undervalued by markets, it creates post-earnings buying dips for optimistic investors.
Focus 3: Workforce Streamlining and Operational Savings
Optimizing staff levels and shifting to AI-enhanced processes will cut costs, freeing up capital for growth initiatives and improving overall profitability. While initial adjustments may disrupt, they build financial resilience over time. Key data: Targeted 10% workforce reduction; trailing twelve-month operating income jumped from 22 billion USD to 686 billion USD. Possible outcomes and impacts: Better-than-expected efficiencies could boost adjusted margins and EPS directly; poor implementation risks temporary productivity dips.
Focus 4: Free Cash Flow Trends and Investor Perceptions
Concerns over declining free cash flow may be overstated, stemming from investment phases rather than core weaknesses. As orders materialize, FCF should recover, enabling better shareholder returns. Key data: Past cycles show ROIC rebounds post-investment peaks; current forward P/E is the lowest among large caps. Possible outcomes and impacts: Clear FCF guidance in earnings could trigger a stock rally; persistent doubts might heighten volatility but offer entry points at lower prices.
Focus 5: 2026 Guidance and Valuation Outlook
Expectations for next year's projections appear cautious, but Amazon's execution history suggests potential for upside surprises, acting as a major stock catalyst. With leading EPS growth rates, the stock trades at a discount to peers. Key data: 2027 EPS forecast at 10.79 USD; average target price 312.82 USD (29x P/E, +28.7% upside). Possible outcomes and impacts: Stronger-than-consensus guidance could fuel valuation expansion and inflows; subpar outlooks might lead to near-term pullbacks without altering long-term appeal.
3. Risks and Opportunities Coexist
Upside Catalysts:
- Accelerated AWS capacity deployment, speeding order fulfillment and adding high-margin revenue, potentially leading to Q4 beats on revenue and EPS.
- Early AI investment payoffs, with upward 2026 revisions affirming growth narrative and drawing more institutional interest.
- Notable cost reductions from efficiencies, generating excess free cash for buybacks or dividends, enhancing shareholder appeal.
Downside Risks:
- Excessive capex straining short-term free cash flow, if viewed negatively, could prompt stock sell-offs.
- Disruptions from staff cuts affecting operations or public image, hindering execution in the quarter.
- Broader economic headwinds slowing demand, resulting in conservative guidance and pressure on multiples.
4. Trading Strategy Suggestions
Bullish Logic:
Look for upside if AWS strength and AI progress yield results exceeding guidance, validating the growth story and encouraging fresh capital inflows.
Bearish Risks:
Potential declines if capex returns lag or free cash weakens further, especially in a tightening macro environment amplifying downside.
Key Data:
- Total revenue (207.95 billion USD expected, watch for guidance upper bound hit).
- EPS performance (consistent beats historically, monitor surprise magnitude).
- AWS growth rate (+XX.X% YoY, with capacity additions as a lead indicator).
- Capex outlook (over 1,500 billion USD for 2026, impacting future ROIC).
Operation Suggestions:
If earnings top expectations with positive 2026 commentary, consider building long positions during post-report gains; conversely, if below consensus, stay sidelined. Focus on conference call insights into AI and efficiencies to guide medium-term trades.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Jensen Huang out, Nvidia's $500 billion AI financing plan is also in jeopardy
The AI financing platform led by Jensen Huang has seen zero transactions since its high-profile launch in August. The core issue lies in Nvidia's guarantee rate of only 25%, which is significantly lower than competitor Broadcom's maximum of 72.5%, resulting in little interest from lenders. Analysts believe that, having lost its visionary leader and facing pressure from Wall Street to assume more risk, the project is unlikely to be implemented any time soon.
Four consecutive gains! Short-term US Treasury yields record fastest increase since 2022 as market bets on Fed rate hike
U.S. short-term Treasury yields have soared sharply for four consecutive trading days, with the 2-year yield rising to 4.862%, accumulating a 38.8 basis point increase—the largest four-day gain since June 2022. The 10-year yield simultaneously broke through the critical 5.10% threshold. Real interest rates have climbed as well, and the market has significantly raised its terminal rate expectations to 4.82%. An interest rate hike in December is now almost certain, while the probability of another hike in January stands at 75%.
Gold falls to over one-year low below $3,900 amid inflation concerns, US PPI data looms
Cisco Q1 revenue grows 24% year-on-year, fastest in over 15 years, AI infrastructure income expected to double|Earnings Report Highlights
Cisco's first-quarter revenue reached $18.5 billion, with adjusted earnings per share at $1.40, both exceeding market expectations. The company raised its full-year revenue guidance to $74.8 billion-$75.8 billion, and expects AI infrastructure revenue to reach $9 billion this fiscal year, doubling from the previous year. The CEO stated that the company is in the early stages of a multi-year networking supercycle.
Crypto prices
More


