
Alphabet Q4 Earnings Preview: Outperformance and Capex Guidance in Focus
1.Investment Highlights Overview
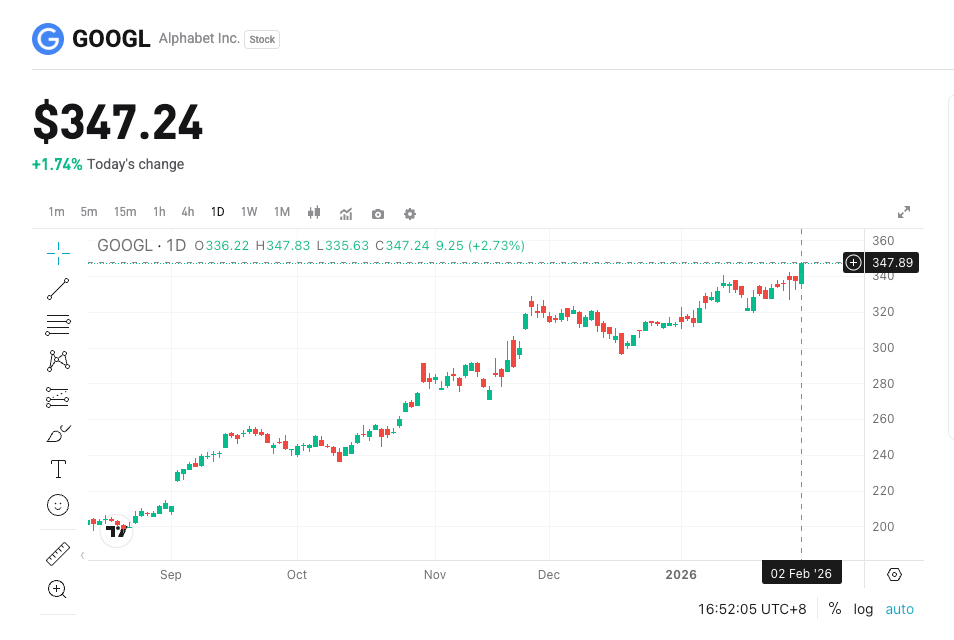
Alphabet is set to release its fiscal Q4 2025 earnings after the US market close on February 4, with Wall Street anticipating revenue of $95.2 billion and adjusted EPS of $2.64. Key focus areas include robust growth in advertising and cloud segments, potentially surpassing consensus estimates, alongside capex guidance that underscores AI infrastructure investments. Amid stabilizing digital ad markets and accelerating AI adoption, this report could offer investors a vital lens into the company's growth trajectory and valuation merits.
2.Key Focus Areas
Focus 1: Accelerated Advertising Growth
Advertising remains Alphabet's primary revenue driver, directly impacting profitability and stock performance. Integration of AI tools like Gemini 3.0 enhances targeting precision in search and YouTube, helping mitigate traffic variability and boost demand recovery. Key metrics: Search revenue expected at $61.9 billion (+15.0% YoY), YouTube ad revenue at $12.0 billion (+15.0% YoY). Strong results could bolster investor sentiment and drive short-term stock gains; slower growth might raise concerns over economic sensitivity.
Focus 2: Rapid Cloud Expansion
Cloud services serve as a high-growth pillar, highlighting Alphabet's edge in AI and data centers, which supports long-term valuation. AI optimizations attract major clients, creating competitive differentiation. Key metrics: Cloud revenue projected at $16.2 billion (+35.0% YoY). Outperformance may reinforce optimism on diversified growth and enhance stock resilience; subpar results could signal intensifying rivalry and dampen bullish views.
Focus 3: Capex Intensity and Efficiency
Capex levels reveal commitment to AI infrastructure, influencing future competitiveness and earnings sustainability. Investors eye how spending translates to revenue gains, especially amid peers' aggressive outlays. Key metrics: Q4 capex forecasted at $29.2 billion (+105.0% YoY, +22.0% QoQ), with FY2026 at $139.0 billion (exceeding market consensus of $119.0 billion). Upward guidance with efficiency emphasis might spark a rally; excessive spending without timely returns could fuel cash flow worries.
Focus 4: Cost Management and Margin Improvement
Controlling operating expenses is crucial for sustaining high margins amid workforce growth and depreciation pressures, tying directly to EPS delivery and shareholder value. Key metrics: Operating expenses expected at $28.0 billion (+13.0% YoY), operating margin at 39.1% (+1.19% YoY). Margin expansion could affirm operational prowess and aid valuation recovery; overruns might dilute profits and trigger near-term selling.
Focus 5: Other Income and Cash Flow Trends
Other income, including equity revaluations, adds variability but buffers overall finances, while free cash flow gauges capital generation strength. Key metrics: Other income anticipated at $1.3 billion, Q4 free cash flow at $11.7 billion (-53.0% YoY). Positive surprises could strengthen the balance sheet and draw value investors; shortfalls might heighten scrutiny on investment returns and reduce trading interest.
3. Risks and Opportunities Coexist
Upside Catalysts:
- AI enhancements lift ad conversion rates, exceeding the 13% growth forecast and propelling search/YouTube revenues.
- Securing major AI cloud deals solidifies growth narrative, with 2026 capex efficiency outpacing competitors.
- Equity revaluations yield unexpected gains, bolstering other income and supporting higher EPS.
Downside Risks:
- Soft digital ad demand drags search and YouTube growth below 15%, amplifying cyclical vulnerabilities.
- Sharp capex hikes with delayed payoffs strain free cash flow and spark financial stress concerns.
- Heightened competition in AI ads erodes market share and compresses margins.
4. Trading Strategy Insights
- Bullish Logic: Revenue and EPS beats, coupled with capex guidance highlighting AI ROI, could fuel positive momentum, ideal for capitalizing on post-earnings upside.
- Bearish Risks: Cloud deceleration or elevated costs, combined with rich valuations, may lead to pullbacks, particularly in volatile markets.
- Key Metrics: Monitor total revenue ($95.2 billion expected), cloud revenue ($16.2 billion), Q4 capex ($29.2 billion), and operating margin (39.1%).
- Operational Suggestions: In favorable scenarios, consider holding short-term to leverage AI-driven catalysts; if risks emerge, implement stops to guard against downside and track follow-up quarters for growth validation.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Jensen Huang out, Nvidia's $500 billion AI financing plan is also in jeopardy
The AI financing platform led by Jensen Huang has seen zero transactions since its high-profile launch in August. The core issue lies in Nvidia's guarantee rate of only 25%, which is significantly lower than competitor Broadcom's maximum of 72.5%, resulting in little interest from lenders. Analysts believe that, having lost its visionary leader and facing pressure from Wall Street to assume more risk, the project is unlikely to be implemented any time soon.
Four consecutive gains! Short-term US Treasury yields record fastest increase since 2022 as market bets on Fed rate hike
U.S. short-term Treasury yields have soared sharply for four consecutive trading days, with the 2-year yield rising to 4.862%, accumulating a 38.8 basis point increase—the largest four-day gain since June 2022. The 10-year yield simultaneously broke through the critical 5.10% threshold. Real interest rates have climbed as well, and the market has significantly raised its terminal rate expectations to 4.82%. An interest rate hike in December is now almost certain, while the probability of another hike in January stands at 75%.
Gold falls to over one-year low below $3,900 amid inflation concerns, US PPI data looms
Cisco Q1 revenue grows 24% year-on-year, fastest in over 15 years, AI infrastructure income expected to double|Earnings Report Highlights
Cisco's first-quarter revenue reached $18.5 billion, with adjusted earnings per share at $1.40, both exceeding market expectations. The company raised its full-year revenue guidance to $74.8 billion-$75.8 billion, and expects AI infrastructure revenue to reach $9 billion this fiscal year, doubling from the previous year. The CEO stated that the company is in the early stages of a multi-year networking supercycle.
Crypto prices
More


