
Meta Q4 Earnings Preview: AI-Driven Growth vs. Metaverse Drag on Profits
1.Investment Highlights Overview
Meta Platforms is set to release its Q4 2025 earnings after the US market close on January 28, 2026, with consensus estimates projecting revenue of $56.59 billion (+21% YoY) and EPS of $8.21. Key investor focus lies on robust ad revenue momentum amid holiday spending, balanced against escalating AI capex and ongoing Reality Labs losses that could pressure margins. In a volatile tech sector, this report will spotlight Meta's ability to sustain growth while managing innovation costs, potentially influencing short-term stock volatility.
2. Key Focus Areas
Focus 1: Advertising Momentum
Ad revenue remains Meta's primary growth engine, directly impacting overall financial stability and investor sentiment. With AI enhancements optimizing ad delivery, ranking, and conversions during the peak holiday season, sustained strength here could affirm the company's monetization edge. Q3 ad revenue hit $50.1 billion (+26% YoY), driven by a 14% increase in impressions and a 10% rise in average ad pricing; exceeding Q4 expectations might fuel stock upside, while any slowdown could heighten concerns over economic headwinds.
Focus 2: Reality Labs Performance
This segment embodies Meta's long-term bet on metaverse and AR/VR tech, yet its persistent losses weigh on profitability and raise questions about resource allocation. Investors will scrutinize revenue trends and cost controls, as any signs of narrowing deficits could boost confidence in strategic pivots. Q3 saw operating losses of $4.43 billion against $470 million in revenue (+74% YoY), but management anticipates a Q4 revenue dip due to no new VR headset launches; improved loss management might signal progress, whereas widening gaps could erode long-term appeal.
Focus 3: User Growth and Engagement
Expanding user base and time spent are foundational to Meta's ad ecosystem, especially in mature markets like the US where AI-driven recommendations are boosting retention. Strong metrics here reinforce competitive moats against rivals and support revenue scaling. Q3 daily active family app users reached 3.54 billion (+8% YoY), with double-digit time-spent growth on Facebook and Instagram in the US; surpassing Q4 forecasts could solidify bullish views, but stagnation might highlight saturation risks.
Focus 4: AI Infrastructure Spending
Meta's aggressive AI investments in data centers and hardware underpin future innovations but inflate short-term expenses, testing the balance between growth and efficiency. Market scrutiny will center on ROI visibility, as effective ad improvements from these outlays could justify the costs. Full-year capex is guided at $70-72 billion, with "significantly larger" increases eyed for 2026; positive AI-driven efficiencies in the report might catalyze rallies, but uncontrolled overruns could amplify margin squeeze fears.
Focus 5: 2026 Guidance Outlook
Forward-looking commentary on revenue, expenses, and AI monetization paths will shape medium-term valuations, particularly amid investor sensitivity to tech spending. Optimistic signals could attract sustained capital inflows. Annual total expenses are projected at $116-118 billion (+22%-24% YoY); a guidance beat with clear efficiency gains might enhance appeal, while conservative tones could trigger pullbacks.
3. Risks and Opportunities
Upside Catalysts:
- AI enhancements exceed forecasts, lifting ad pricing and conversions for revenue beats.
- Accelerated user engagement in emerging markets, amplified by seasonal effects, strengthens ecosystem value.
- Reality Labs shows loss narrowing with promising AR glasses demand, indicating a metaverse inflection point.
Downside Risks:
- Surging capex erodes margins, especially if AI infrastructure costs spiral without immediate returns, dragging EPS below consensus.
- Macro slowdowns curb ad growth, with impressions or pricing declines signaling demand weakness.
- Intensified competition or regulatory hurdles, like from TikTok, stall user expansion and market share.
4. Trading Strategy Suggestions
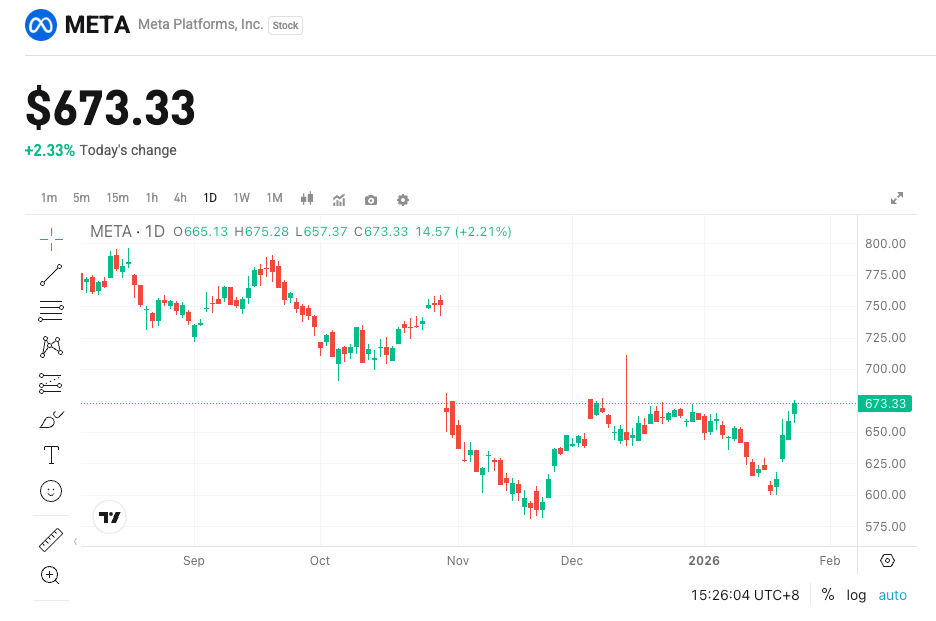
Bullish Logic: If Q4 revenue and EPS top consensus, coupled with upbeat 2026 guidance highlighting AI payoffs, the stock could break recent highs and challenge the $796.25 all-time peak.
Bearish Risks: Should expense guidance rise without solid ROI proof, or Reality Labs losses widen, shares might breach the $580-595 support zone and test $479.80 lows.
Key Data Points:
- Revenue: Watch for $56.59 billion (+21% YoY) as a gauge of growth traction.
- EPS: $8.21, assessing core profitability after adjustments.
- Capex: Q4 actuals versus full-year $70-72 billion guide, evaluating AI commitment.
- Daily Active Users: Above 3.54 billion (+8% YoY), indicating platform stickiness.
- Operational Suggestions: Prior to the earnings release, consider leveraging volatility via Meta options contracts to capture potential price swings; if the data exceeds expectations, short-term bulls may ramp up positions targeting a rebound, while setting a stop-loss at $580; in the event of negative surprises, bears could monitor high-volume breakdowns for opportunities, but remain vigilant against rebound risks stemming from analysts' prevailing "strong buy" consensus.
Disclaimer: The above content is for reference only and does not constitute any investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Cisco (CSCO.US) Q1 revenue up 24%, strongest in 15 years; AI infrastructure revenue expected to double to $9 billion, shares surged over 8% after hours
Network equipment giant Cisco released its financial report for the first quarter of fiscal year 2027 after the US market closed on November 12, with both revenue and profit exceeding expectations, and raised its full-year guidance.
A Record 27 Trillion Yen Intervention Fails as Yen Once Again Approaches 160: The Tug-of-War Dilemma for the World's Most Difficult Currency to Trade
In recent months, the exchange rate has remained tightly anchored within a narrow range around 1 USD to 158 JPY. However, on Wednesday, it broke through again: unexpectedly for traders, the yen weakened and approached the 160 mark.
Overnight US Stocks | The Three Major Indices Closed Lower, Nvidia (NVDA.US) Closed Down 4.3%
At the close, the Dow Jones Industrial Average fell by 189.40 points, or 0.36%, to 52,297.09 points. The S&P 500 Index declined by 26.98 points, or 0.35%, to 7,592.40 points. The Nasdaq Composite Index dropped 100.10 points, or 0.39%, to 25,366.09 points.
Tim Draper predicts Bitcoin will integrate altcoin innovations, boost market dominance
Crypto prices
More


