
Should the Fed cut 50bps in September?

We’re beginning to price in the chance of not just a 25 basis point cut, but a 50 bps one
This is a segment from the Forward Guidance newsletter. To read full editions, subscribe .
It’s amazing how quickly things can change in one week.
It feels like only yesterday that the Fed appeared unlikely to cut rates at all in September. Now, we’re beginning to price in the chance of not just a 25 basis point cut, but a 50 bps one!
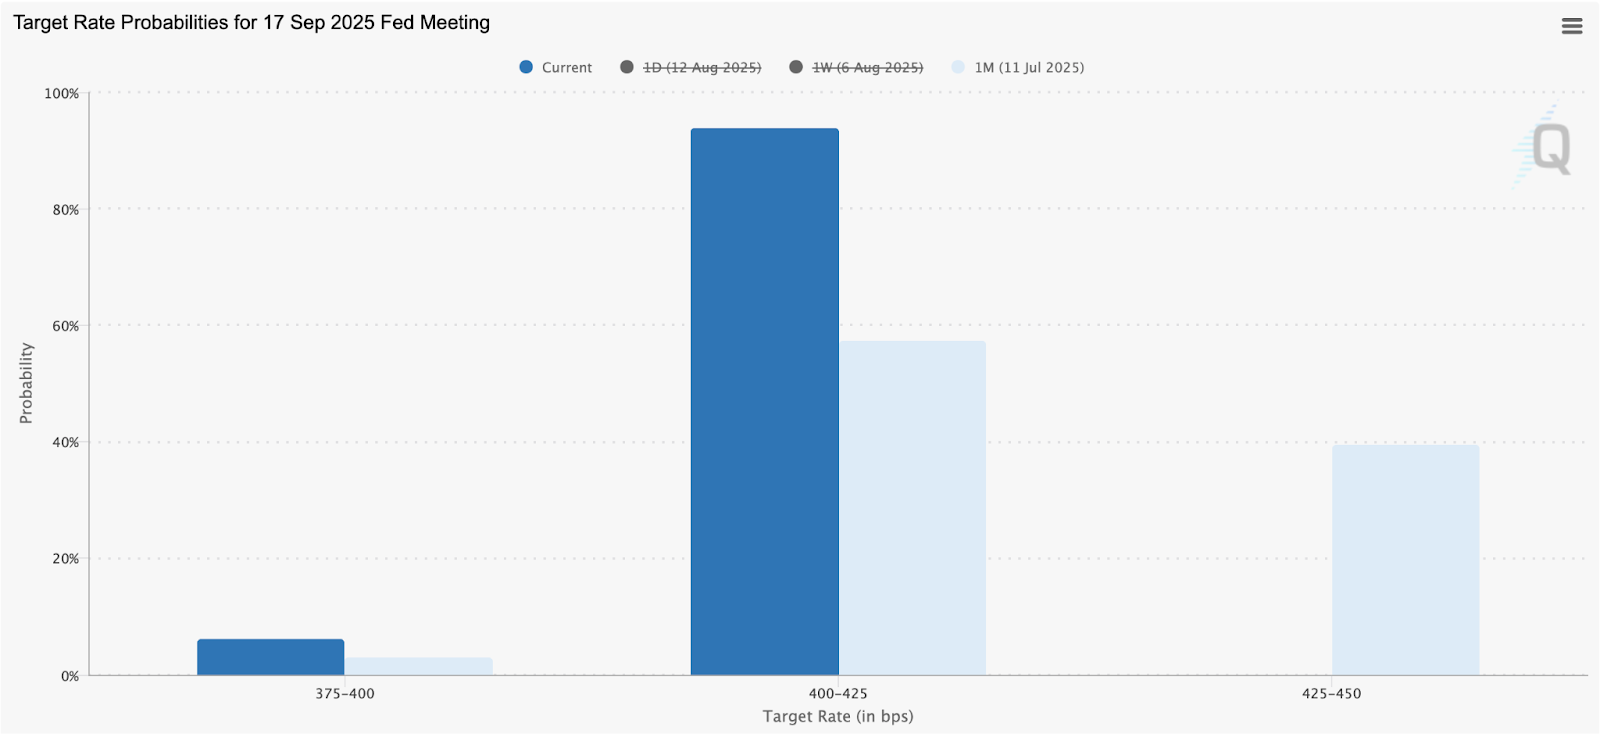
In a Tuesday Fox Business interview, Treasury Secretary Bessent added fuel to the speculation by saying “the real thing now to think about is: Should we get a 50 basis point rate cut in September?”
I’m old enough to remember when Bessent said he wouldn’t comment on future monetary policy decisions. But here we are.
So, should the Fed cut 50 bps in September? Let’s look at both sides of the argument.
No cuts
Although this month’s CPI print was pretty tame and consensus, there are some underlying inflation pressures building.
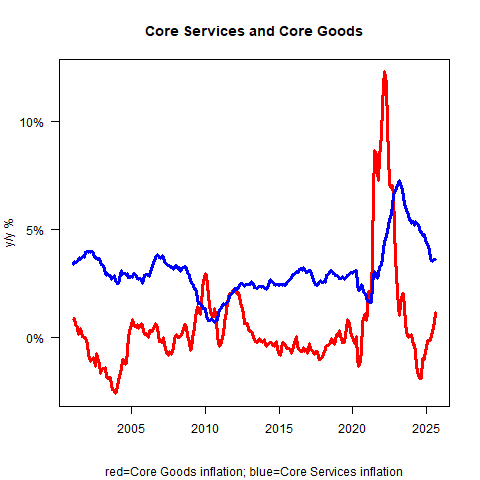
Core goods, one of the biggest drivers of the disinflation story over the last couple years, is now beginning to accelerate higher, largely driven by tariffs:
Despite a pretty nasty jobs report last week, forward-looking estimates point to a labor market that is beginning to reaccelerate again.
In the most recent business headcount surveys, the amount of businesses that planned on meaningfully increasing headcount in the next year bounced higher: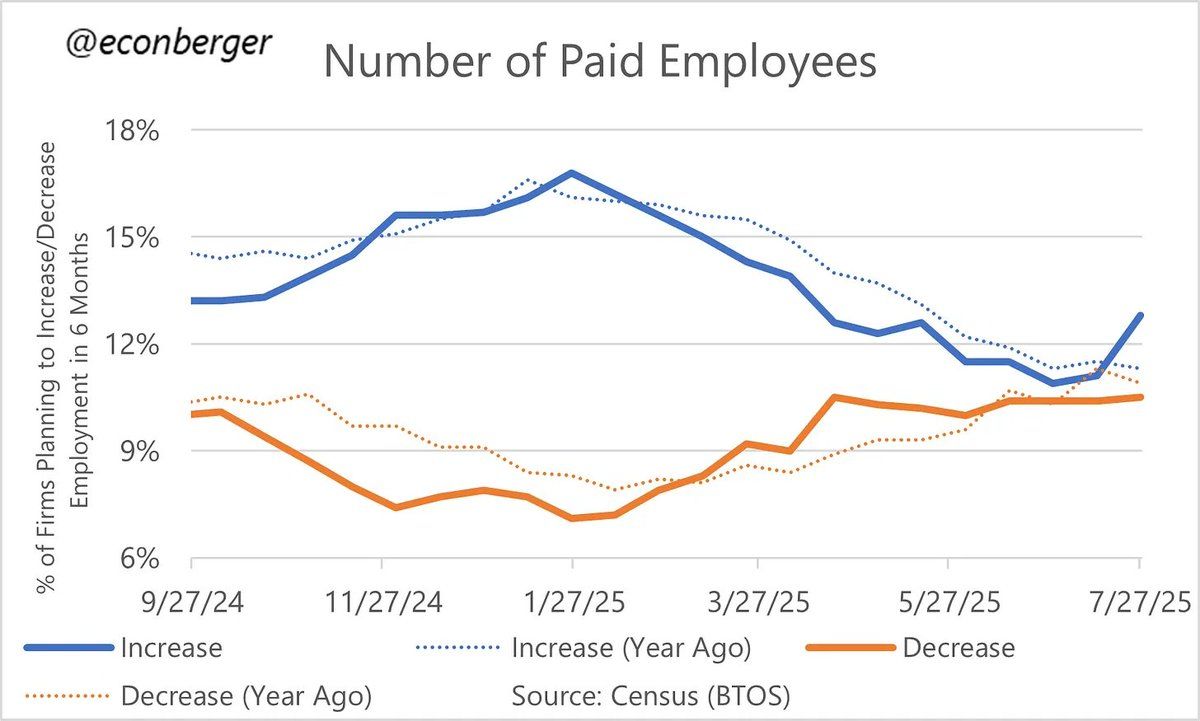
Looking at Visa’s US spending momentum index, the consumer appears pretty resilient in the face of tariffs and their spending habits are looking like they’re beginning to tick higher: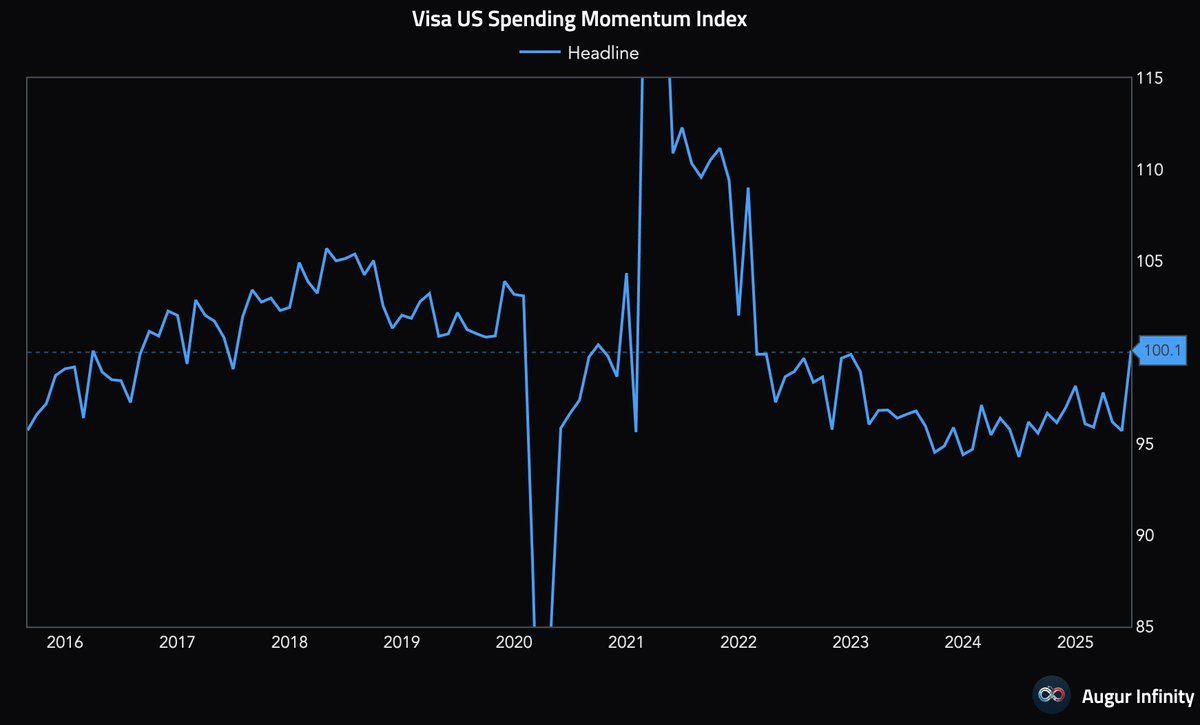
Based on this confluence of data, I could make the argument that the economy is beginning to reaccelerate. If the Fed were to cut in September based on lagging data such as NFP, it could end up being a mistake that makes the bond market sell off like it did last year when the Fed did the same thing.
Cut and go big
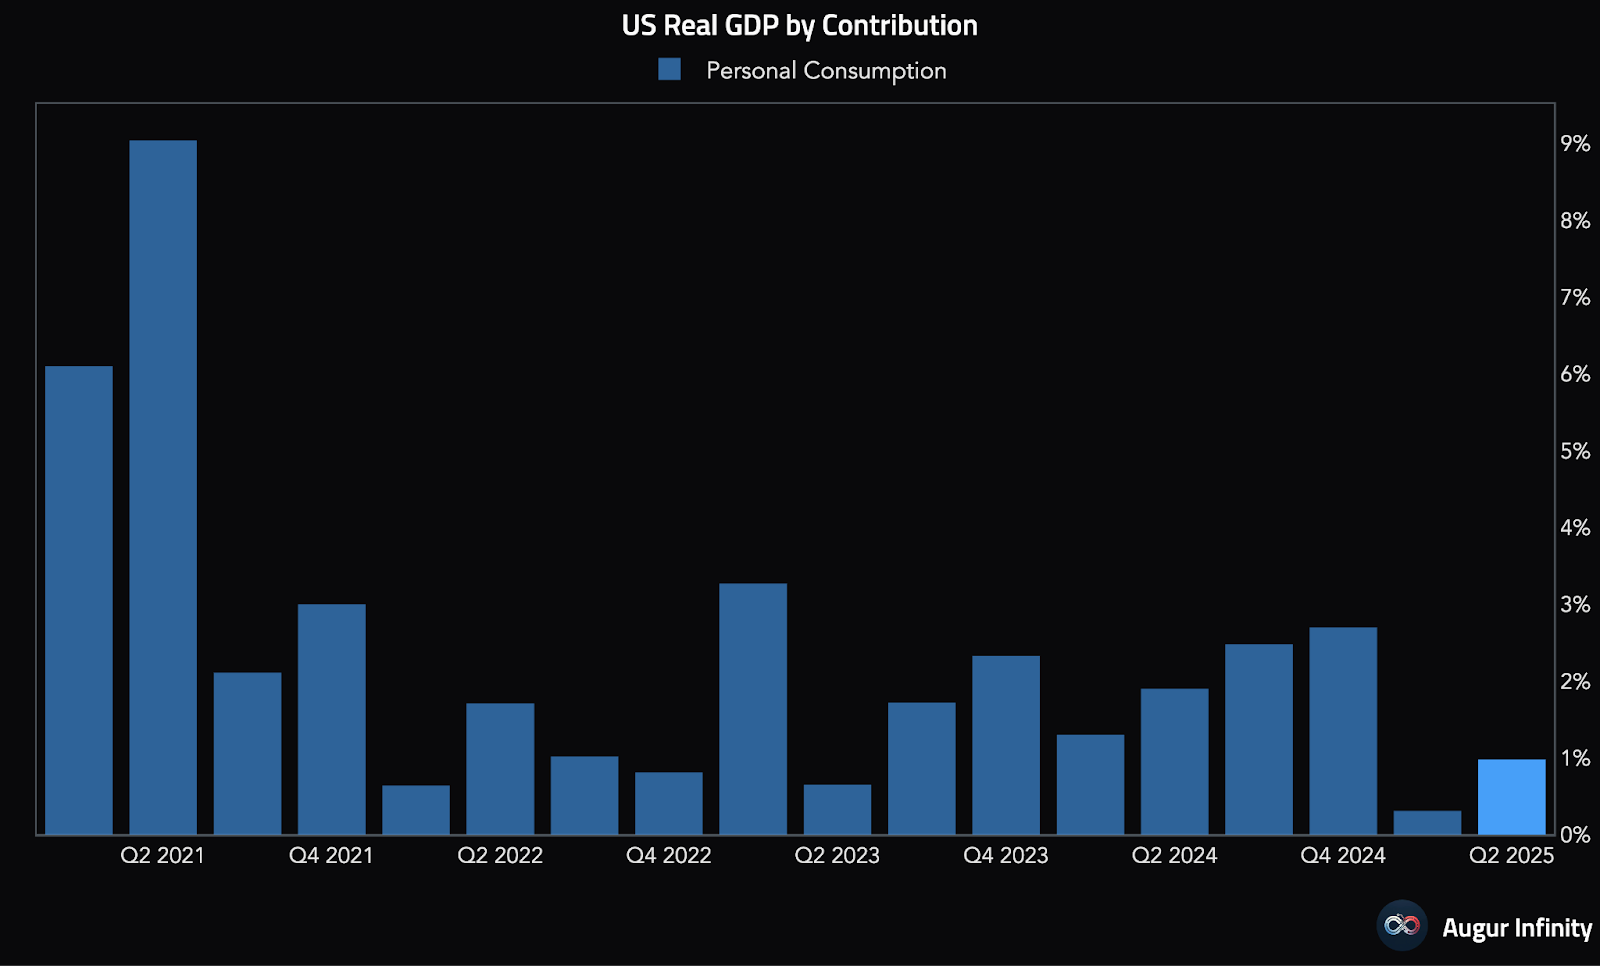
Consumption is the engine that drives the US economy. Ever since Q4 2024, it’s been meaningfully slowing.
If purchasing power decreases due to the continued implementation of tariffs, we could well see further weakening in consumer spending that could quite quickly look recessionary.
Meanwhile, tariff collections continue to surge higher — and someone needs to foot that bill: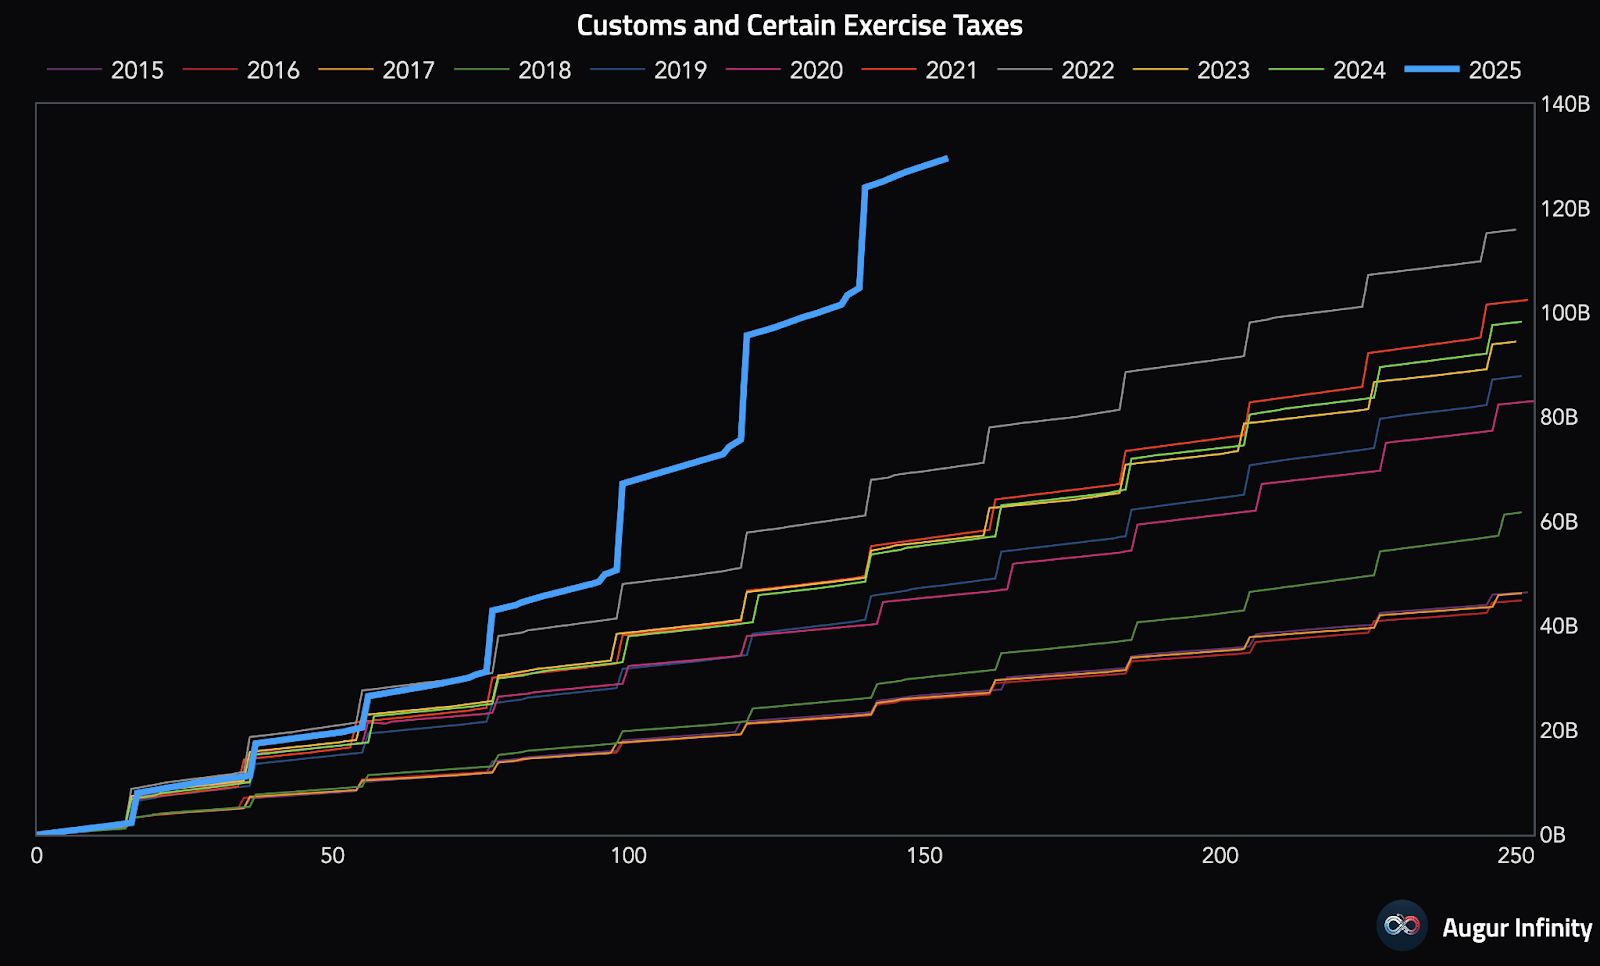
If companies pass on the tariffs to the consumer, those higher prices will eventually hurt aggregate demand since that additional price increase means that money cannot be spent elsewhere. Without an offset, this is negative for growth.
If companies absorb the price hikes, it will squeeze their corporate profit margins, which will also lower economic output. Either way, it’s negative for the growth outlook.
Finally, with a labor market that continues to surprise to the downside with downward revisions that continue to tick lower pro-cyclically, some sort of insurance rate cut could make sense here. 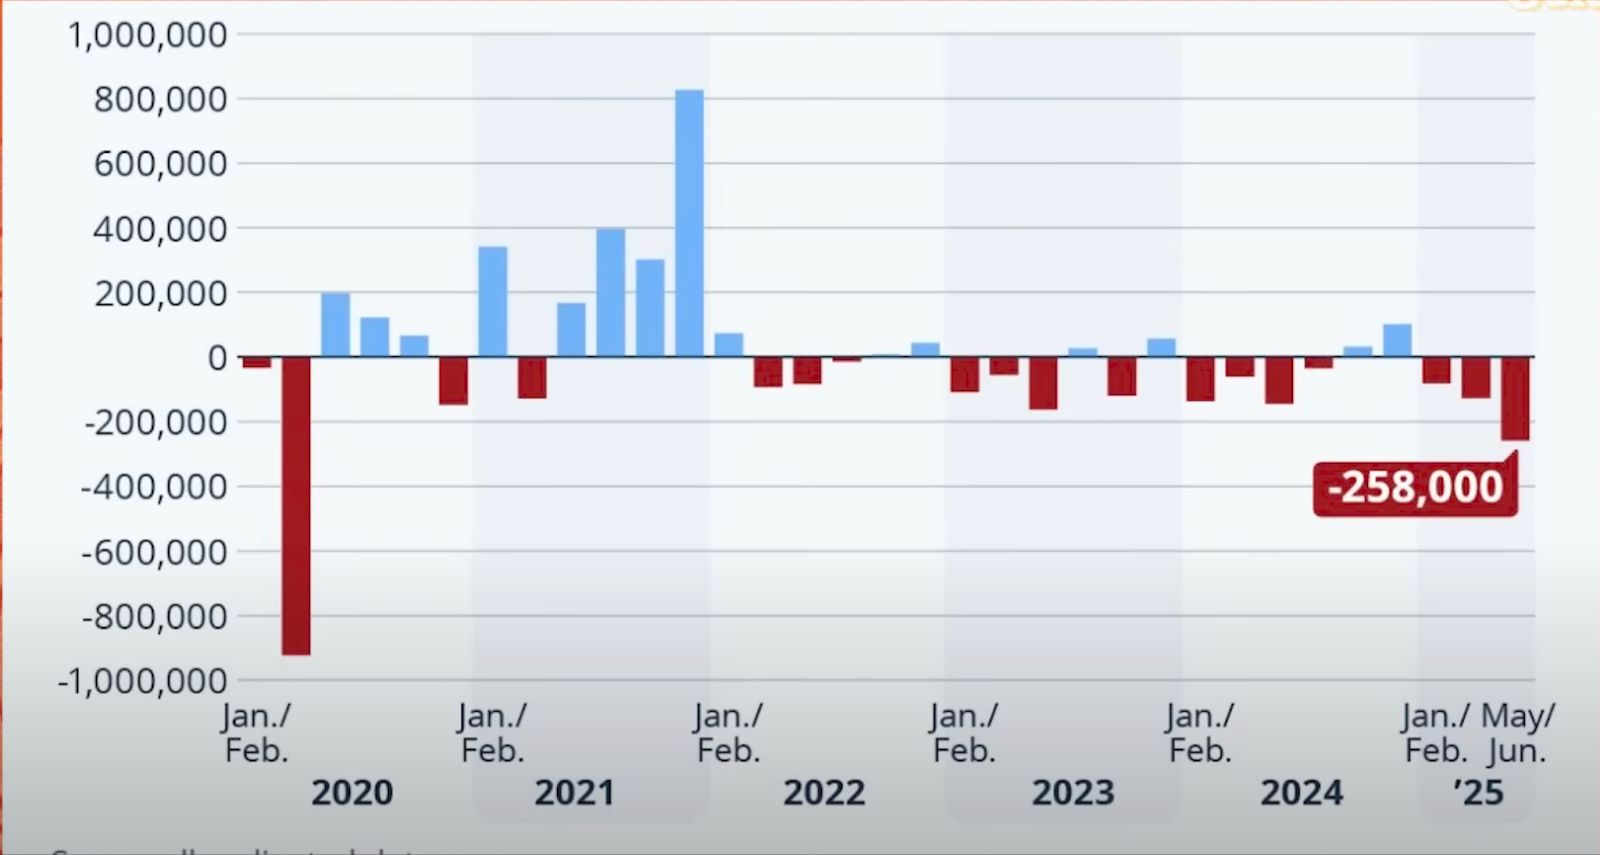
Putting it all together, I can make the case for a pause as much as I can make a case for substantial cuts.
It’s no wonder the FOMC, on the question of where to go from here, is the most divided it’s been in decades.
Get the news in your inbox. Explore Blockworks newsletters:
- The Breakdown : Decoding crypto and the markets. Daily.
- 0xResearch : Alpha in your inbox. Think like an analyst.
- Empire : Crypto news and analysis to start your day.
- Forward Guidance : The intersection of crypto, macro and policy.
- The Drop : Apps, games, memes and more.
- Lightspeed : All things Solana.
- Supply Shock : Bitcoin, bitcoin, bitcoin.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
How much CPO demand will Nvidia Rubin Ultra generate? Bernstein: Optical value per Pod will increase fivefold
Bernstein believes that the co-packaged optics (CPO) and fiber demand driven by Nvidia's Rubin Ultra architecture will surge significantly, with the optical content per Pod rising from $1 million to $5.4 million. This will propel the size of Nvidia's optical ecosystem market to $46.8 billion by 2028 (a 91% annual increase). Although the industry faces supply bottlenecks with InP substrates, the outlook remains positive. The institution reiterates its “outperform” rating for Lumentum, Coherent, and Ciena.

UBS Q3 implements a two-way strategy with gold options, heavily invests in technology stocks, and builds positions in SK Hynix (SKHY.US)
UBS Group (UBS.US) has submitted its Q3 holdings report (13F) as of September 30, 2026.

SpaceX (SPCX.US) reportedly attempts “de-Nvidiaization” at the rack level: developing Kessel cabinets to bypass L6 compute boards, purchasing only chips
SemiAnalysis: SpaceX has developed its own Kessel cabinet, bypassing Nvidia's L6 cards to provide more options for manufacturing its own hardware.

$3.7 billion “data center power equipment prepayments” abandoned! What did "the most active buyer of gas turbines", SoftBank, see?
In the second quarter of fiscal year 2026, SoftBank reported a net loss of $7.1 billion, primarily due to a $3.7 billion impairment charge from a $9.5 billion advance payment for power generation equipment for US data centers—of which about $2.9 billion was non-refundable and effectively lost. The CFO admitted that SoftBank placed orders before the project plan was finalized, and is now conducting a comprehensive review of its procurement strategy. "The most aggressive purchaser of gas turbines has now written off the deposit in this way."
Crypto prices
More


