
Is Circle Ready for Wall Street? Analysts Warn of Troubled Financials

Circle's IPO filing reveals growth in revenue but a decline in profitability, leading to skepticism among analysts regarding its long-term sustainability and valuation.
Circle’s initial public offering (IPO) filing has raised concerns among industry experts, who are sounding alarms over the company’s financial health, distribution costs, and valuation.
While the move marks a significant step toward mainstream financial integration, experts’ skepticism casts doubt on the company’s long-term prospects.
Analysts Highlight Red Flags With Circle IPO
On April 1, BeInCrypto reported that Circle had filed for an IPO. The company plans to list its Class A common stock on the New York Stock Exchange (NYSE) under “CRCL.”
Circle’s IPO filing reveals revenue of $1.67 billion in 2024, a notable increase from previous years. However, a closer examination of the company’s financials has uncovered some challenges.
Matthew Sigel, Head of Digital Assets Research at VanEck, noted that revenue increased 16% year over year. Yet, at the same time, the company reported a 29% decrease in EBITDA year over year, indicating a decline in operational profitability. Additionally, net income fell by 42%, reflecting a significant drop in overall profitability.
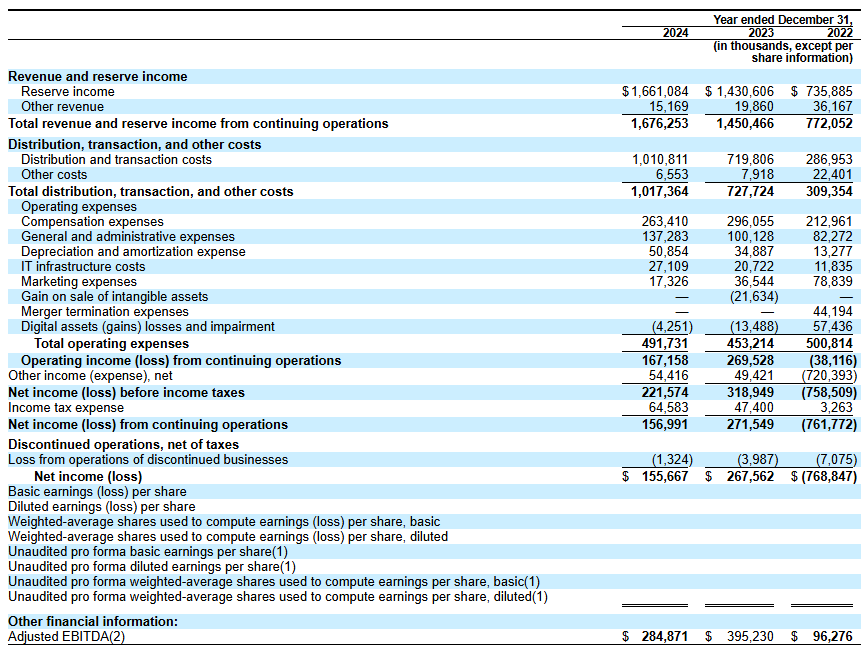 Circle Financial Data. Source:
X/MatthewSigel
Sigel pointed out four factors contributing to the decline in these financial metrics. He explained that the company’s rapid expansion and new service integrations negatively impacted net income.
Furthermore, the discontinuation of services like Circle Yield reduced other revenue streams. This, in turn, exacerbated the decline in profitability.
“Costs related to restructuring, legal settlements, and acquisition-related expenses also played a role in the decline in EBITDA and net income, despite overall revenue growth,” Sigel added.
Importantly, he focused on Circle’s increased distribution and transaction costs. Sigel revealed that the cost rose due to higher fees paid to partners like Coinbase and Binance.
A related post by Farside Investors on X (formerly Twitter) shed further light on these expenses.
“In 2024, the company spent over $1 billion on “distribution and transaction costs,” probably much higher than Tether as a % of revenue,” the post read.
This prompts speculation that Circle may be overspending to maintain its market share in the competitive stablecoin sector. The company’s historical performance further fuels skepticism.
Farside Investors added that in 2022, Circle recorded a staggering $720 million loss. Notably, the year was marked by significant turmoil in the crypto industry, including the high-profile collapses of FTX and Three Arrows Capital (3AC).
This suggests that Circle may be vulnerable to market shocks. Thus, it calls into question the company’s risk management capabilities—especially in the inherently volatile crypto market.
“The gross creation and redemption numbers are a lot higher than we would have thought for USDC. Gross creations in a year are many multiples higher than the outstanding balance,” Farside Investors remarked.
In addition, analyst Omar expressed doubts about Circle’s $5 billion valuation.
“Nothing to love in the Circle IPO filing and no idea how it prices at $5 billion,” he questioned.
He drew attention to several concerns, including the company’s gross margins being severely impacted by high distribution costs. The analyst also pointed out that the deregulation of the US market is poised to disrupt Circle’s position.
Additionally, Omar stressed that Circle spends over $250 million annually on compensation and another $140 million on general and administrative costs, raising questions about its financial efficiency. He also noted that interest rates—core income drivers for Circle—will likely decline, presenting additional challenges.
“32x ’24 earnings for a business that just lost its mini-monopoly and facing several headwinds is expensive when growth structurally challenged,” Omar said.
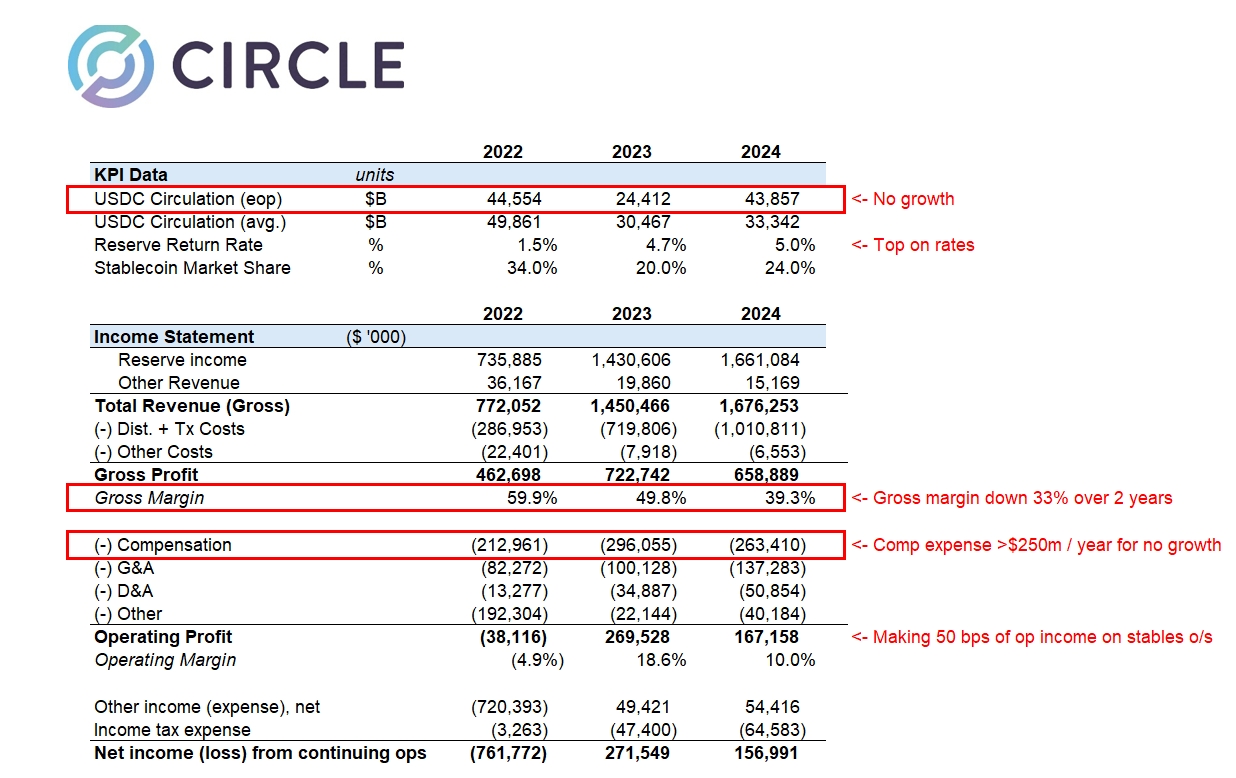 Analysis of Circle’s Valuation Ahead of IPO. Source:
X/Omar
Ultimately, the analyst concluded that the IPO filing was a desperate attempt to secure liquidity before facing serious market difficulties.
Meanwhile, Wyatt Lonergan, General Partner at VanEck, shared his predictions for Circle’s IPO, outlining four potential scenarios. In the base case, he forecasted that Circle would capitalize on the stablecoin narrative and secure key partnerships to drive growth.
In a bear case, Lonergan speculated that poor market conditions might lead to a Coinbase buyout.
“Circle IPOs, the market continues to tank, Circle stock goes with it. Poor business fundamentals cited. Coinbase swoops in to buy at a discount to the IPO price. USDC is all theirs at long last. Coinbase acquires Circle for something close to the IPO price, and they never go public,” Lonergan claimed.
Lastly, he outlined a probable scenario where Ripple bids up Circle’s valuation to a staggering $15 to $20 billion and acquires the company.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Expanding computing power on one hand, grabbing spectrum on the other! Barclays optimistic about SpaceX (SPCX.US) acquiring T-Mobile: Complementary advantages of ground networks and Starlink
After Space's stock price rose for two consecutive days, Barclays stated that T-Mobile is the "cleanest" choice among SpaceX’s potential acquisition targets. Barclays considers Verizon a major unknown, while AT&T has the lowest strategic fit.
Will the Federal Reserve raise rates in December? Tonight's CPI will be the final verdict!
The October CPI data will be released tonight, with the market pricing in an 86% chance of a rate hike. Goldman Sachs predicts a core CPI month-on-month increase of only 0.16%, much lower than market expectations. However, statistical distortions in health insurance and declines in used car prices—these "soft factors"—are unlikely to be reflected in the core PCE, which the Federal Reserve places greater emphasis on. The data may trigger a relief rally, but it is unlikely to change the underlying hawkish sentiment.

A 14x PE is not a bargain! Renowned wealth management CEO warns: If Nvidia (NVDA.US) earnings are revised down by 5%, its stock price could drop by 40%.
Ritholtz Wealth Management CEO Josh Brown questioned the idea that a 14x P/E ratio is a bargain and issued a warning: "If Nvidia's earnings over the next 12 months are revised down by 5% from our expectations, the stock could potentially drop by 40%."

Citibank: US beer sales will not bottom out by 2026, non-alcoholic beer is the only clear long-term growth track
Beer shipments in the United States have declined for the fifth consecutive year and are set to fall below 1980 levels. Citibank: Only non-alcoholic beer still has long-term growth potential.

Crypto prices
More


